


 23
/ 9 MIN READ

For many young Indians, a computer is no longer a device used only in a college laboratory or an office. It is where they attend classes, prepare assignments, learn software, edit videos, apply for internships, manage side projects and unwind. These overlapping uses are changing what buyers expect from personal computing and moving the market beyond the idea of a laptop as a work-only purchase.
Young consumers are not one uniform group. A school student, design aspirant, first-time job seeker and young professional may all be buying a personal computer, but their priorities differ. What connects them is the expectation that one device should support several parts of the day without demanding a major compromise on cost or usability.
The First Computer Has Its Own Significance
For many students, a personal computer is an investment in independence. They want to complete coursework without borrowing a family member’s device, join online classes, prepare presentations and organise files. As they move into higher education, requirements become more specific. A commerce student may need spreadsheets and research tools; a design student may look for creative applications; someone learning to code needs an environment in which to practise regularly.
The first purchase is therefore a decision that involves more than comparing prices. Buyers and their families want to know whether a device can run the applications they expect to use, remain useful as studies progress and offer reliable after-sales service. They are evaluating it against a list of tasks, not just a processor name or specification sheet.
Performance is measured in everyday use
Young buyers may compare specifications, but their experience is shaped by how a device performs across a full day. Can it run several browser tabs alongside a document? Does it start quickly? Can it handle a video call while notes are open? Will it support the applications they regularly use without slowing down? For students and young professionals, these everyday experiences often matter as much as the specifications on paper.
These everyday tasks indicate how well a device handles multiple activities and responds to regular usage demands. For students, this could mean attending online classes while accessing study material, preparing assignments, researching topics and switching between applications without disruptions. For young professionals, it could involve managing documents, virtual meetings and browser-based tools through the day. Ultimately, consistent performance and reliability in these situations often matter as much as the specifications on paper.
Portability and everyday convenience
Portability also matters because the device moves between a bedroom desk, classroom, library, coaching centre and shared workspace. Weight, battery life, screen quality, keyboard comfort and durability influence the decision alongside processing power and memory. Price remains important, particularly for first-time buyers and families managing education expenses. But value is not the lowest upfront price. A device that cannot support a learner’s regular applications, or becomes difficult to use as requirements grow, can prove a poor purchase. Brands need to explain what a product is designed to do, where its limits lie and which user it serves.
One device, several ambitions
Young consumers are increasingly balancing learning, creating and earning through their personal computers. A person might start the day attending classes, then continue editing videos in the afternoon, building their portfolio in the evening and working on freelance assignments, such as video editing or graphic design, at night. Others use computers to study languages, code, run an online business or prepare for competitive exams. This shift has changed how consumers evaluate a device’s capabilities. Multitasking, storage space, reliable internet connectivity, useful software and a comfortable user experience all contribute to how well a computer fits into everyday activities. The ability to switch between applications smoothly and manage multiple tasks efficiently can be just as important as raw performance.
Entertainment is also becoming an integral part of this computing experience, but the distinction between work and leisure isn't always clear-cut. For many young creators and professionals, the content they consume for enjoyment can also become a source of research and inspiration. A photographer might study the cinematography and framing of a film, a social media strategist might explore music for campaign ideas, or an event planner might draw inspiration from visual storytelling and performances. In these instances, entertainment and work are not separate activities; one often feeds into the other. Younger consumers therefore expect their devices to support not just content consumption, casual gaming and streaming, but also the creative exploration and research that can emerge from it.
What brands need to understand
Speed, design or low prices should not be the only aspects that are communicated through the campaigns regarding the product. The brand must know how young people use their gadgets and must state what problems each gadget solves. First-time buyers, in particular, need clear guidance on which features are essential for their needs and which specifications may not make a significant difference to their everyday experience.The young creative individual may pay more attention to the display, memory, and compatibility of applications.
Communication in retail or online stores is important as well. Demonstrations, helpful comparisons, and clear explanations can assist customers in making a decision, especially if they are buying a computer for the first time. The experience should also extend beyond the purchase, with accessible product guidance, easy-to-understand setup instructions and reliable after-sales assistance helping users make the most of their devices.
Another important shift brands need to recognise is that young consumers no longer fit neatly into fixed audience categories. Career paths are becoming increasingly fluid, with newer professions such as content creation and podcasting becoming established career choices. Individuals are also taking on multiple roles simultaneously. Someone might be pursuing an online MBA while working as a DJ and running a business, moving between being a learner, a creative professional and an entrepreneur. These roles often overlap, and so do the computing needs that come with them. Brands therefore need to look beyond conventional audience labels and understand the different ambitions, activities and workflows that shape how an individual uses their device.
Authored by:
Aman Verma, COO & Co-Founder, Primebook


A college student in Pune wants an iPhone with a genuinely good camera. A new one costs more than her monthly stipend can justify. A few years ago, her only real option would have been settling for a budget Android instead. Today, she has a third path that didn't really exist in any organised form a decade ago, a certified, warrantied, pre-owned iPhone at nearly half the price of new.
That shift, happening quietly across millions of similar decisions, is what's now being called India's upgrade economy, and the numbers behind it are hard to ignore. According to Counterpoint Research's Global Pre-Owned Smartphone Market Report for H1 2026, India's refurbished smartphone volumes grew 13 percent year on year in the first half of the year, even as sales of new smartphones actually fell by around 11 percent over the same period. That's not a small divergence. It suggests a genuine behavioural shift, not just budget conscious buyers settling for less, but buyers deliberately choosing better, older devices over newer, more expensive ones.
The same report found premium brands gaining ground specifically within the organised, certified segment of the refurbished market, a detail that matters more than it might seem. India's pre-owned electronics market has historically been dominated by unorganised sellers, roadside shops, informal resellers, classified listings with no real accountability if something goes wrong after the sale. Counterpoint's data puts the organised channel's share at roughly 20 percent of the total market, which sounds modest until you realise how much room that leaves for structured, trust-driven businesses to grow into.
This is really the crux of why the upgrade economy matters beyond just cheaper phones. Pre-owned technology has always existed in India. What's changing is the infrastructure around it, warranty coverage, quality certification, verification checks, and genuine after sales support, the same things that made buying new devices feel safe for decades.
A growing number of certified pre-owned platforms now illustrate this shift concretely. The stronger ones put every device through a documented, multi-point inspection covering hardware, software, battery health and cosmetic condition, alongside verification of activation lock status and device identity history, two checks that directly address the biggest fears buyers have historically had about used electronics, a stolen device, a hidden lock, a battery quietly dying within months. Many now offer up to twelve months of warranty, a short return window, and financing through EMI, features that used to be reserved almost exclusively for new device purchases. Trade-in and exchange programmes have also become common, letting customers put an older device toward a pre-owned upgrade, and some platforms operate physical stores in major cities, giving buyers somewhere to walk in and get support rather than relying purely on an online transaction with no recourse.
This model addresses something the broader market data hints at but doesn't fully explain on its own. Industry tracking through 2026 has repeatedly pointed to rising demand for higher-priced refurbished devices specifically, even as the cheapest segment of the refurbished market has been shrinking as a share of total sales. In other words, Indian buyers aren't gravitating toward pre-owned technology purely to save money at the bottom end. They're using resale and refurbishment markets to access premium technology they otherwise couldn't justify buying new, a phone with a great camera, a laptop capable of real creative work, a smartwatch with cellular connectivity.
That's a meaningfully different economy from the one refurbished electronics operated in a decade ago, when pre-owned essentially meant compromise. It's becoming a legitimate parallel path to ownership, one where the ceiling isn't "what can I afford new" but "what can I access certified and warrantied, at a price that makes sense."
What happens next likely depends on how much the organised segment of this market can grow relative to the unorganised one still handling roughly four out of every five refurbished transactions in the country. Trust, not price, is the actual bottleneck holding back faster adoption, and trust is built slowly, through certification standards, warranty follow through, and enough repeat customers willing to vouch for the experience.
For now, the trajectory looks fairly clear. As new device prices in India continue climbing, and certified pre-owned platforms continue building the infrastructure that makes pre-owned technology feel safe rather than risky, more buyers are likely to start their next upgrade not by asking which new phone to buy, but by asking which excellent, certified, pre-owned device they can now actually afford.
Authored by:
Manil Shetty, Managing Director, Maple Digital Technology
Scroll through any week of retail headlines in India and a pattern jumps out. A snack brand closes a Series B. A beauty label raises growth capital. A footwear chain files its draft papers. Consumer names such as Lenskart and Meesho have already made the leap from startup decks to the stock-market ticker, and a long line of D2C brands is watching closely.
For decades, retail success in India was built on reading the customer: what sells in Ludhiana versus Kochi, how festive demand shifts year to year, which SKU deserves the eye-level shelf. That instinct still matters. But a new layer of literacy is now being demanded of everyone in the business, from the founder pitching investors to the store manager who has just been handed ESOPs. They need to understand how markets price a business.
Market Literacy Is Becoming a Retail Skill
Three shifts are pushing capital-market fluency down the retail org chart.
Listed peers have become the benchmark. When Avenue Supermarts or Trent publishes quarterly numbers, the market's reaction tells every private retailer what investors value right now, whether that is same-store sales growth, margin discipline or store expansion pace. Founders who can read that reaction negotiate better in their own funding rounds.
Equity is reaching the shop floor. ESOP pools at funded D2C brands increasingly extend beyond the head office to category managers, regional leads and senior store staff. An employee who holds stock options but has never seen a share price move is holding something they do not fully understand.
Treasury decisions are getting sharper. Mid-sized retailers and franchise owners sitting on seasonal cash surpluses are asking where that money should sit between peaks. Making that call well requires a basic grasp of risk, liquidity and volatility.
The problem is that most retail professionals learned business on the floor, not on a trading screen. And the market is an expensive classroom when lessons are paid for with real money.
Retail Already Knows How to Rehearse
Here is the irony: retail is one of the industries most comfortable with rehearsal. Brands open pilot stores before a national rollout. They soft-launch a product in two cities before committing to a full production run. Merchandisers test planograms in a handful of outlets and watch the sell-through before redesigning every shelf in the chain.
The same logic applies to markets. Before putting capital at risk, it makes sense to run a pilot, and that is exactly what trading simulators offer: a live-like market environment where orders, price swings and losses are real in every sense except the financial one.
What a Simulator Actually Teaches
A good practice environment teaches lessons that no explainer video can.
- How orders behave. The difference between a market order and a limit order feels academic until you watch one fill at a price you did not expect.
- What volatility feels like. Seeing a position swing several percent in an afternoon builds a gut sense of risk that a spreadsheet cannot.
- Position sizing. Retailers understand inventory exposure intuitively. Simulators translate that instinct into how much capital to commit to a single idea.
- Emotional discipline. The urge to exit too early on a small gain, or hold too long on a loss, shows up even with virtual money. Better to meet that urge in practice.
The barrier to starting has also dropped sharply. Many tools now run straight in the browser, and some go as far as offering demo trading without account registration, so there is no sign-up form, no KYC and no personal data to hand over. For a busy store manager, that means a fifteen-minute session during a lunch break rather than an afternoon of onboarding. For a training team, it means an entire batch of employees can try the same exercise in a workshop without anyone creating a login.
Choosing the Right Practice Ground
Low friction is useful, but the practice ground still matters, because habits formed in a simulator tend to follow people to the platform they eventually trade on. A few principles help.
Stay inside the regulated ecosystem. India offers solid practice options built around SEBI-regulated markets, including NSE's own learning and virtual-trading initiatives and the paper-trading modes that many SEBI-registered brokers provide inside their apps. Practising on instruments and rules you will actually use is far more valuable than practising on something you never should.
Check before you click. The Reserve Bank of India maintains a public Alert List of platforms that are not authorised to offer forex trading to Indian residents, and SEBI publishes registers of authorised intermediaries. A two-minute check is the retail equivalent of verifying a new supplier's GST number.
Be wary of practice tools built to convert. A simulator that constantly nudges you towards depositing money, promises guaranteed returns, or pushes leveraged forex and binary-style bets is a sales funnel, not a classroom.
Treat it as training, not a game. The point is to build judgement. Keeping a simple log of each trade, the reason behind it and the outcome turns play into learning.
A 30-Day Plan for Retail Teams
For founders and HR leads who want to build market literacy into their teams, a simple monthly structure works well.
- Week 1: Foundations. Short sessions on how exchanges work, what moves a share price, and how to read a listed retailer's quarterly results.
- Week 2: First trades. Each participant builds a small virtual portfolio of listed consumer and retail companies they know from the floor.
- Week 3: Stress test. Track the portfolio through a results season or a market-moving event and discuss what happened and why.
- Week 4: Reflection. Review trade logs together. Which decisions were driven by analysis, and which by emotion? What would the team do differently with real capital?
The cost is close to zero. The payoff is a team that understands its own ESOPs, reads competitor results with sharper eyes, and speaks the same language as the investors funding the next stage of growth.
The Retail Lesson, Applied to Markets
Every experienced retailer knows the rule: test small, learn fast, then scale. It is how winning formats are born and how costly mistakes are avoided. As Indian consumer businesses move deeper into the world of capital markets, the people who build them would do well to apply that same rule to their own financial learning.
The next big retail listing will be celebrated on the floor of the stock exchange. The people best placed to benefit from it will be the ones who rehearsed long before the bell rang.
The Indian beverage market is witnessing changes. With a growing interest in alternative options to carbonated soft drinks, there are now a variety of options available on the shelf, including colas, fruit-flavored drinks, fizzy drinks, energy drinks, and even low-sugar products.
Factors such as cost, availability, and chilled options are becoming increasingly important to the market. However, with traditional colas still being very popular, energy drinks are gaining momentum along with new drink formats.
India Energy Drink Market Share, Companies & Trends Report (2026-2031) by Ken Research: India Energy Drink Market is valued at USD 1.135 billion in the year 2026 and is expected to reach USD 2.245 billion by the year 2031, at a CAGR of 12.04 percent.
The market is largely consolidated, with companies such as PepsiCo India (Sting), Red Bull India, Monster Beverage Corporation (Monster Energy and Predator), Reliance Consumer Products (Campa Energy), and HELL ENERGY competing across affordable Rs 20 PET bottles and premium canned products.
Also read: From Organic Hampers to Personalised Gifts
Energy Drinks Gain Momentum
Energy drinks are growing faster than traditional carbonated soft drinks, although colas continue to account for a significant share of the market.
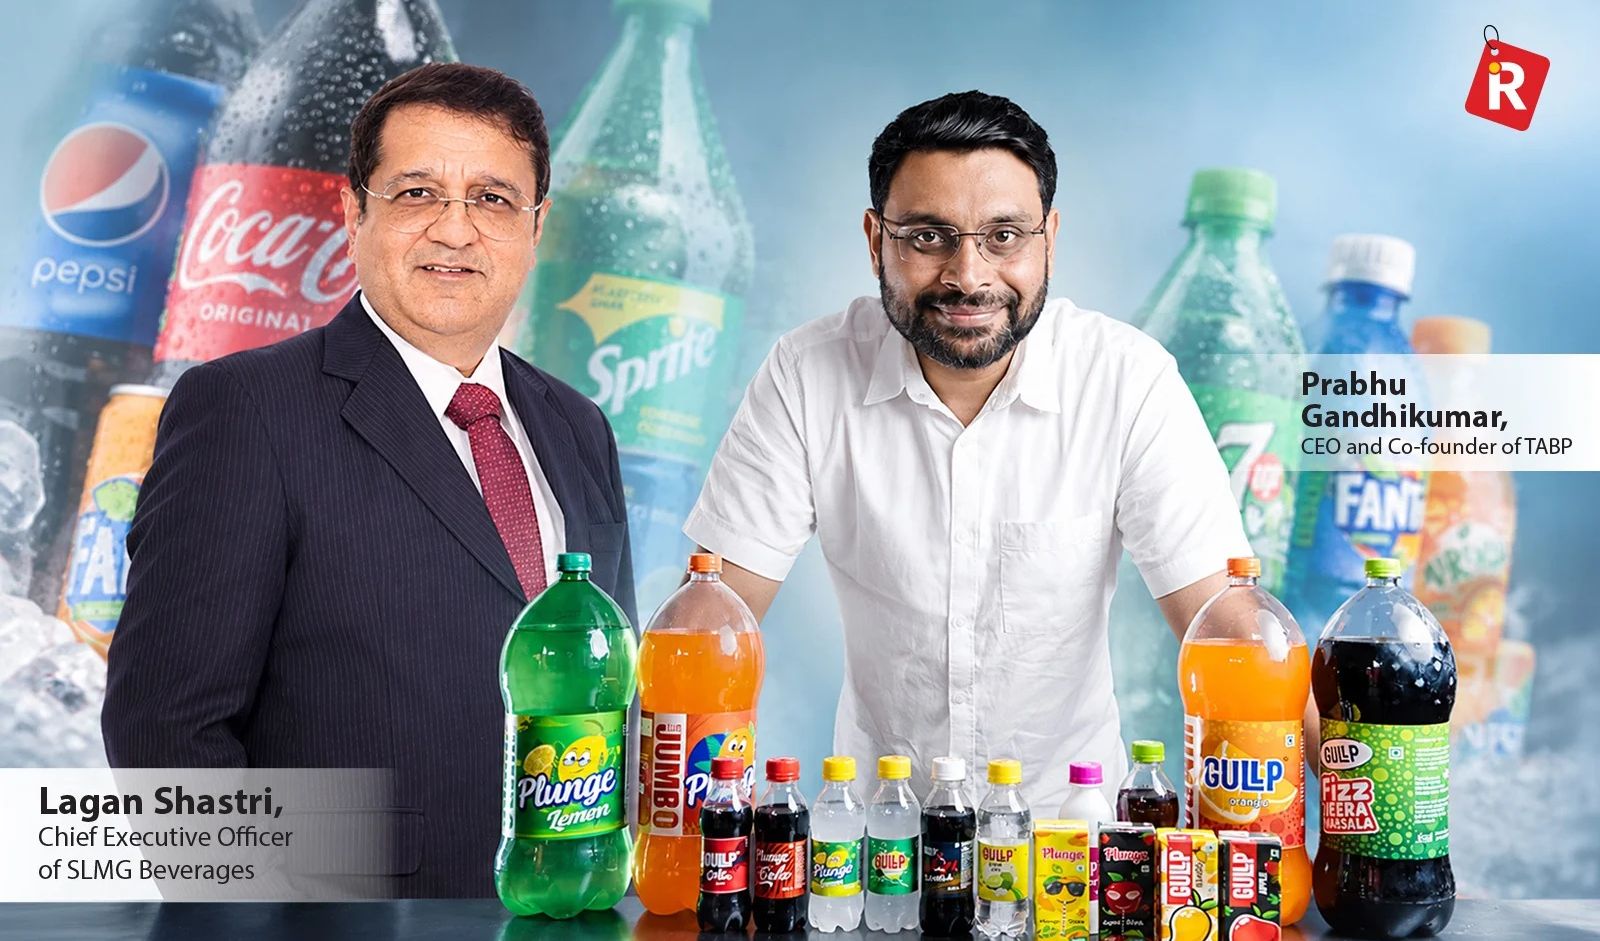
Prabhu Gandhikumar, CEO and Co-founder of TABP, said, “Euromonitor estimates that India’s energy drink volumes grew by 21 percent in 2025. Affordable formats are helping the category reach consumers who would previously have found it expensive to try.”
He added that this should not be seen as a complete shift away from colas, as consumers purchase different beverages for different occasions.
Lagan Shastri, Chief Executive Officer of SLMG Beverages, said, “Energy drinks are expanding faster from a smaller base, while colas retain substantial scale. Younger consumers, new consumption occasions, chilled availability and greater choice are supporting growth across both segments.”
Also read: Diwali Brings Growth in Furniture and Home Decor Sales
Low-Cost Packs Gain Traction
Price continues to play an important role in India's beverage market, particularly in smaller towns and rural areas. Single-serve packs and affordable price points are helping brands reach consumers who prefer making small, frequent purchases.
Shastri said, “Affordable single-serve packs are a key growth driver. Consumers value accessible price points and convenient, immediate consumption, reinforcing the importance of the right pack-price architecture and widespread chilled availability.”
For TABP, the Rs 10 price point remains its best-selling and fastest-moving offering. Gandhikumar explained that consumers often make purchasing decisions based on the amount they can comfortably spend at a particular time, rather than the value per litre offered by larger packs.
He said the company has also introduced a Rs 10 mojito, following the same approach of offering different flavours at accessible prices.
Also read: India’s Alco-Bev Market Sees Festive Push as Premium Spirits Gain Ground
 Expanding Retail Reach
Kirana stores, neighbourhood shops and bakeries remain key beverage sales channels, while quick commerce is emerging as an additional avenue for wider retail distribution and growth.
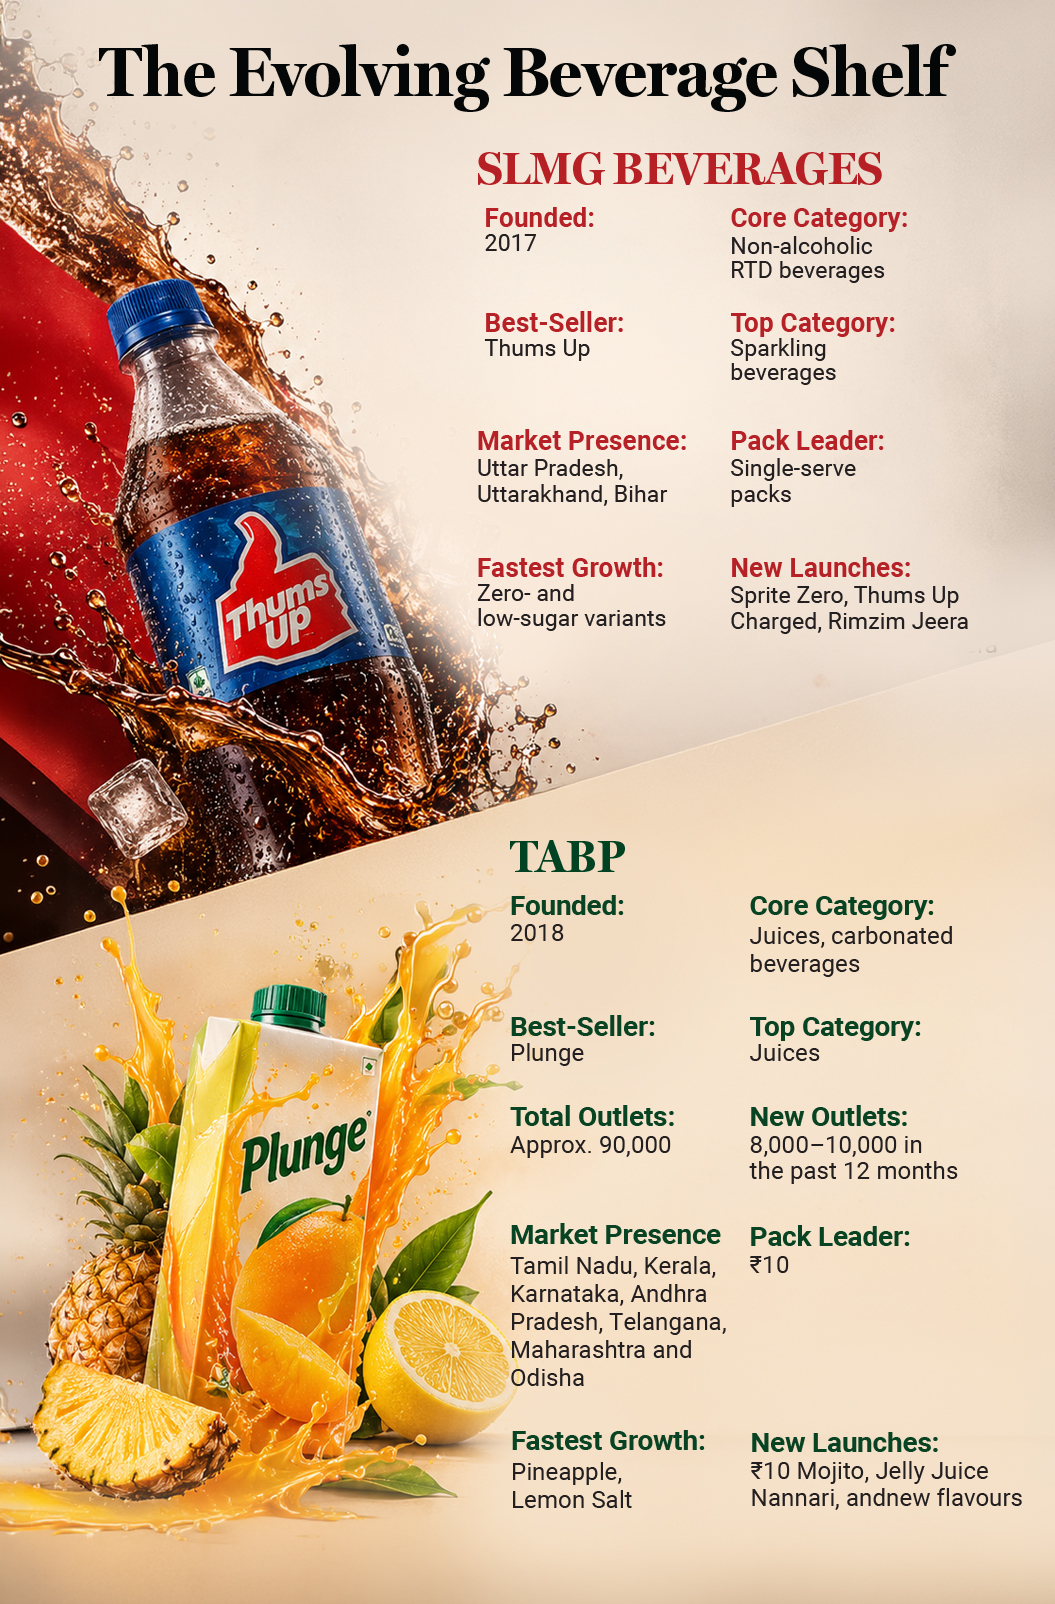
According to Gandhikumar, TABP added approximately 8,000–10,000 retail shops over the past 12 months, taking its estimated presence to around 90,000 shops across Tamil Nadu, Kerala, Karnataka, Andhra Pradesh, Telangana, Maharashtra and Odisha.
He said, “For the consumer we serve, the nearby shop is an important point of purchase. Our distribution decisions therefore begin with local demand, the right assortment and dependable replenishment.”
Shastri also highlighted the growing role of quick commerce but said kiranas remain the distribution backbone. He added that the company is working with The Coca-Cola Company to improve availability, channel-specific assortments and digital activation.
Also read: Diwali Demand Puts India’s Home Appliance Market on a Premium Growth Path
Changing Beverage Preferences
Consumers are exploring diverse beverage options, including fruit-based, sparkling, energy and zero-sugar drinks, choosing products based on changing preferences and consumption occasions.
Shastri said, “Consumer preferences are broadening, not simply shifting away from cola. Sparkling, fruit-based, energy and zero-sugar choices serve different occasions.”
At SLMG Beverages, sparkling beverages remain the principal contributor to portfolio growth. The company operates across Uttar Pradesh, Uttarakhand and Bihar, with Thums Up among its best-selling products. Its newer offerings include Sprite Zero, Thums Up Charged and Rimzim Jeera. Zero- and low-sugar variants are also among its faster-growing segments.
For TABP, juices remain the largest category, with Plunge as its best-selling brand. Pineapple and lemon salt are currently its fastest-growing products. Founded in 2018, the company focuses on juices and carbonated beverages and has expanded its portfolio to include jelly juice, additional flavours and nannari.
Also read: How India’s Edible Oil Market Is Evolving
Growth
As well as energy drinks, the market for non-alcoholic ready-to-drink products in India is growing. This includes soft drinks, fruit drinks and packaged waters. The market was estimated by Redseer to be worth USD 20 billion in 2025 and expected to grow to USD 40 billion by 2030, growing at approx. 14 percent per annum.
Gandhikumar said he expects an average growth rate of 12-15 percent per annum for the next couple of years, although weather can impact the market.
As prices of packs have become more affordable, the market has broadened with more variety. Whilst traditional cola markets remain strong, there are many new growth opportunities with energy drinks, fruit-based and low-sugar products.
Also read: Small Feet, Big Business: Kids’ Footwear Steps Up Growth
The festive season has traditionally been one of the biggest shopping periods for India's fashion and retail industry. From new clothes and footwear to accessories and festive essentials, consumers have always looked forward to making purchases during this time. However, the 2026 festive season revealed a noticeable shift in shopping behavior. Indian consumers continued to participate in festive sales, but they became more careful about how much they spent, what they purchased, and where they shopped.
Indian shoppers are increasingly moving towards value-driven fashion commerce, according to Fynd's Report. While festive shopping remained strong, consumers were no longer buying simply because discounts were available. Instead, they were comparing prices, looking for better deals and prioritizing products that offered practical value.
Value Takes Priority as Consumers Become More Selective
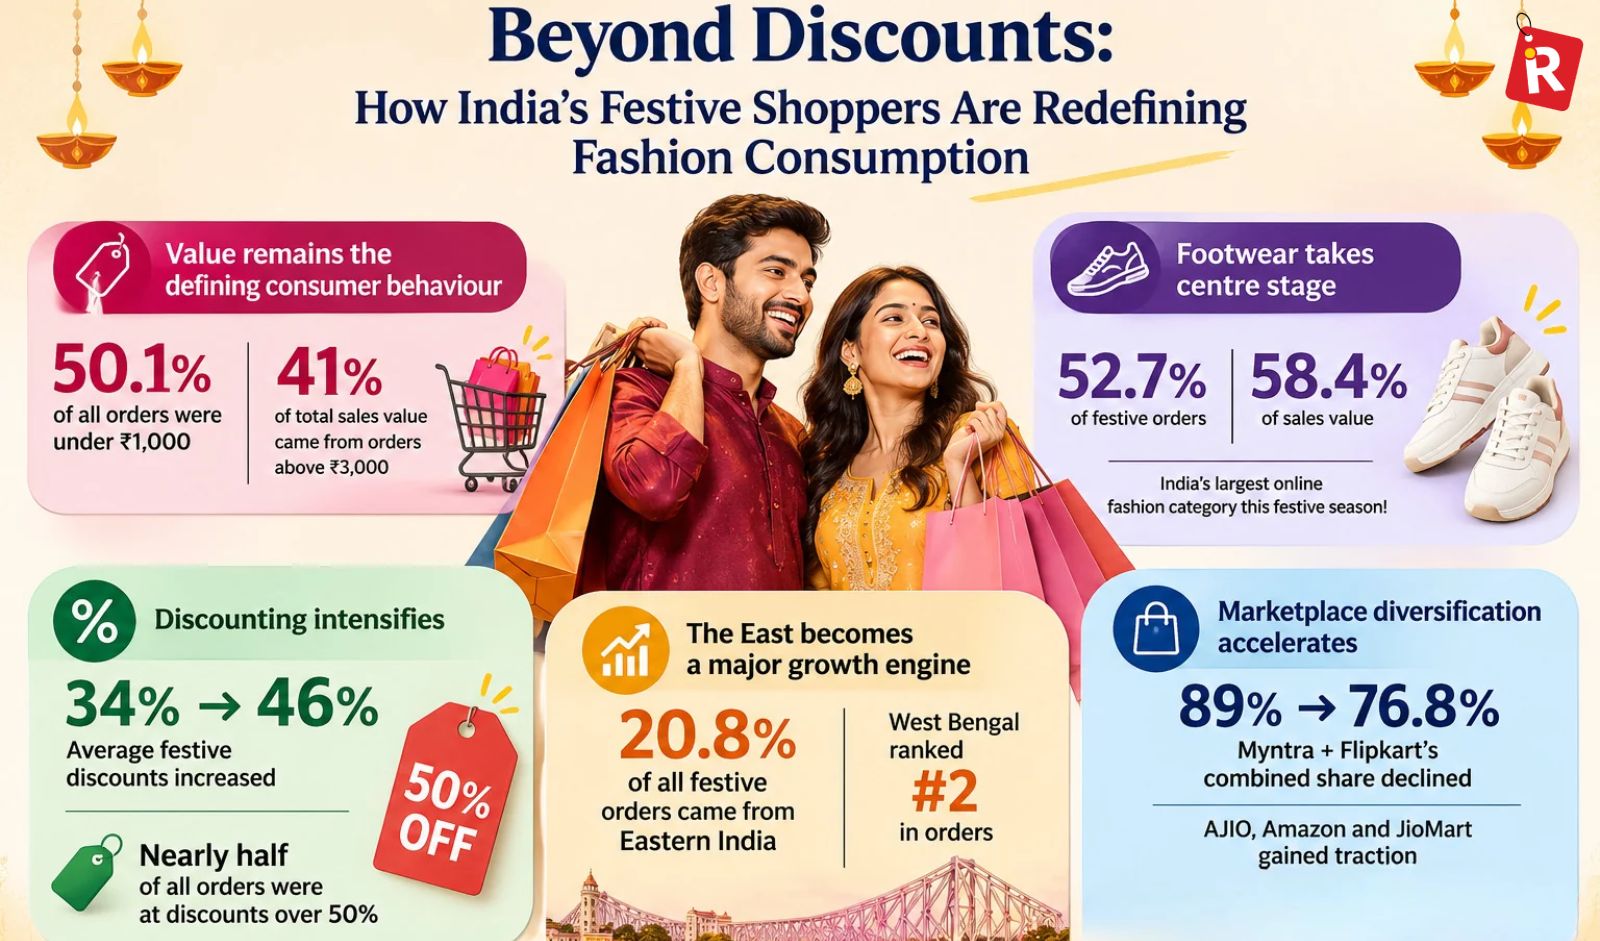
One of the biggest findings of the report is the growing importance of affordability. Around 50.1 percent of all festive orders were placed below Rs 1,000, indicating that a large number of consumers preferred keeping their purchases within an accessible price range.
However, this does not mean Indian shoppers have stopped spending on premium products. Orders above Rs 3,000 accounted for only 11.8 percent of total purchases but contributed more than 41 percent of the overall sales value. This shows that consumers are still willing to spend on higher-priced products when they see value in the purchase.
Footwear Emerges as the Biggest Fashion Category
Another major highlight of the report is the growing popularity of footwear. During the 2026 festive season, footwear accounted for 52.7 percent of all festive orders and contributed 58.4 percent of total sales value.
This marks a significant change from 2025, when footwear represented just 33 percent of festive orders. The growing preference for footwear suggests that shoppers are increasingly prioritizing products that can be used beyond the festive season. Unlike occasion-specific clothing, footwear often serves both everyday and special-occasion needs, making it a practical investment for consumers.
Meanwhile, clothing's share of festive orders declined from 48 percent in 2025 to 34.5 percent in 2026. This does not necessarily indicate a decline in interest in fashion. Rather, it points towards consumers becoming more selective about discretionary clothing purchases.
Bigger Discounts, Smarter Shopping
Discounts continued to play an important role in influencing festive purchases. However, brands had to offer more attractive deals to capture consumer attention. According to the report, average festive discounts increased from 34 percent to 46 percent. Nearly half of all orders were placed at discounts exceeding 50 percent.
This indicates that consumers were actively looking for promotions and were increasingly sensitive to pricing. At the same time, deeper discounting also puts pressure on retailers to balance sales growth with profitability.
The report suggests that the future of festive retail will depend not just on how much brands discount their products, but also on how effectively they understand customer expectations.
Eastern India Becomes a Strong Growth Market
Regional shopping patterns also revealed an important shift during the festive season. Eastern India emerged as one of the strongest growth markets, contributing 20.8 percent of all festive orders.
West Bengal became India's second-largest ordering state, highlighting the growing importance of the region in online fashion commerce. This development reflects the expanding reach of digital marketplaces and the increasing participation of consumers beyond traditional metropolitan markets. It also presents an opportunity for brands to rethink their regional strategies.
Tier II Cities Drive the Next Wave of Demand
Beyond regional growth, smaller cities are becoming increasingly important for India's fashion industry. The contribution of Tier II cities to festive orders increased from 19 percent in 2025 to approximately 35 percent in 2026. This sharp rise highlights how online fashion shopping is expanding beyond India's largest urban centres.
Tier I cities continued to contribute approximately 43 percent of total orders and 56 percent of gross merchandise value (GMV). However, the growing contribution from Tier II markets signals a wider consumer base and new opportunities for brands.
Marketplace Preferences Continue to Evolve
The report also highlights a shift in how consumers are choosing online shopping platforms. Myntra and Flipkart continued to lead the fashion marketplace landscape. However, their combined share declined from 89 percent to 76.8 percent during the festive season.
At the same time, platforms such as AJIO, Amazon and JioMart gained traction, indicating that shoppers are exploring more options before making a purchase.
This growing marketplace diversification is important for brands. Depending heavily on one or two platforms may limit their ability to reach different customer segments. A wider marketplace presence can help brands improve visibility, connect with new shoppers, and reduce dependence on individual sales channels.
Digital Payments Gain Momentum
Payment preferences also continued to change during the 2026 festive season. Online payments accounted for 56.5 percent of all orders, reflecting the growing acceptance of digital payment methods.
Prepaid adoption also increased across Eastern markets, indicating a shift in consumer payment behaviour in these regions.
As more consumers become comfortable with prepaid transactions, brands can also explore ways to encourage digital payments through relevant offers and a seamless shopping experience.
Returns Remain an Important Retail Challenge
While festive demand remained encouraging, managing returns continued to be an important concern for fashion retailers.
The overall return rate stood at 11.8 percent during the festive season. Clothing recorded a category-wise return rate of 14.9 percent, while footwear reported a lower return rate of 10.5 percent.
These numbers highlight the need for brands to focus on product information, accurate sizing, quality checks, and better product representation online. Reducing returns is not just about controlling operational costs. It is also about improving customer satisfaction and building long-term trust.
What the 2026 Festive Season Means for Retailers
Commenting on the findings, Ragini Varma, Chief Business Officer - India, Fynd said, “This festive season unfolded against a very different backdrop. Consumers were navigating higher borrowing costs, elevated fuel prices, global geopolitical uncertainty, and continued pressure on household budgets. In that environment, value emerged as the defining theme of the season. Shoppers compared more, planned purchases more carefully, and looked for products that justified their spend. For brands, the opportunity is not simply to sell more, but to understand how customer priorities are evolving and deliver the right value, assortment and experience at the right moment.”
The findings point towards a clear shift in India's fashion retail market. Consumers are still interested in festive shopping, but their expectations are changing. Affordability, product utility, discounts, convenient payments, and regional relevance are increasingly influencing purchase decisions.
For retailers, the next phase of growth will require a more thoughtful approach to commerce. Diversifying marketplace presence, developing stronger regional strategies, planning discounts more carefully, encouraging prepaid payments, and understanding category-specific demand will become essential.
Ultimately, the future of fashion commerce will not be defined by the biggest discounts or the highest number of orders. It will be shaped by how well brands understand the value their customers are looking for.
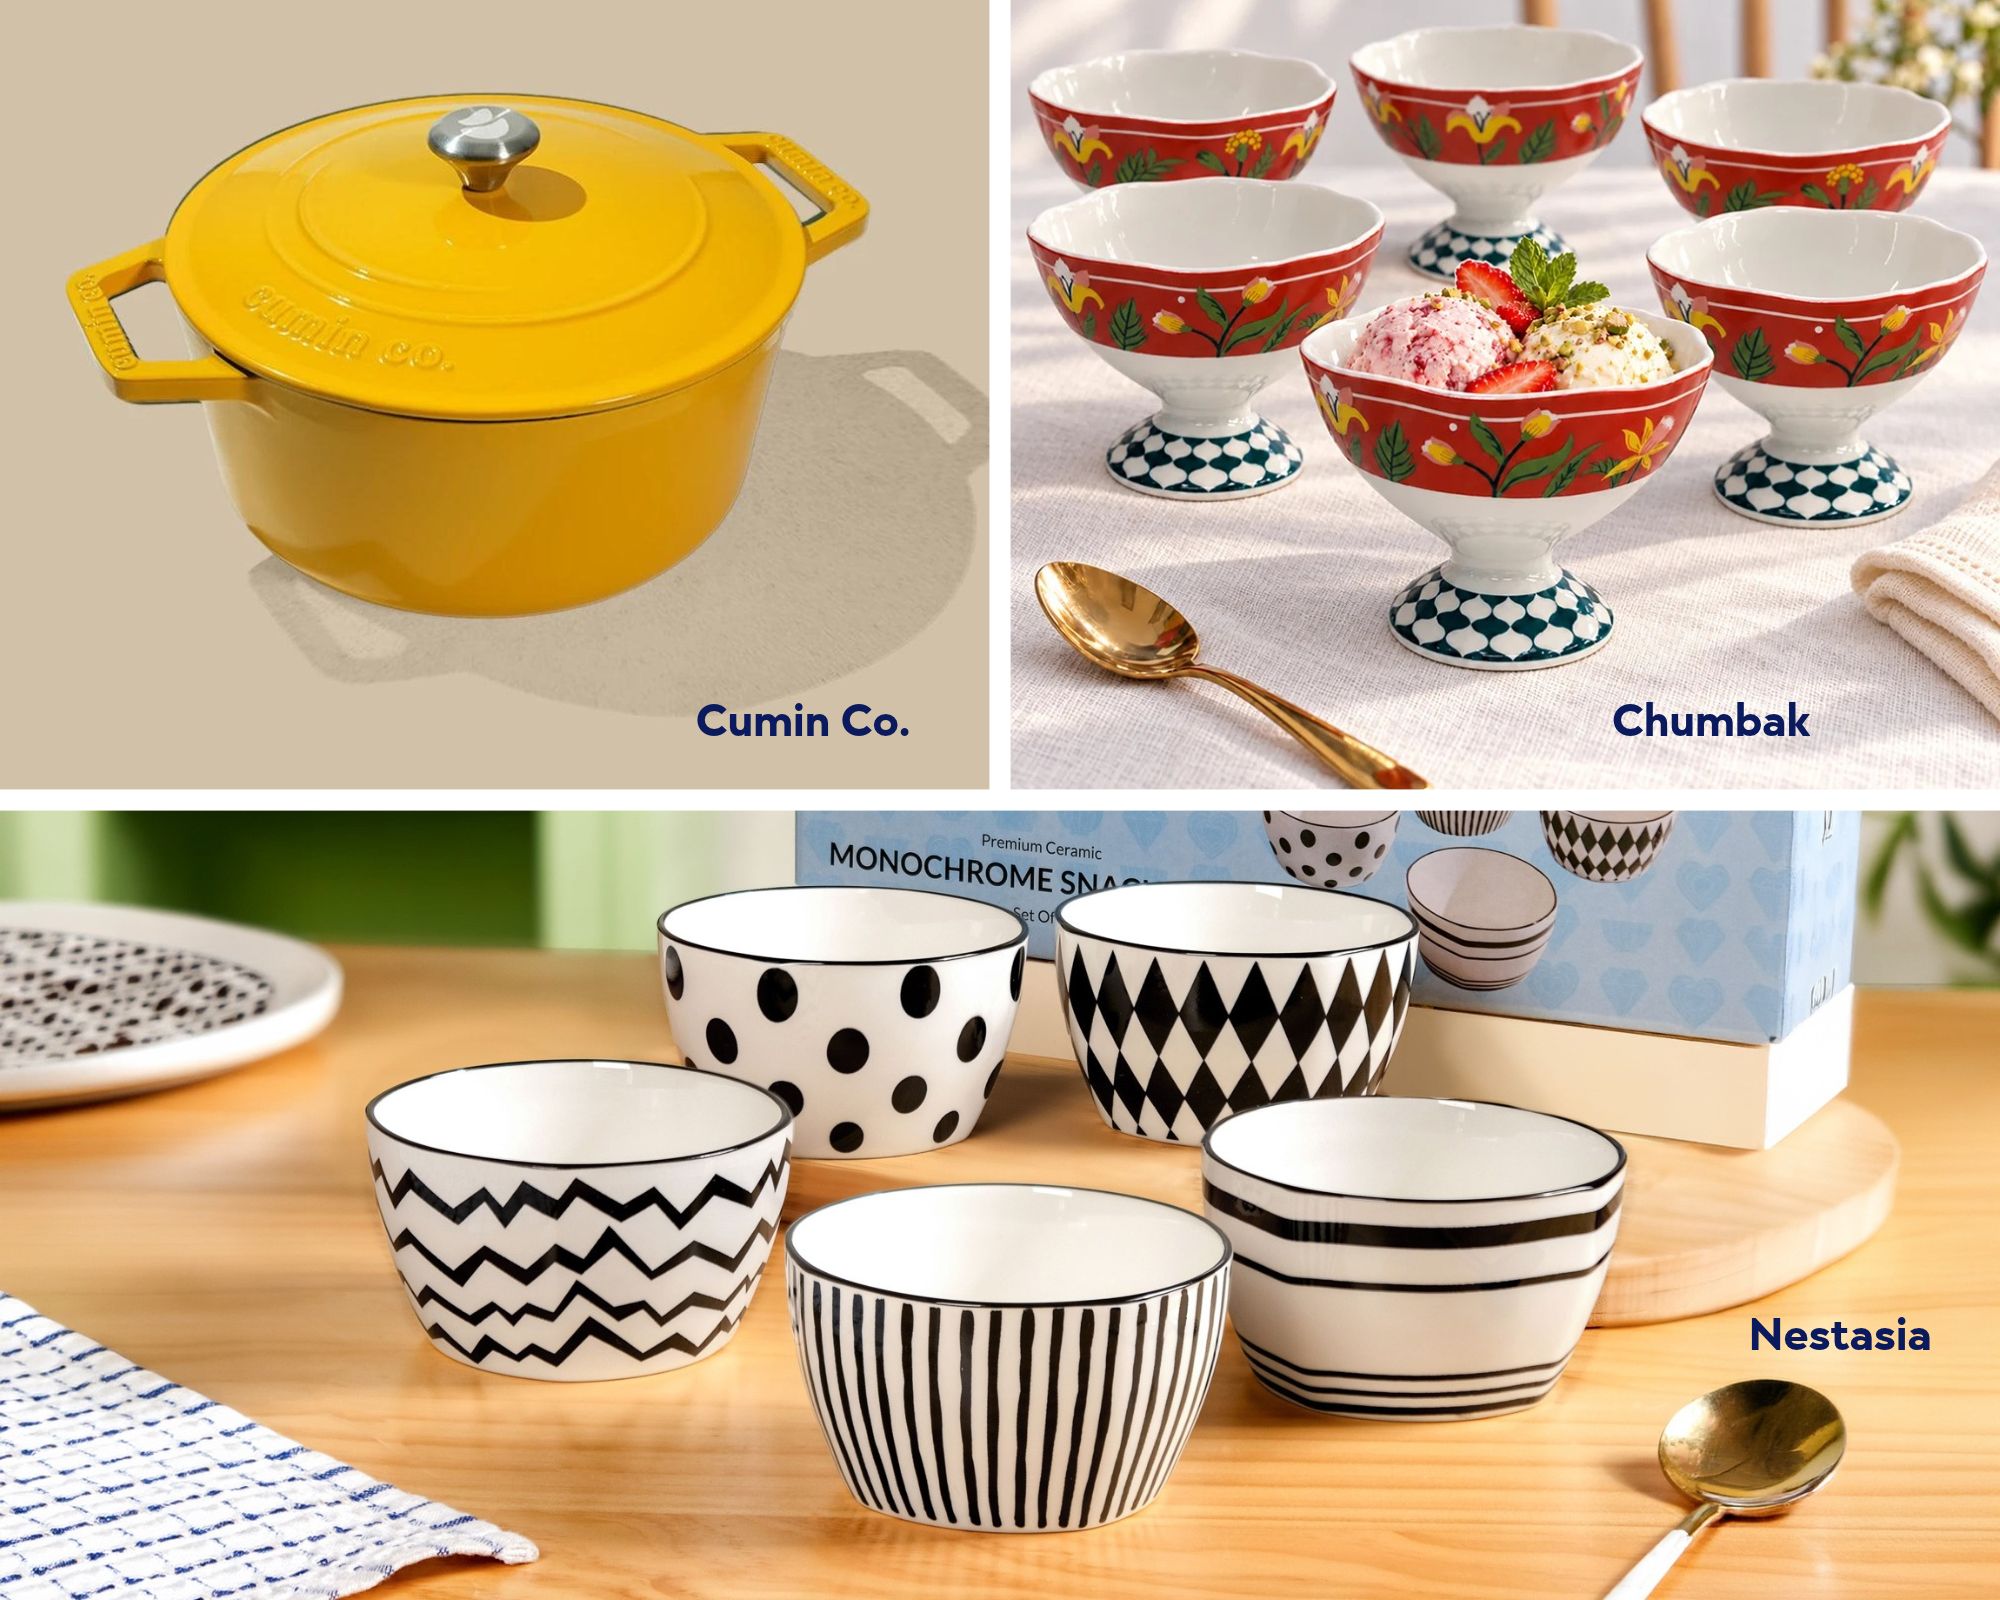
The dining table is becoming something more than a place to serve food. Indian consumers are increasingly focusing on the way their dining spaces look and feel, be it well-chosen plates and bowls, matching serveware, or chic table settings.
From home entertaining to festive occasions, gifting, or changing home décor tastes, dinnerware is moving from a household staple to a lifestyle choice, creating new opportunities for design-led brands.
Growth in the Market and Shifting Consumer Preferences
The dinnerware market in India is witnessing steady growth due to increasing demand for premium, design-led, and functional products.
The overall tableware market is expected to grow at a CAGR of 4.9 percent from 2025 to 2030, whereas the ceramic tableware is anticipated to register around 10 percent CAGR from 2025 to 2029.
Changing lifestyles, home hosting, gifting, and growing interest in home décor are helping to transform dinnerware from a household necessity to a lifestyle and personal expression category.
Also read: From Organic Hampers to Personalised Gifts
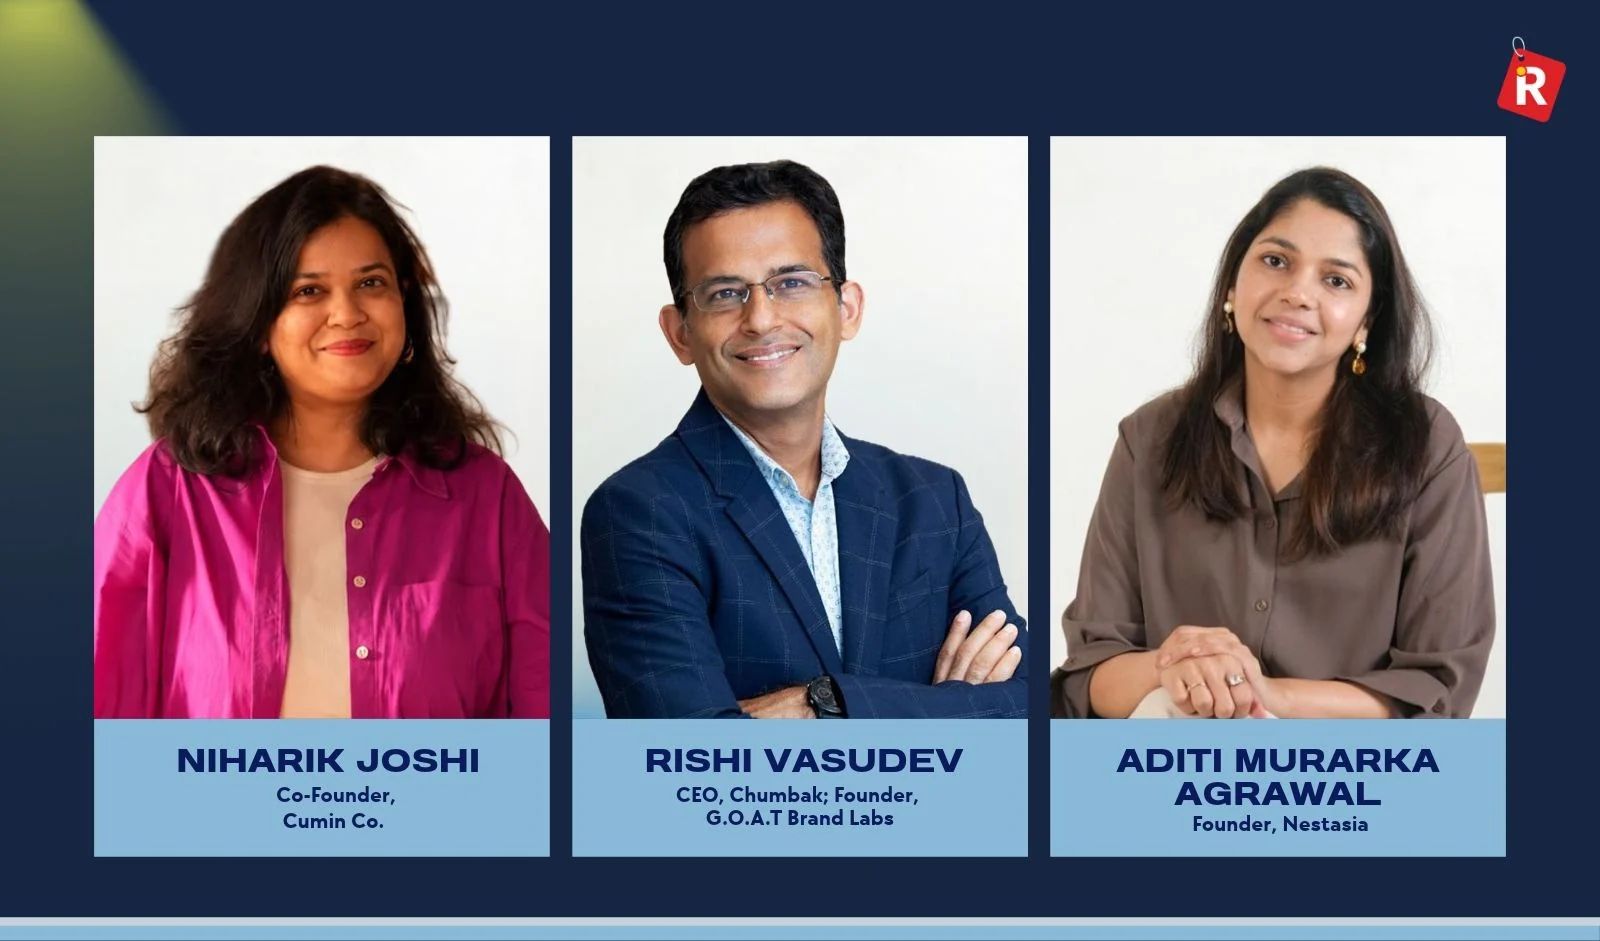
Niharik Joshi, Co-founder of Cumin Co., said, "The dinnerware category in India is growing rapidly, and we're seeing a very interesting shift in the way consumers approach it. Traditionally, dinnerware was largely a functional purchase. Today, it is increasingly becoming a lifestyle."
She highlighted the resurgence of home hosting as a key driver of this shift. Consumers are increasingly inviting friends and family over for meals and investing in products that reflect their personal taste and home aesthetics.
"People want their dinnerware to reflect their aesthetic, their taste, and the kind of experience they want to create for their guests," Joshi added.
Also read: Diwali Brings Growth in Furniture and Home Décor Sales
Raising the bar and purchasing inspired by design
The increasing importance of aesthetics is also playing a role in purchase decisions across price segments. There is a high level of interest among consumers for unique designs and aesthetic finishes.
"The demand for products in the Rs 500 to 2000 range has been great. The dinnerware sets and statement pieces have a lot of interest," said Rishi Vasudev, CEO at Chumbak and Founder at G.O.A.T. Brand Labs. At the same time, consumers are increasingly willing to spend more on distinctive designs, better finishes, and products that feel special."
A similar trend is evident at Nestasia, where consumers are increasingly judging products on their design, material, detailing, and overall finish, as opposed to their utility.
Aditi Murarka Agrawal, founder of Nestasia, said, "The strongest shift we are seeing is that consumers are naturally moving towards better-designed products and aspiring to create better, more considered homes."
She added that premiumization is not simply about purchasing expensive products but about choosing better-quality and thoughtfully designed products that enhance the overall home experience.
Also read: India’s Alco-Bev Market Sees Festive Push as Premium Spirits Gain Ground
 Home hosting and gifting drive demand
Demand for dinnerware beyond everyday use is driven by weddings, holidays, gift-giving, and entertaining at home.
Consumers are increasingly opting for coordinated dining collections, serveware, glassware, and table accessories, while the growing trend of hosting gatherings at home is encouraging greater spending on table settings and dining presentation.
According to Agrawal, festive and wedding gifting remain important opportunities for the category. Nestasia is witnessing demand for curated assortments, occasion-led collections, festive products, and gift sets.
"The gifting experience itself has also evolved. It is no longer just about what is inside the box. The packaging, how the gift is presented, and the unboxing experience have become important parts of the overall experience," she said.
She further observed that consumers are putting more effort into home entertaining, with table settings, serveware, glassware, barware, and décor becoming important elements of hosting.
Chumbak is also witnessing growing demand for dining and drinkware products as year-round gifting options. Vasudev said dinnerware is increasingly becoming part of home décor, with consumers selecting products for their kitchen counters and crockery cabinets.
Also read: Diwali Demand Puts India’s Home Appliance Market on a Premium Growth Path
Growth in Online and Off-Line Retail
The rise of digital commerce and organized retail is also facilitating consumer engagement with dinnerware brands. While online channels offer wider product selections, physical stores allow consumers to experience designs, materials, and finishes before purchasing.
At Chumbak, online and offline channels contribute equally, with each accounting for 50 percent of sales. The company has an average selling price of around Rs 1,000 and operates more than 30 stores across 15-plus cities. Its best-selling product is the Marigold Kulhad Set of 4, priced at Rs 1,599.
Vasudev said the brand is strengthening its omnichannel presence across metros and emerging markets, including Guwahati, Visakhapatnam, Amritsar, and Kochi. The company is also using Chumbak Now to provide two-hour delivery. Its plans include expanding home and living categories, strengthening gifting-led collections, and reaching more consumers in emerging markets.
Also read: How India’s Edible Oil Market Is Evolving
Nestasia, meanwhile, has a predominantly online-led business, with approximately 90 percent of its sales coming through its website, e-commerce marketplaces, and quick commerce. Its offline stores contribute the remaining 10 percent.
Following its latest store opening in Jaipur, the company has 16 stores across India. Its existing network includes locations in Noida, Chandigarh, Dehradun, Pune, Hyderabad, Bengaluru, Delhi, Gurugram, and Kolkata.
The company plans to expand to 20 exclusive brand outlets (EBOs) by the end of FY27 and approximately 80 by the end of FY28. It is also exploring modern trade as an additional distribution channel.
Also read: Small Feet, Big Business: Kids’ Footwear Steps Up Growth
Safety and Use Importance Gained
Alongside design and premiumization, consumers are also becoming more conscious of product materials and food safety. Awareness around food-safe materials, lead-free glazes, and safe finishes is gradually influencing purchase decisions.
Joshi said, "Consumers may first be drawn to a product because of its design, color, or finish, but they're increasingly asking questions about what goes into making it."
"Consumers no longer want to compromise between aesthetics, functionality, and safety. Convenience is also gaining importance, particularly through the stove-to-table concept, where cookware can move directly from the kitchen to the dining table," she added.
Also read: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Expanding the Home and Kitchen Opportunity
Looking ahead, brands are seeking growth beyond traditional plates and bowls by expanding into serveware, glassware, cookware, drinkware, and kitchen accessories.
Nestasia plans to deepen its presence in bottles, lunch boxes, kitchen tools, storage containers, and cookware while expanding its retail network. Chumbak is focusing on gifting-led dinnerware and décor collections, along with new home and living categories.
India’s tableware market is creating opportunities for established and emerging brands, with overall growth projected at 4.9 percent CAGR and ceramic tableware at 10 percent.
Rising focus on home décor and personal expression is expected to drive demand for design-led, quality, safe, and convenient products.
Also read: India’s Rice Market: From Everyday Staple to Branded Growth Opportunity
India's Diwali gifting market is changing as consumers move beyond traditional sweets and dry-fruit boxes to explore healthier snacks, organic products, home fragrances and personalised gifts. While mithai and namkeen continue to be popular, consumers are increasingly looking for gifts that offer quality, good presentation and everyday use.
Brands are also seeing growing interest in customised hampers, premium packaging and corporate gifting. From organic food boxes to scented candles and lifestyle products, the festive gifting market is expanding into new categories.
According to PwC India's 2025 Voice of the Consumer study, 84 percent of Indian consumers seek safer and healthier food choices. This growing awareness is also influencing what people choose to gift during festivals.
Also read: Malgudi: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Healthier Gifts Gain Popularity
Consumers are paying more attention to ingredients and product quality while choosing festive gifts. Organic foods, dry fruits, seeds, honey, ghee and healthy snacks are finding space in Diwali hampers.
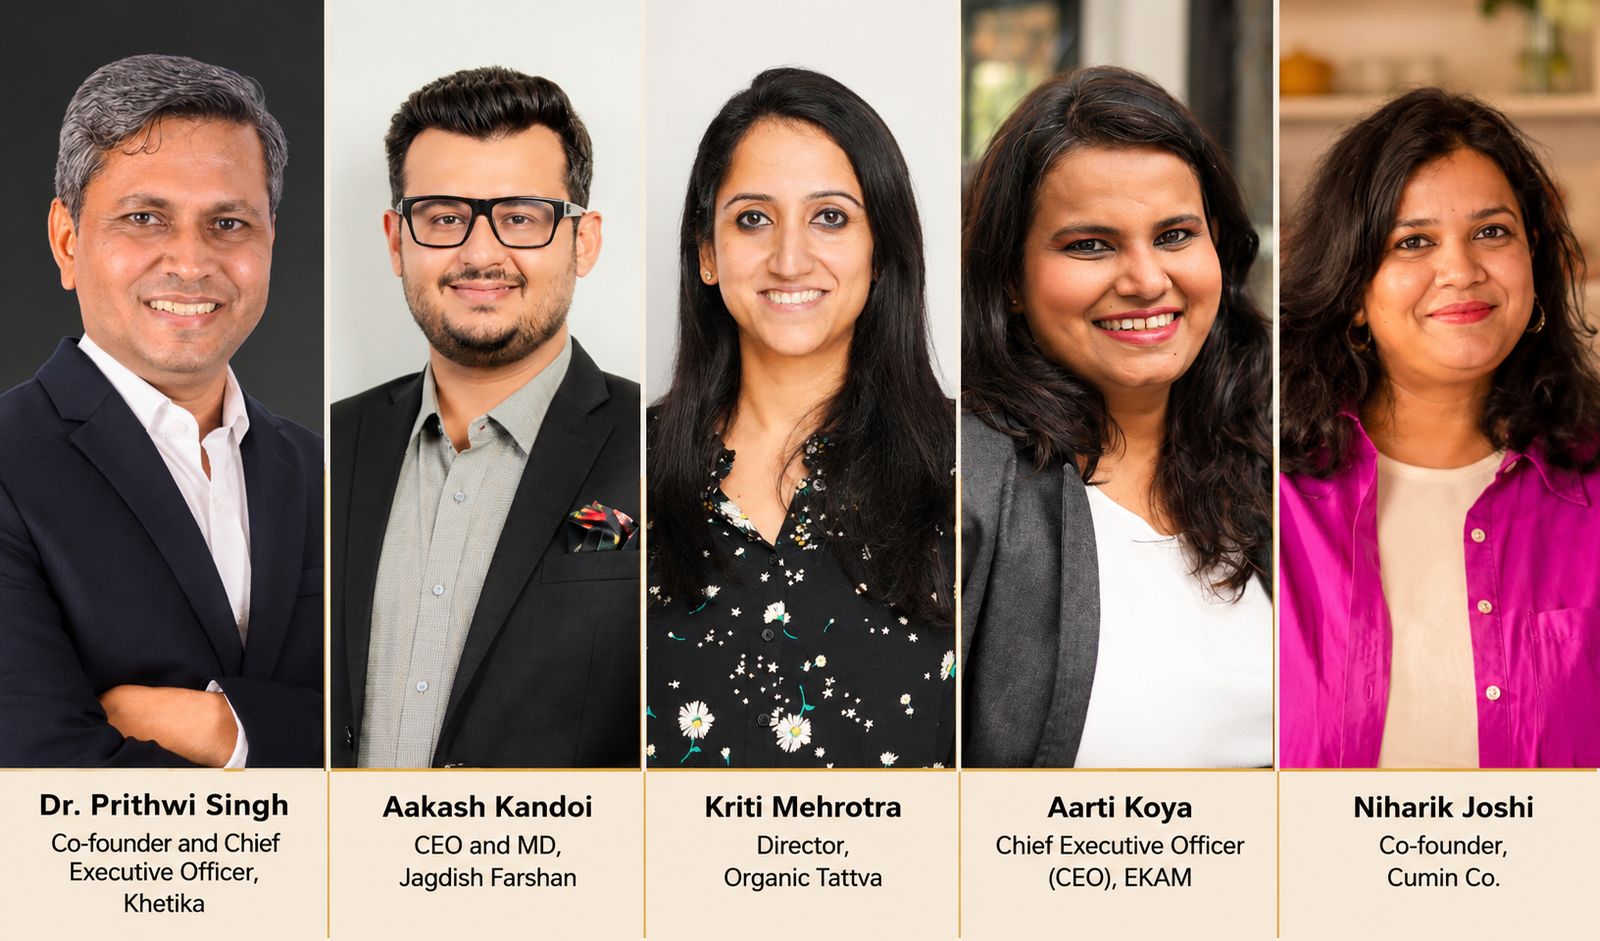
Dr. Prithwi Singh, Co-founder and CEO of Khetika, said, "Diwali gifting is gradually moving beyond conventional sweets and standard dry-fruit hampers. Consumers are increasingly looking for gifts that combine quality, good taste and a greater sense of wellbeing."
He said Khetika's Premium Snacking & Gifting range includes dates, makhana, seeds and other wholesome food products. The company's healthy snacks category has recorded over 100 percent year-on-year growth.
The trend is also supported by NIQ's 2025 health and wellness research, which found that 49 percent of Indian consumers plan to buy more high-fibre foods, while 37 percent intend to add more plant-based proteins to their diets.
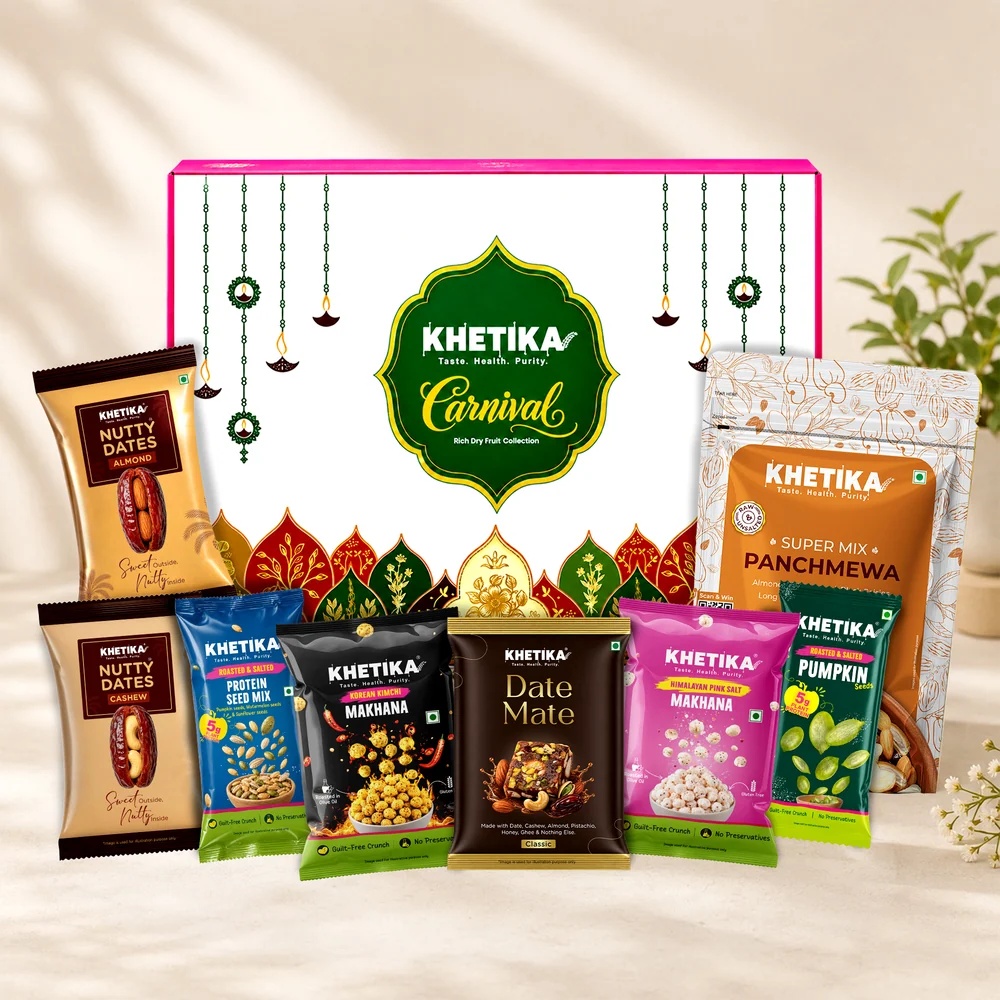 Singh said products priced above Rs 300 are witnessing strong demand. The company's Luxury Stuffed Dates Collection and Healthy Indulge Box have also seen a rise in demand. Its focus includes preservative-free and INS-free products, natural flavouring, and farmer-linked sourcing through SAATHI, supported by more than 380 quality checks and tests.
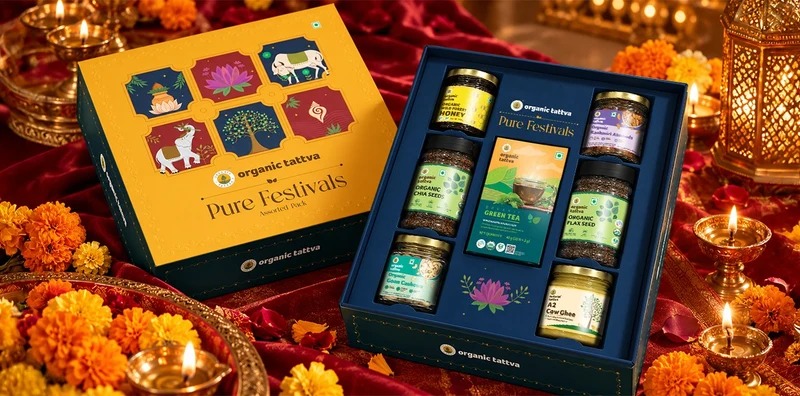
Kriti Mehrotra, Director, Organic Tattva, said, "Diwali gifting has shifted from sweets, namkeens, and sugary drinks to wellness-led hampers. People are gifting cleaner, healthier snacks, something that their families and friends would actually love to use at home."
Established in 2012 and headquartered in Greater Noida, Organic Tattva has launched two gift boxes at different price points. These include dry fruits, chia seeds, flax seeds, honey, ghee, and other organic products.
The company's average gifting order value ranges between Rs 700 and Rs 1,500. Dry fruits, honey, ghee and superfoods are among its popular gifting categories. However, Mehrotra said festive growth has remained stagnant for most FMCG companies this year. The brand is also offering festive deals across quick-commerce and e-commerce platforms.
Also read: How GRM Foods Is Growing 921 Basmati Rice Globally
Traditional Hampers Get a New Look
Traditional sweets and savoury snacks continue to be important during Diwali, but consumers are showing greater interest in curated hampers that bring different products together.
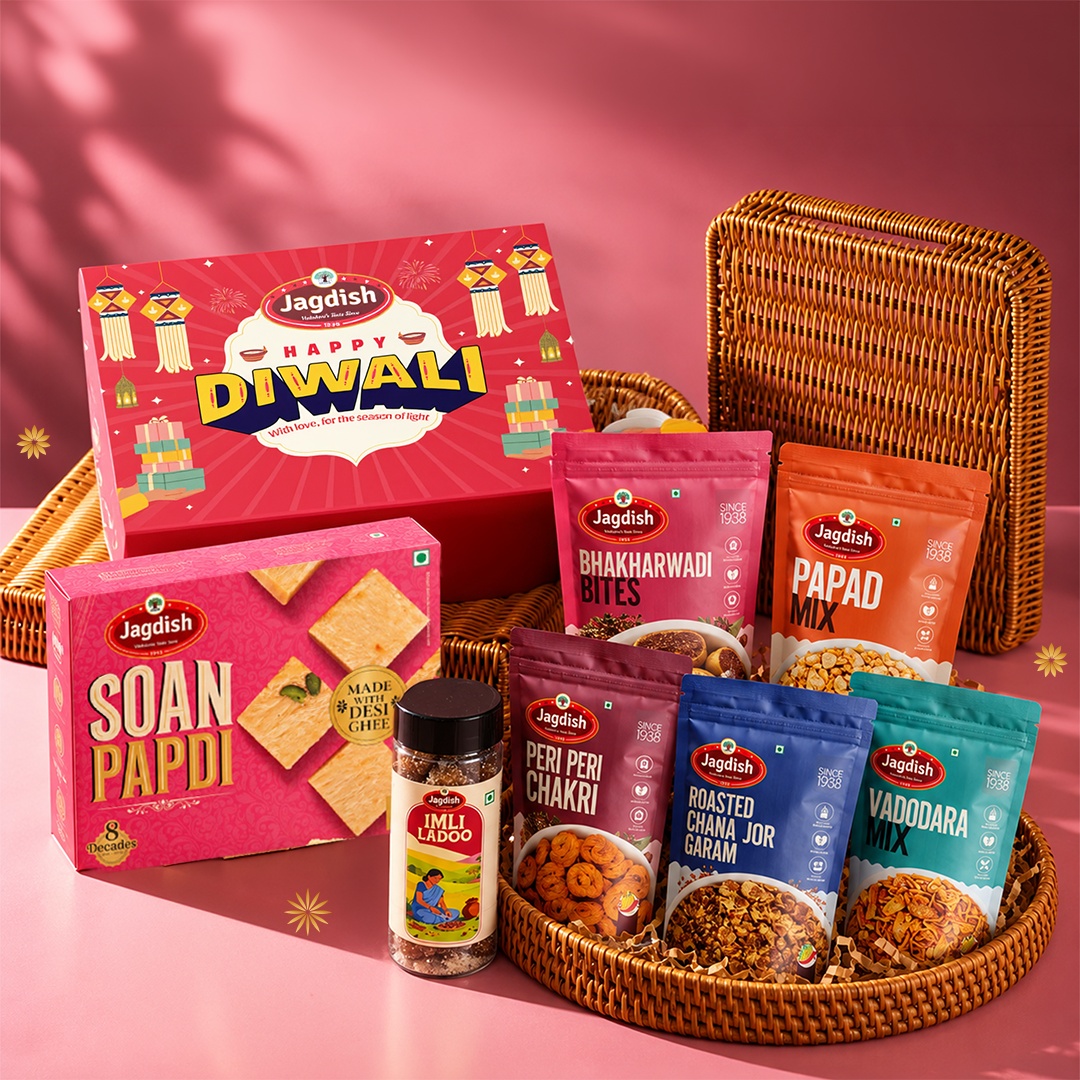
Aakash Kandoi, CEO and MD of Jagdish Farshan, said, "Diwali gifting this year is more considered than impulsive. Consumers are still spending, but they want each gift to carry meaning: heritage, quality and packaging that feels gift-ready."
Jagdish Farshan is recording 15 percent year-on-year growth in Diwali sales. Its popular gifting categories include festive hampers, mithai and namkeen. Starting at Rs 699, its hampers combine Gujarati farsan, traditional sweets and dry fruits.
The company's average order value ranges between Rs 1,100 and Rs 1,300, showing interest in larger gift assortments instead of individual boxes.
 Kandoi said, "Today's Diwali buyer is not choosing between tradition and modernity; they want both in the same box."
He added that customers are asking more questions about ingredients, oil quality, and sugar levels. As a result, dry-fruit sweets and baked or roasted namkeen are also finding demand.
Personalisation is another trend, with customers choosing their own assortments, adding messages and selecting festive packaging. Corporate buyers are also asking for branded hampers for employees and clients.
Jagdish Farshan expects to maintain at least 15 percent festive growth. The company sees opportunities in quick commerce, Tier II cities and demand from Indian consumers living in the US, UK and Canada.
Also read: From Premium Perfumes to Pocket-Friendly Scents
Home Fragrance Finds Space in Gifting
Apart from food products, home fragrance is emerging as another gifting option. Rising dry-fruit prices and the demand for affordable premium gifts are encouraging consumers and companies to explore alternatives.
Aarti Koya, CEO, EKAM, said, "Diwali 2026 is a volume year, not a ticket-size year."
According to Datum Intelligence, India's online festive season is expected to reach Rs 1.50-1.55 lakh crore in 2026, growing 25-29 percent over 2025.
Koya said EKAM is seeing more first-time buyers, repeat orders and demand for smaller gifts instead of one large hamper. The later Diwali date this year, November 8 compared with October 20 in 2025, has also pushed a larger share of purchases towards the final ten days.
Rising dry-fruit prices are another factor. According to figures cited by Koya from the Free Press Journal, pistachio and date prices have approximately doubled, while almond prices have increased around 35 percent year on year.
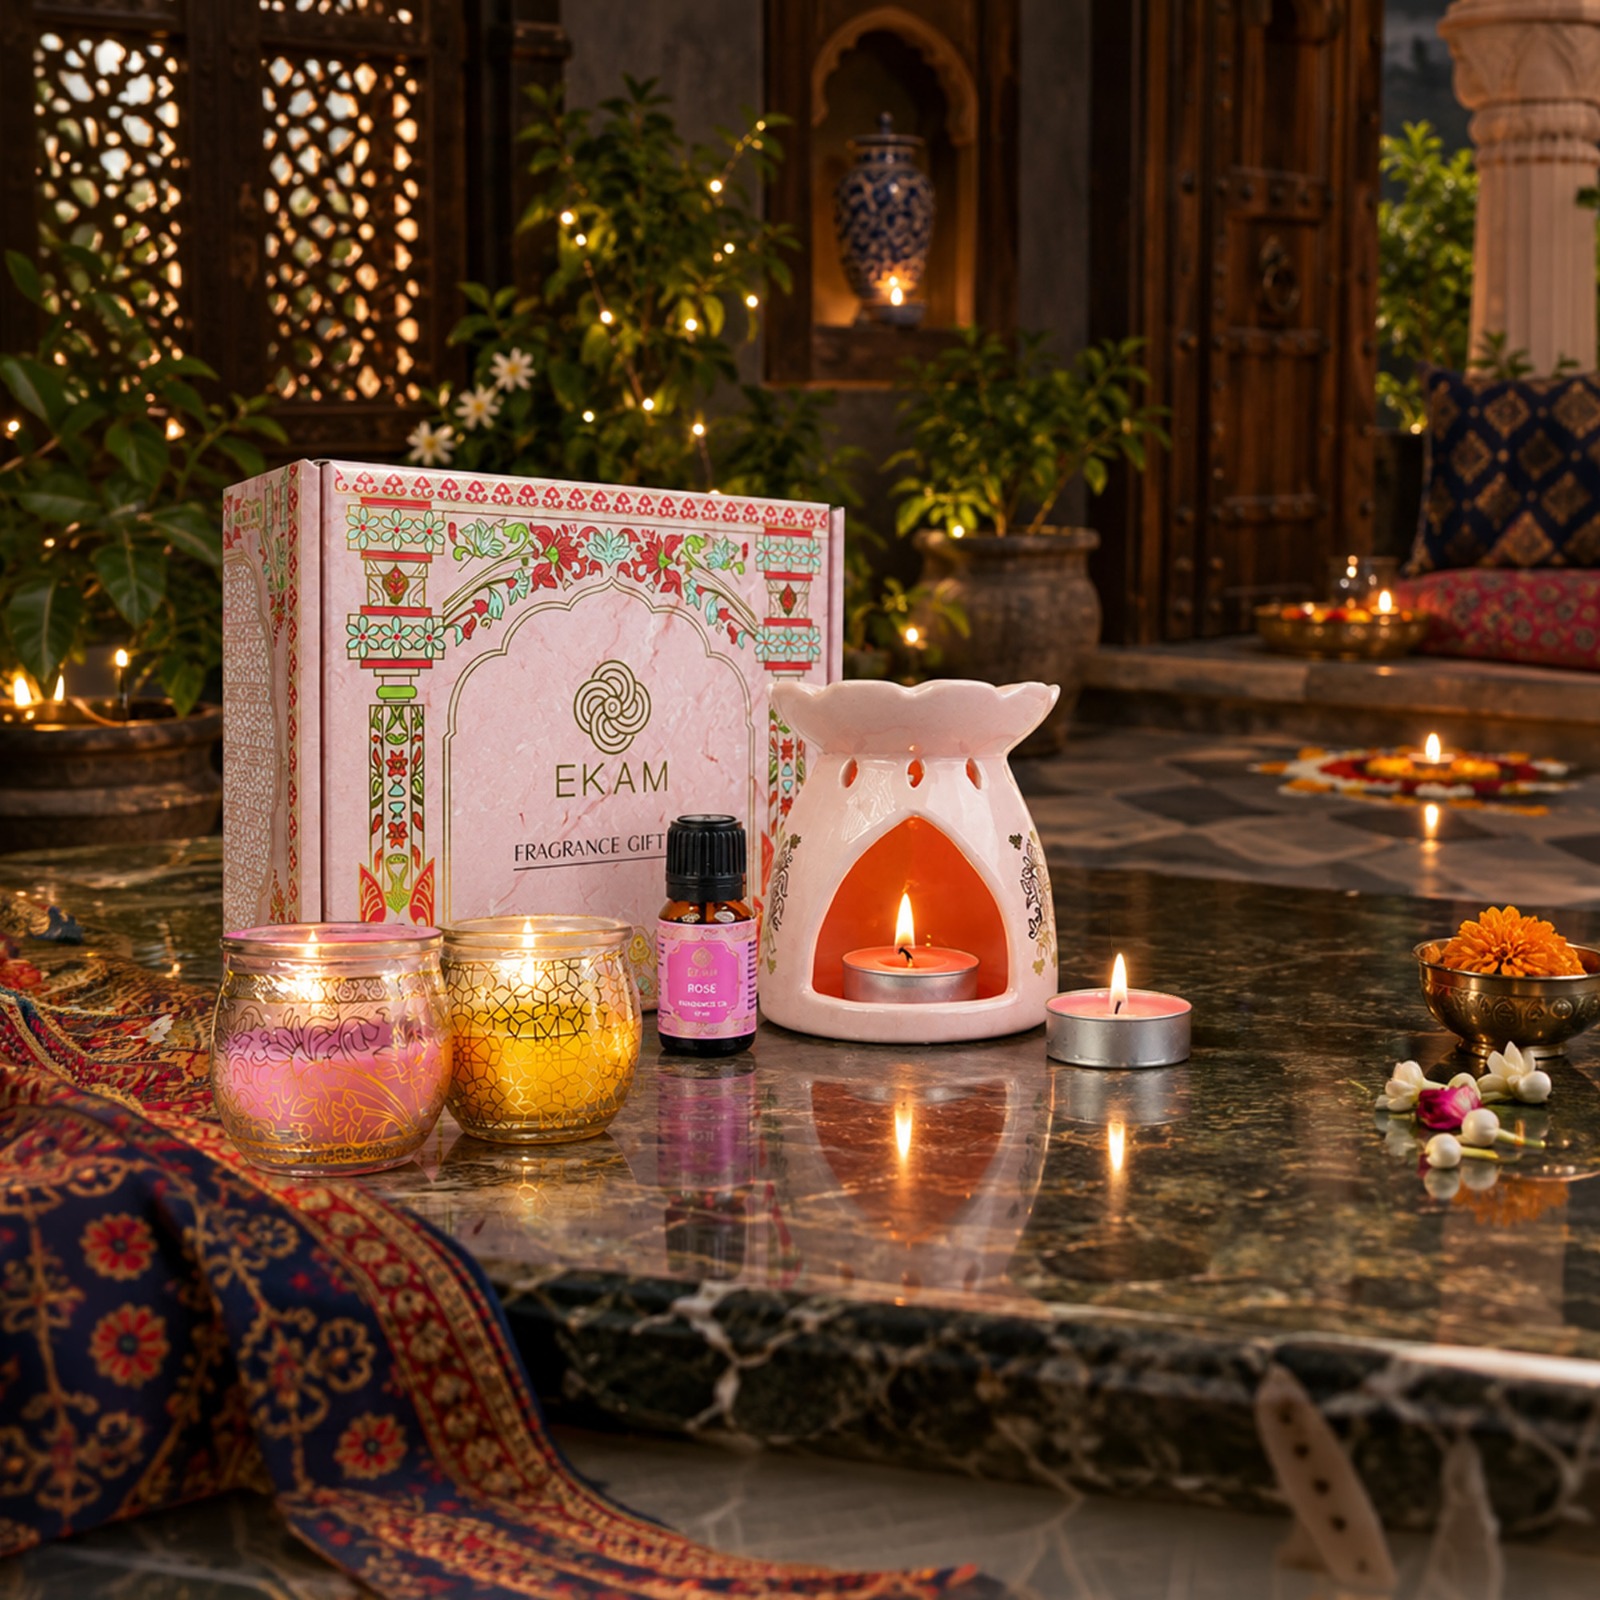 EKAM's Diwali-season sales are running 200 percent ahead of last year on a like-for-like basis. Festive candle gift packs, reed diffuser sets and corporate orders are driving demand.
The company has introduced 24 new gifting SKUs across three collections: Sheesh Mahal, Pink Haveli and Stone Palace. Its products are mainly priced between Rs 500 and Rs 1,000, while the Rs 1,000-2,500 segment is growing faster. Reed diffuser gift sets are popular in the Rs 500-750 range.
Founded in September 2020, EKAM is headquartered in Mangalore (Karnataka). Its average direct-to-consumer order value is around Rs 1,000, while corporate orders average Rs 1 lakh.
Koya said, "Premium means 'feels expensive', not 'is expensive'. Shoppers are comparing prices and prioritising value, and festive growth is coming from smaller, more frequent orders rather than bigger baskets."
The company has also expanded its presence across Amazon, Flipkart, Myntra, Blinkit, Swiggy Instamart and Zepto to reach last-minute shoppers.
Also read: Retail Sales Grow 8 Pc in September 2026 Ahead of Festive Season: Report
 Personalised Gifts Gain Demand
Consumers are also looking for gifts that are useful and match the interests of the person receiving them. This is creating opportunities for lifestyle and home products.
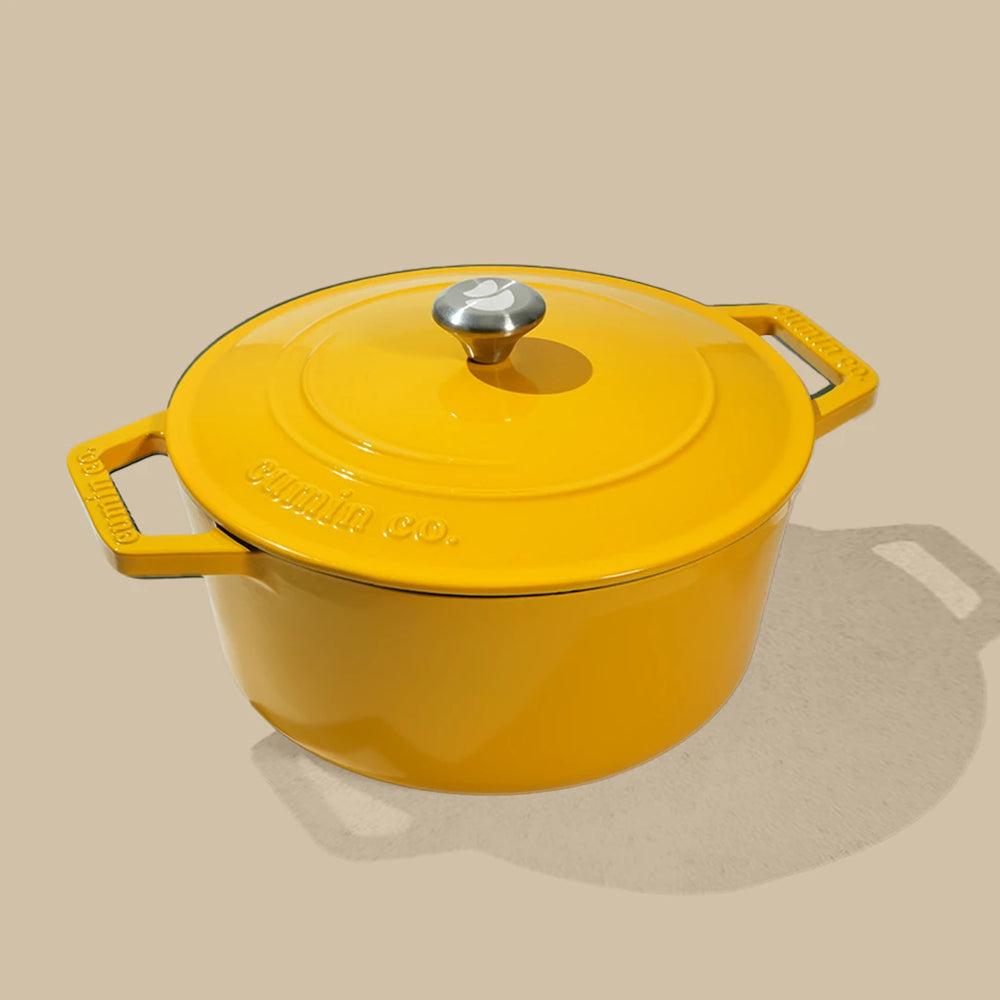
Niharik Joshi, Co-founder of Cumin Co., said, "One of the biggest shifts we've noticed is how deliberate and discerning consumers have become about gifting. People are no longer looking to simply pick up generic or random gift items."
The company has seen good demand for its Stash Boxes, which offer storage and everyday utility. It has also introduced a gifting concierge service to help customers select products, especially when buying gifts for several people.
Joshi said, "There is a growing preference for products that are unique yet useful, something that the recipient will genuinely enjoy and incorporate into their everyday lives."
She added that consumers are increasingly interested in products that combine design, quality, and functionality. The company has also received corporate gifting orders where buyers specifically asked for clean products.
According to Joshi, consumers may be purchasing fewer products but are willing to spend more on premium and well-designed gifts.
Also read: Premiumization Reshapes India’s Home Appliance Retail Market
 Corporate Gifting Expands
Corporate gifting is becoming an important part of the festive market, with companies looking for customised hampers, branded packaging and products suited to different budgets.
Brands are also extending their gifting collections beyond Diwali to weddings, housewarmings, employee milestones and other occasions.
Khetika is building its gifting range as a year-round offering, while Jagdish Farshan is focusing on customised food hampers. EKAM is offering co-branded packaging and bulk orders, and Cumin Co. is focusing on useful and design-led products.
Overall, India's Diwali gifting market is expanding beyond traditional sweets and dry fruits. Healthier food choices, personalised hampers, home fragrances and useful lifestyle products are becoming part of the festive shopping basket.
As consumers become more careful about what they buy and gift, brands are focusing on products that offer quality, good presentation and value.
A college student in Pune wants an iPhone with a genuinely good camera. A new one costs more than her monthly stipend can justify. A few years ago, her only real option would have been settling for a budget Android instead. Today, she has a third path that didn't really exist in any organised form a decade ago, a certified, warrantied, pre-owned iPhone at nearly half the price of new.
That shift, happening quietly across millions of similar decisions, is what's now being called India's upgrade economy, and the numbers behind it are hard to ignore. According to Counterpoint Research's Global Pre-Owned Smartphone Market Report for H1 2026, India's refurbished smartphone volumes grew 13 percent year on year in the first half of the year, even as sales of new smartphones actually fell by around 11 percent over the same period. That's not a small divergence. It suggests a genuine behavioural shift, not just budget conscious buyers settling for less, but buyers deliberately choosing better, older devices over newer, more expensive ones.
The same report found premium brands gaining ground specifically within the organised, certified segment of the refurbished market, a detail that matters more than it might seem. India's pre-owned electronics market has historically been dominated by unorganised sellers, roadside shops, informal resellers, classified listings with no real accountability if something goes wrong after the sale. Counterpoint's data puts the organised channel's share at roughly 20 percent of the total market, which sounds modest until you realise how much room that leaves for structured, trust-driven businesses to grow into.
This is really the crux of why the upgrade economy matters beyond just cheaper phones. Pre-owned technology has always existed in India. What's changing is the infrastructure around it, warranty coverage, quality certification, verification checks, and genuine after sales support, the same things that made buying new devices feel safe for decades.
A growing number of certified pre-owned platforms now illustrate this shift concretely. The stronger ones put every device through a documented, multi-point inspection covering hardware, software, battery health and cosmetic condition, alongside verification of activation lock status and device identity history, two checks that directly address the biggest fears buyers have historically had about used electronics, a stolen device, a hidden lock, a battery quietly dying within months. Many now offer up to twelve months of warranty, a short return window, and financing through EMI, features that used to be reserved almost exclusively for new device purchases. Trade-in and exchange programmes have also become common, letting customers put an older device toward a pre-owned upgrade, and some platforms operate physical stores in major cities, giving buyers somewhere to walk in and get support rather than relying purely on an online transaction with no recourse.
This model addresses something the broader market data hints at but doesn't fully explain on its own. Industry tracking through 2026 has repeatedly pointed to rising demand for higher-priced refurbished devices specifically, even as the cheapest segment of the refurbished market has been shrinking as a share of total sales. In other words, Indian buyers aren't gravitating toward pre-owned technology purely to save money at the bottom end. They're using resale and refurbishment markets to access premium technology they otherwise couldn't justify buying new, a phone with a great camera, a laptop capable of real creative work, a smartwatch with cellular connectivity.
That's a meaningfully different economy from the one refurbished electronics operated in a decade ago, when pre-owned essentially meant compromise. It's becoming a legitimate parallel path to ownership, one where the ceiling isn't "what can I afford new" but "what can I access certified and warrantied, at a price that makes sense."
What happens next likely depends on how much the organised segment of this market can grow relative to the unorganised one still handling roughly four out of every five refurbished transactions in the country. Trust, not price, is the actual bottleneck holding back faster adoption, and trust is built slowly, through certification standards, warranty follow through, and enough repeat customers willing to vouch for the experience.
For now, the trajectory looks fairly clear. As new device prices in India continue climbing, and certified pre-owned platforms continue building the infrastructure that makes pre-owned technology feel safe rather than risky, more buyers are likely to start their next upgrade not by asking which new phone to buy, but by asking which excellent, certified, pre-owned device they can now actually afford.
Authored By:
Manil Shetty is the Managing Director at Maple Digital Technology Intl. Pvt. Ltd.
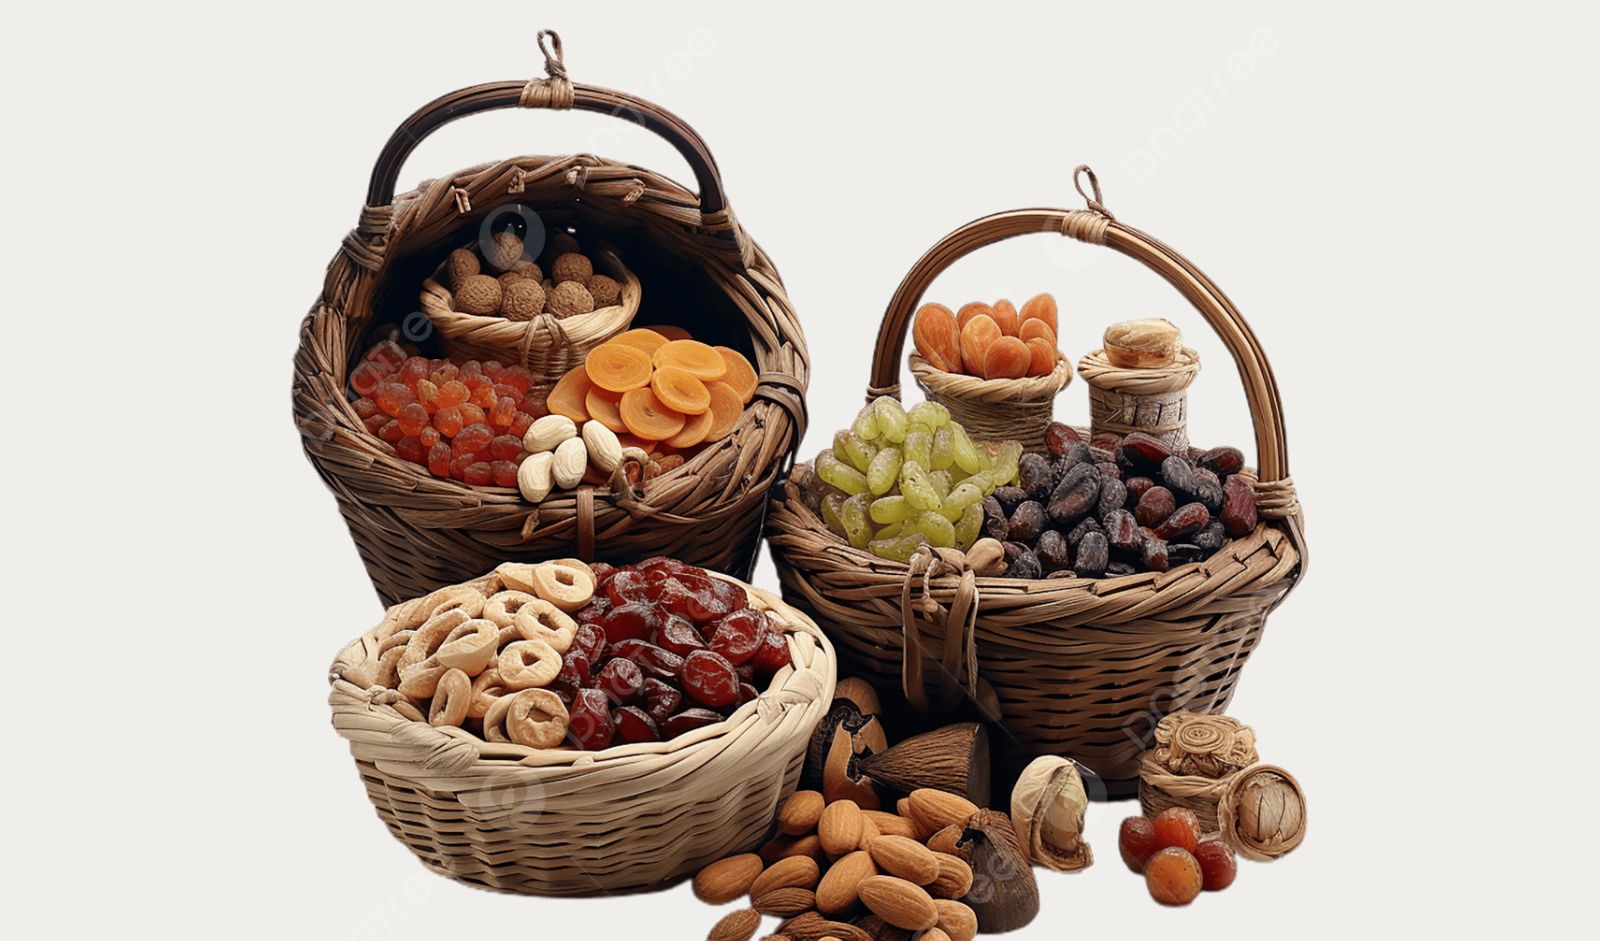
Every festive season, a box of nuts and dry fruits carries more than food. It is a gesture of respect, affection or appreciation. What goes inside that box is changing, though. Alongside familiar almonds, cashews, raisins and pistachios, buyers are discovering pecans, macadamias, hazelnuts, Brazil nuts, dates and berries. For retailers, that change says something important about what people now consider a thoughtful gift.
Health awareness is part of the appeal, but it would be a mistake to call this the end of traditional festive indulgence. Mithai retains its place in celebrations, and rightly so. Many families would rather offer a combination: a favourite sweet, a selection of nuts and perhaps something the recipient can enjoy over the following weeks. Gifting is becoming more personal, not less festive.
Nuts also have a practical advantage. They are familiar foods that can move from a celebration hamper into a breakfast bowl, office drawer or evening snack. Almonds, walnuts and pistachios provide nutrients including plant protein and unsaturated fats. The ICMR-National Institute of Nutrition includes modest portions of nuts and seeds in its guidance on balanced diets. That is a sounder message than suggesting an expensive assortment can, by itself, deliver better health. Portions, ingredients and the wider diet still matter.
Variety is changing the meaning of premium gifting as well. A larger box does not necessarily feel more special than a carefully chosen mix. Macadamias offer a different texture; pecans and hazelnuts bring flavours some recipients may know from desserts but rarely buy on their own. Traditional favourites provide reassurance, while a smaller quantity of unfamiliar nuts can make the gift memorable. The strongest assortments allow both to sit comfortably together.
This opens up a distinct opportunity for retailers and gifting businesses. Corporate buyers need dependable availability, consistent quality and presentation that suits different budgets. Individual shoppers may value smaller assortments with clearly identified varieties and practical packaging. A recipient should know what is inside the box, where appropriate how to store it, and whether a flavoured product contains added sugar or salt. Clear ingredient and allergen information deserves as much attention as an elegant sleeve.
Pricing is especially important this season. Imported nut categories remain exposed to freight costs, currency movements and shifts in overseas supply. Rather than treating premium as synonymous with expensive, retailers can offer combinations across price points, balancing familiar varieties with smaller portions of speciality nuts. That keeps discovery possible without making a gift inaccessible.
The longer-term prize is not merely a bigger festive sale. Someone who enjoys a new variety in a hamper may look for it again, this time in a small pack for home. Festivals can introduce a product; everyday usefulness can turn that introduction into lasting demand.
The traditional dry fruit box is not being replaced. It is finding new company. For India's nuts and dry fruits trade, the opportunity is to preserve the warmth of gifting while giving consumers more choice, better information and food they will actually enjoy after the celebrations end.
India’s furniture and home décor market is seeing a shift in consumer spending. During Diwali, homeowners are increasingly investing in furniture, furnishings and decorative products to refresh their living spaces. Buyers are looking beyond basic functionality and giving more importance to design, comfort, quality and durability.
The festive season has also brought higher sales for several brands. Consumers are showing interest in products that improve the appearance of their homes and remain useful throughout the year.
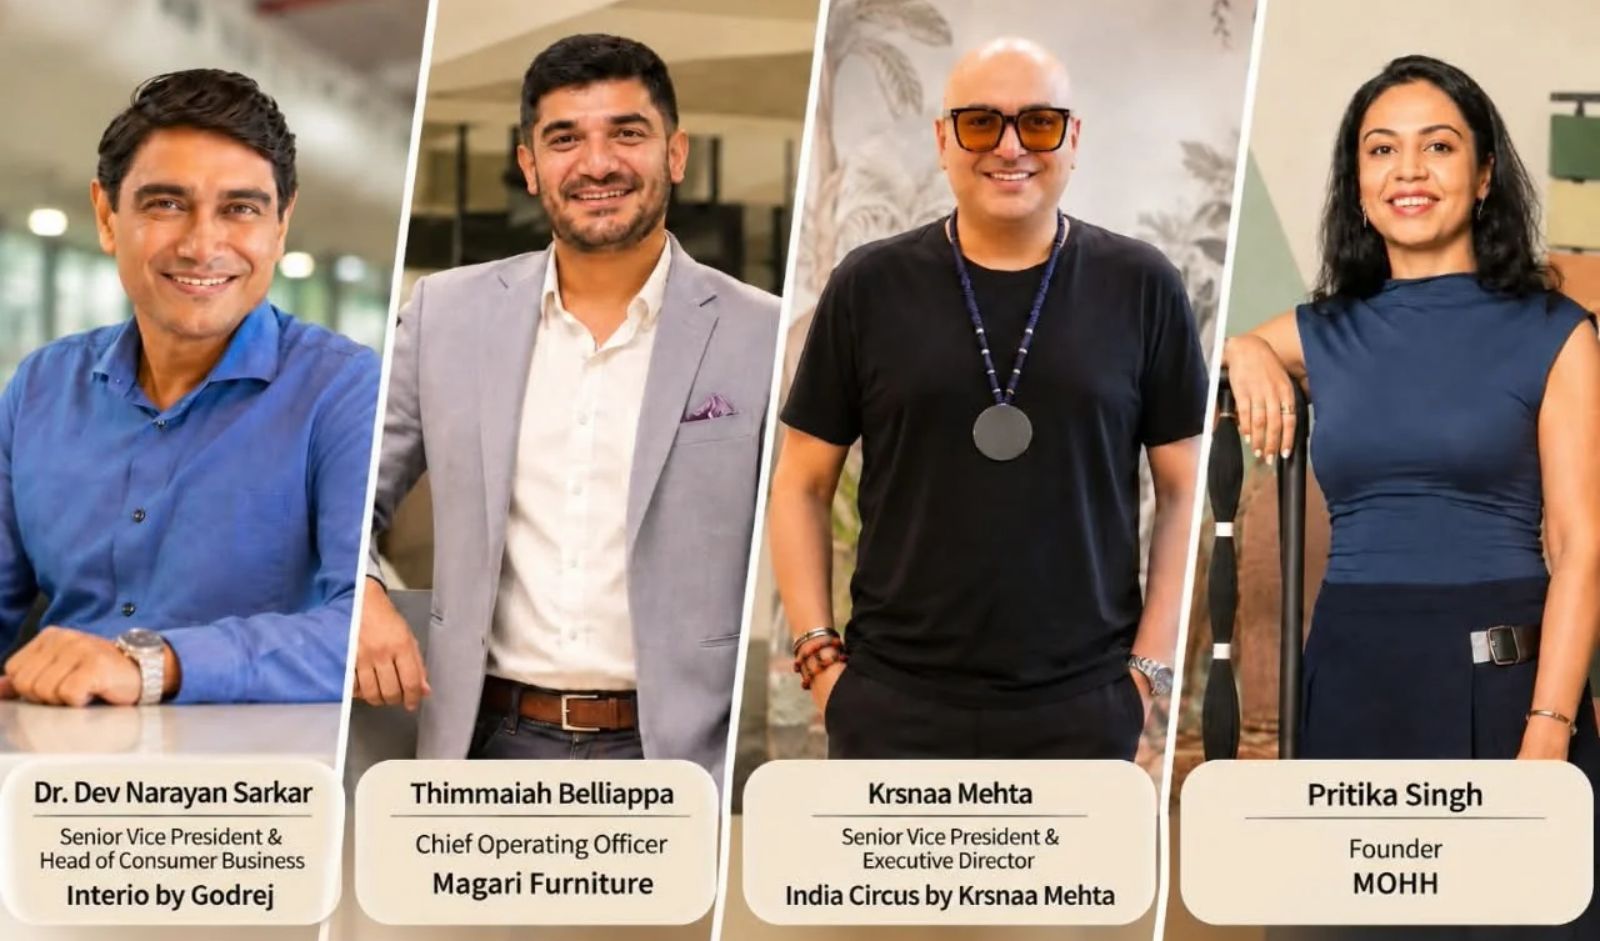
According to Pritika Singh, Founder of MOHH, festive sales were around 25 percent higher than an average month. The company recorded a 120 percent increase in order value and a 50 percent rise in order numbers compared with the previous year.
“The festive season is an important period for the furniture and home interiors industry, as consumers look to refresh their living spaces and invest in pieces that enhance both aesthetics and functionality,” Singh said.
At MOHH, home décor, bar units and living room seating, including sofas, lounge chairs and benches, were among the top-selling categories. The strongest demand came from the Rs 30,000-65,000 price range.
Also read: Malgudi: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Premium Products Gain Share
Consumers are becoming more selective about their home purchases. Design, craftsmanship, material quality and customisation are playing a bigger role in buying decisions.
Singh said MOHH recorded an approximately 30 percent year-on-year increase in premium and luxury furniture sales during Diwali 2026. Its festive sales were divided equally between smaller products, such as home décor, consoles, stools and shelves, and higher-value purchases, including sofas, beds and bar units.
“Consumers are becoming more thoughtful about where they spend on their homes. Rather than purchasing furniture purely for its functional value, there is greater consideration for design, craftsmanship, material quality and how well a piece fits into an individual's lifestyle,” she said.
A similar trend is visible at India Circus by Krsnaa Mehta, a Godrej brand. Krsnaa Mehta, Senior Vice President and Executive Director, India Circus by Krsnaa Mehta, said the brand recorded more than 100 percent year-on-year sales growth during Diwali 2026. Its festive revenue was around three times that of an average month.
Home décor and dining products were the major contributors. Dinnerware, serveware, decorative accessories, and furnishings also saw increased interest. Gifting remained another important category.
“The Diwali season is one of the most significant periods for India Circus, witnessing a strong uptick in consumer demand as customers look to refresh their homes, shop for festive essentials and explore gifting options,” Mehta said.
The brand reported a 30-40 percent change in average consumer spending compared with the previous year. Premium products accounted for around 75 percent of its festive demand. Gifting recorded the strongest growth, followed by the business-to-consumer segment.
Its average festive order value stood at around Rs 7,000. The brand reported 55 percent year-on-year growth, while the festive season contributed 30 percent of its annual sales.
Also read: How GRM Foods Is Growing 921 Basmati Rice Globally
Changing Furniture Preferences
Changing lifestyles and smaller urban homes are influencing furniture purchases. Consumers want products that offer more functionality without occupying too much space.
Dr. Dev Narayan Sarkar, Senior Vice President and Head of Consumer Business, Interio by Godrej, said consumers are moving from buying individual products to creating complete living spaces.
“Comfort, storage, durability and design are now expected to come together. A sofa or wardrobe must be functional, durable and suited to the way people live,” he said.
He added that living rooms are now used for work, entertainment, family time and hosting guests. This has increased demand for multifunctional furniture, integrated storage, warmer materials and textured finishes.
Interio's Upmods range offers more than 2,450 configurations. Customers can modify or upgrade their furniture as their requirements change.
At Magari Furniture, consumers are increasingly viewing furniture as a long-term investment rather than making purchases only for festive occasions.
“Design, quality, comfort and durability are playing a greater role in purchase decisions, particularly in the premium furniture segment,” said Thimmaiah Belliappa, Chief Operating Officer, Magari Furniture.
He added that customers are showing interest in natural materials, richer textures and distinctive designs. Sofas, lounge chairs, accent chairs and dining furniture are among the categories attracting buyers.
Also read: From Premium Perfumes to Pocket-Friendly Scents
Online and Offline Sales
Online platforms and physical stores both play an important role in furniture and home décor purchases.
At MOHH, online sales contributed 80 percent of total sales, while offline sales accounted for 20 percent. During the festive season, offline sales increased 70 percent year-on-year, compared with 20 percent growth online.
India Circus recorded 30 percent year-on-year growth in online sales and 50 percent growth in offline sales during the festive period. Offline retail contributed 60 percent of its total sales, while online accounted for 40 percent.
The brand is looking to expand through exclusive outlets, shop-in-shop formats and retail partnerships in FY27. It is also focusing on e-commerce, quick commerce, corporate gifting and international e-commerce.
Interio has expanded its e-commerce reach to more than 17,000 pin codes. It also has over 1,015 exclusive showrooms and more than 4,000 retail touchpoints.
The company holds a 15 percent share of India's organised furniture retail market and recorded 23 percent sales growth over the past year. During FY26, it expanded into 100 new cities. Sales from new product introductions contributed 22 percent of its overall business.
Its online sales contribution stands at 15 percent, while offline sales account for 85 percent. The company has also introduced 360-degree virtual walkthroughs, 3D room planners and AI-based product recommendations.
Magari Furniture operates stores in Bengaluru, Hyderabad, Chennai, Kochi and Indore. It is looking to expand into Mumbai, Delhi, Ahmedabad and Kolkata, along with select Tier II cities.
Also read: Retail Sales Grow 8 Pc in September 2026 Ahead of Festive Season: Report
Focus on Design and Personalisation
India's furniture market is increasingly moving towards products that offer better design, comfort and flexibility. According to industry estimates cited by Interio, the market is projected to reach USD 45.52 billion by 2031. Premium furniture is also expected to grow faster than the overall home furniture market, while the mid-range segment remains the largest.
Sarkar said modern Indian luxury is about comfort, quality and personalisation rather than expensive products alone.
“Luxury lies in the freedom to customise a layout, the comfort of good ergonomics, the feel of quality materials, the usefulness of integrated technology and the confidence that a product will last,” he said.
Founded in 1923 and headquartered in Mumbai, Interio offers home furniture and mattresses. Bedroom, living and dining furniture are its key categories. Its average price point is around Rs 50,000. The company has more than 1,000 stores and over 3,700 retailers.
India Circus was founded in 2013 and is headquartered in Mumbai. Its focus includes home décor, dining, wall décor, floor coverings, and hydration products. Its festive bestsellers include cushion covers, wall décor, dinner sets, tea sets, mugs, copper bottles and tumblers.
Founded in 2020 and headquartered in Delhi, MOHH recorded 10 percent revenue growth between FY25 and FY26. The company operates a 1,50,000 sq. ft. manufacturing facility in Gurugram.
As festive demand supports the furniture and home décor category, brands are focusing on changing consumer needs. Premium products, customised furniture, decorative accessories, and functional designs are gaining attention. These preferences are also shaping purchases beyond Diwali, as consumers look for products that suit their homes and everyday lifestyles.
Also read: Premiumization Reshapes India’s Home Appliance Retail Market
India’s alcoholic beverages market is witnessing a gradual shift towards premium products, with Diwali 2026 highlighting changing preferences across whisky, vodka and gin. Premium bottles, festive gifting, home entertaining and flavour experimentation are driving demand.
From Indian single malts to craft gin and flavoured vodka, domestic brands are gaining traction as consumers show greater interest in product origin, quality and craftsmanship. Festive celebrations and social gatherings continue to support sales across retail outlets, bars and restaurants, while metros lead premiumisation and smaller cities gradually follow suit.
Also read: Malgudi: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Premium Spirits Drive Festive Demand
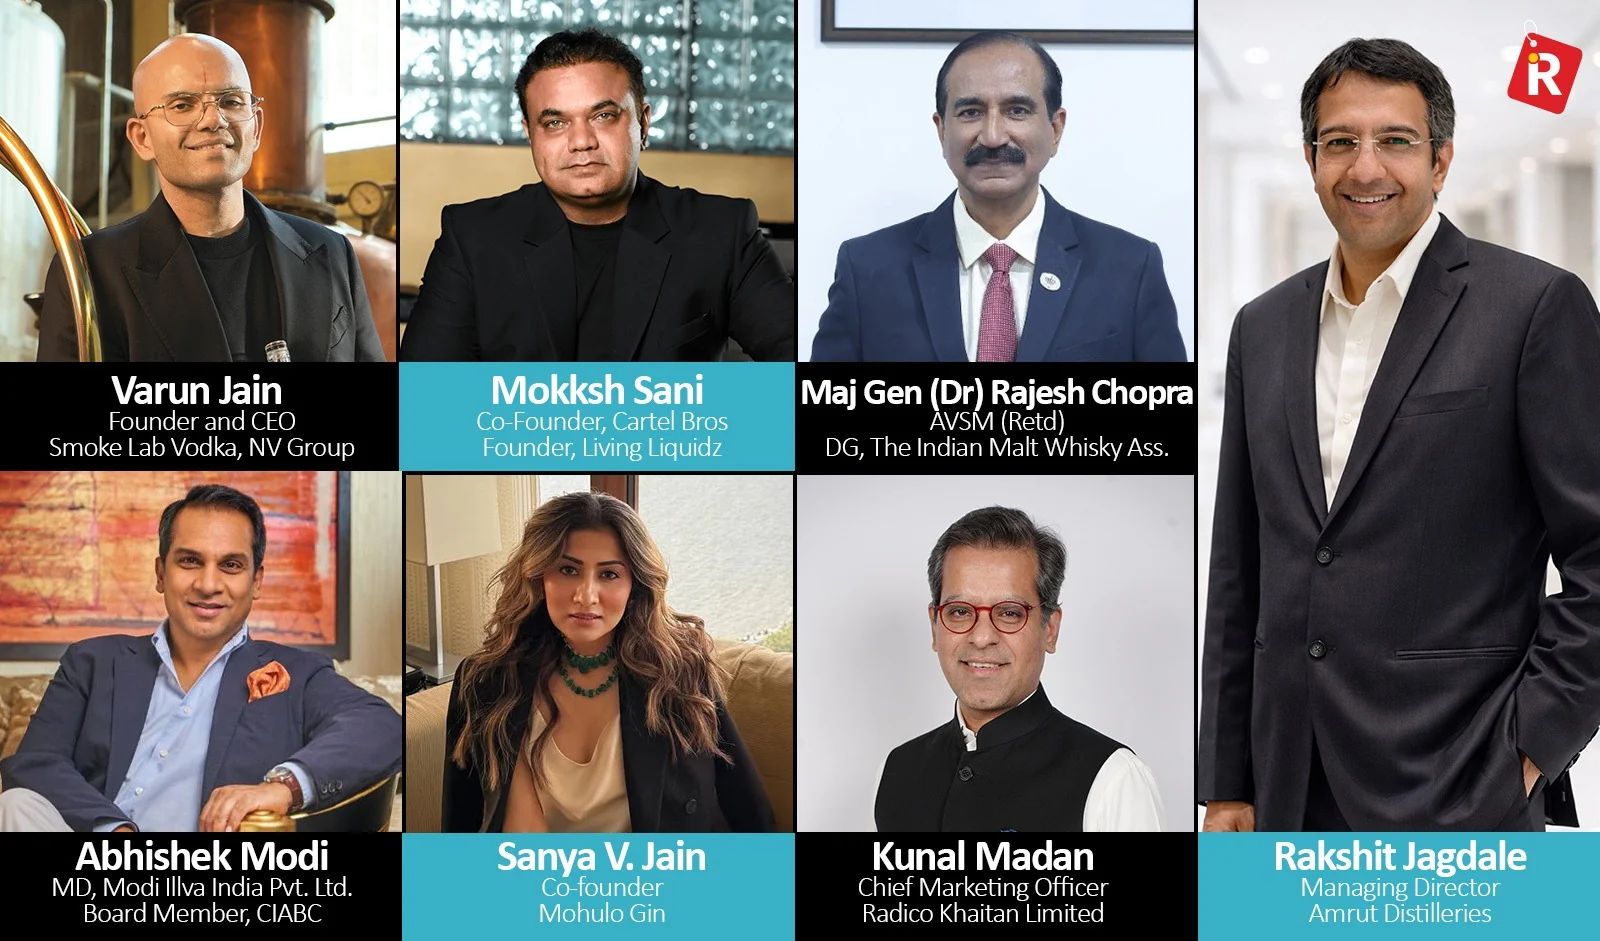
Kunal Madan, Chief Marketing Officer, Radico Khaitan Limited, said consumer preferences during the festive season reflect a combination of premiumisation and value consciousness.
“The festive mood is in the air, and it is reflecting in how consumers are choosing to celebrate. Premium continues to lead the way, with gifting and hosting driving demand, alongside growing interest in white spirits, particularly gin and flavoured vodka. At the same time, consumers remain value-conscious, making popular price points and smaller packs equally relevant,” he said.
According to Madan, metropolitan markets are leading the shift towards premium products and experimentation, while smaller markets are also catching up.
Radico Khaitan's premium portfolio registered 36 percent volume growth in Q2 FY27, reflecting the company's performance in the premium segment. The company is looking to strengthen its premium offerings, expand its presence across markets and improve its distribution network ahead of the festive and wedding seasons.
Also read: How GRM Foods Is Growing 921 Basmati Rice Globally
Indian Single Malts Gain Premium Traction
Indian single malt whiskies are strengthening their position in India’s premium spirits market, driven by rising consumer awareness, growing interest in homegrown brands and increasing appreciation for quality, craftsmanship and distinctive whisky-making techniques.
According to Maj Gen (Dr) Rajesh Chopra, AVSM (Retd), Director General, The Indian Malt Whisky Association (IMWA), the Indian single malt whisky category recorded 22 percent year-on-year growth between 2024 and 2026.
Rising incomes, wider retail access and growing interest in craftsmanship are driving Indian single malt demand, with Diwali boosting premium gifting and personal consumption opportunities.
Companies such as Amrut Distilleries, John Distilleries, Radico Khaitan, Piccadily Agro Industries, Diageo India and Alcobrew Distilleries India represent different participants in the broader Indian malt whisky landscape. Brands such as Amrut, Paul John, Rampur and Indri have contributed to increasing awareness of Indian whisky in domestic and international markets.
The Indian single malt whisky market is projected to grow at a compound annual growth rate (CAGR) of 12.6 percent between 2024 and 2032, according to the market estimate cited in the industry inputs.
Also read: From Premium Perfumes to Pocket-Friendly Scents
Homegrown Brands Gain Premium Appeal
Indian consumers are increasingly exploring homegrown premium spirits, with quality, distinctive flavours and product differentiation shaping purchase decisions across categories beyond whisky.
Abhishek Modi, Managing Director, Modi Illva India Pvt. Ltd. and Board Member, CIABC, said the Indian spirits market is undergoing a significant change in consumer expectations.
“India’s spirits market is at an important inflection point, with premiumisation increasingly shaping consumer preferences across categories. What is changing is not just how much consumers are willing to spend, but what they expect from the product. Quality, character, craftsmanship and a clear point of differentiation are becoming more important in the purchase decision,” he said.
He added that Indian consumers are increasingly willing to consider homegrown premium spirits instead of automatically choosing imported labels.
The company's Rockford portfolio includes Rockford Classic, Rockford Reserve and Rockford Imperial Reserve. Its premium offering, Rockford Imperial Reserve, was developed to provide existing consumers with a higher-end expression within a familiar brand.
Modi also pointed to growing interest in flavoured vodka, indicating consumers' willingness to experiment with different tastes and drinking experiences.
For the company, Rockford has recorded a 73.5 percent CAGR, while its overall business has reported a CAGR of more than 52.5 percent since inception. Founded in 2008 and incorporated in 2009, Modi Illva India reported gross sales of Rs 1,328 crore in FY26. The company has a presence across 22–23 states and is targeting gross sales of Rs 1,611 crore and sales of four million cases in FY27.
Also read: Retail Sales Grow 8 Pc in September 2026 Ahead of Festive Season: Report
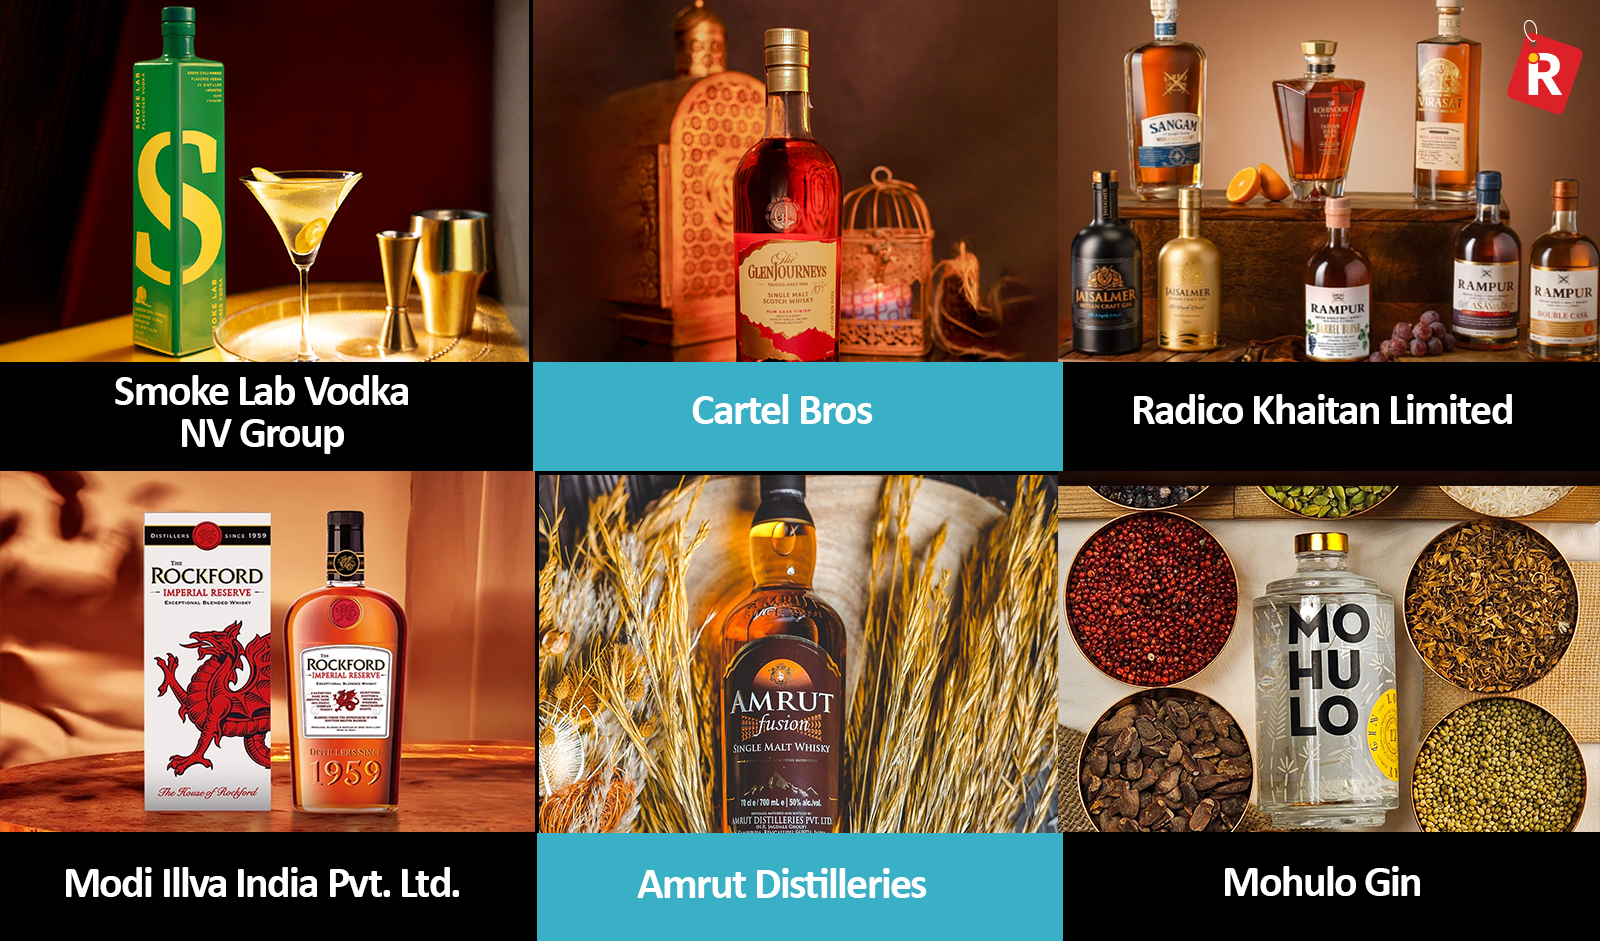 Amrut Sees Festive Demand Growth
Amrut Distilleries is witnessing festive interest across single malt whisky, premium rum and gin. Managing Director Rakshit Jagdale said the company typically records around 20 percent year-on-year festive growth, supported by limited-edition releases.
He said consumers are willing to spend approximately 20–25 percent more on a bottle of alcohol during the festive period compared with their regular spending. Gifting, personal consumption and increased socialising are among the factors supporting this trend.
“During the festive season, consumers typically show a willingness to spend around 20–25 percent more than they would usually spend on a bottle of alcohol. This trend is largely driven by three factors: gifting, personal consumption and increased socialising,” Jagdale said.
The company expects retail purchases to contribute significantly to festive sales, supported by house parties and at-home celebrations. While bars and restaurants remain important sales channels, home consumption is also driving demand.
Amrut Distilleries, founded in 1948 and headquartered in Bengaluru, reported FY26 net revenue of approximately Rs. 600 crore and gross revenue of Rs. 1,800 crore. Its portfolio includes single malts such as Amrut, Fusion and Amalgam.
For FY27, the company is targeting approximately 10–12 percent growth over the previous year's closing net sales. It is also looking to enter a couple of new states, subject to state excise regulations and distribution opportunities. Its average selling price is approximately Rs 3,500–4,000.
The company estimates that the festive season contributes around 30–35 percent of its annual sales, while its premium segment has recorded more modest growth of approximately 5–7 percent.
Also read: Premiumization Reshapes India’s Home Appliance Retail Market
Flavoured Vodka and Craft Gin Find New Consumers
Beyond whisky, vodka and gin are gaining attention as consumers explore different flavours and products. The interest is particularly visible among younger consumers in metropolitan and Tier I markets.
Smoke Lab Vodka, founded in 2019 by Varun Jain, Founder and CEO, Smoke Lab Vodka, NV Group, is positioning itself in the premium vodka segment through products that use Indian ingredients.
The brand's portfolio includes Classic, Aniseed, Saffron and Liquid Gold, alongside its Green Chilli Mango expression. Its vodka is made using premium Basmati rice, while the flavoured variants bring Indian ingredients into a category traditionally associated with conventional flavour profiles.
Jain said Diwali provides an opportunity for consumers to explore products that offer different experiences.
“When we founded Smoke Lab in 2019, our ambition was to challenge conventional perceptions of vodka by placing Indian ingredients at the heart of the experience,” he said.
The brand is seeing growing interest among Gen Z and millennial consumers in metropolitan and Tier I cities. Its Green Chilli Mango variant combines mango's sweetness with the heat of green chilli.
Smoke Lab's average selling price ranges between Rs 1,600 and Rs 2,000, with Rs 1,600 being its leading price point. The brand has a presence in more than 30 markets, including India, the US, the UAE and the UK.
The US is its largest international market. The company is looking to strengthen its presence there while expanding into the UK, Europe and Africa. It has also set an ambition to capture at least 30 percent of India's premium vodka segment by 2027.
According to the company's inputs, flavoured variants account for approximately 40 percent of its domestic sales, while Classic Vodka contributes around 85 percent of its international volumes.
Also read: Small Feet, Big Business: Kids’ Footwear Steps Up Growth
Indian Ingredients Give Craft Spirits a Distinct Identity
The growing interest in product differentiation is also creating opportunities for craft spirits built around indigenous ingredients.
Mohulo Gin, Co-founded by Sanya V. Jain, is developing its positioning around Mahua, a flower associated with the cultural traditions of communities across central India.
Founded in 2023 and headquartered in New Delhi, Mohulo is positioned as a premium craft sipping gin. It is produced in small batches using copper pot distillation and combines Mahua with a blend of 12 botanicals.
At 42.8 percent alcohol by volume (ABV), the gin is designed to be consumed neat or over ice. The brand is attempting to bring an indigenous ingredient into a contemporary premium spirits category.
Jain said premiumisation is increasingly about product character and differentiation rather than simply moving to a higher price point.
“Premiumisation is no longer just about moving to a higher price point. It is about giving consumers a compelling reason to choose one spirit over another,” she said.
She added that gifting preferences are creating opportunities for brands with a distinctive product story, provenance and craftsmanship.
For Mohulo, the focus is on expanding retail availability, building relationships with premium bars and restaurants and encouraging consumers to experience the product as a sipping gin.
The company is targeting wider distribution across key markets in FY27. However, its FY26 revenue, average selling price, Diwali sales growth and festive sales contribution have not been disclosed in the inputs.
New Entrants Expand the Luxury Single Malt Segment
The premium whisky market is also attracting newer brands looking to tap into consumer interest in aged and differentiated expressions.
The GlenJourneys, a brand from Cartel Bros, entered the Indian retail market in October 2025 with its Cask Series. Its portfolio includes bourbon, sherry, and rum cask-finished expressions, along with the 21-year-old Pioneer Edition.
Mokksh Sani, Co-Founder of Cartel Bros and Founder of Living Liquidz, has identified premium single malts as an opportunity within India's evolving luxury spirits market.
The Cask Series was introduced in Maharashtra at a reported launch price of Rs 6,409, while the Pioneer Edition was priced at Rs 50,000 at launch.
The brand reported cumulative turnover of Rs 30 crore by February 2026. It had also established distribution across nine states and entered international airport duty-free channels, with export orders to Dubai.
According to the company-provided information, The GlenJourneys recorded 50 percent year-on-year Diwali sales growth in 2026. October, November and December together contribute approximately 40 percent of the company's annual sales.
The brand had previously set an ambition to capture 10 percent of India's luxury single malt segment within two years. Its updated FY27 revenue and expansion targets are yet to be confirmed.
Export Opportunities Add to Industry Growth
Alongside domestic consumption, international markets are becoming an important opportunity for Indian alcoholic beverage producers.
According to the Agricultural and Processed Food Products Export Development Authority (APEDA), India's alcoholic beverage exports reached USD 364.68 million in FY26, covering 225,704.90 metric tonnes of alcoholic products. The UAE, the Netherlands, Ghana, Kenya and Singapore were among the major export destinations.
The government has also been promoting Indian alcoholic beverages under the Make in India initiative. APEDA had announced an export revenue target of USD 1 billion for the broader alcoholic and non-alcoholic beverage segment over the next few years.
For Indian single malt producers, international expansion is supported by growing recognition of Indian whisky-making, distinct maturation conditions and the use of locally sourced ingredients.
The category's growth is also reflected in its sales volumes. According to industry data reported by Business Standard, Indian single malt sales reached approximately 500,000 nine-litre cases in 2025, registering around 22 percent growth. Indian companies accounted for an estimated 92 percent of the category's sales.
Outlook: Premiumisation to Shape the Next Phase
The Indian alco-bev market is entering a phase in which product differentiation, premium offerings and consumer experience are becoming increasingly important. Whisky continues to be a significant category, while vodka and gin are gaining attention through new flavours, indigenous ingredients and craft-led positioning.
For established companies, the focus remains on expanding distribution, strengthening premium portfolios and increasing market penetration. For newer brands, building consumer awareness, establishing retail presence and developing a distinct product identity are central to their growth plans.
The festive season has reinforced these trends, with gifting, socialising and home entertaining supporting demand for premium spirits. However, the market continues to have multiple price segments, with smaller packs and accessible offerings remaining relevant.
As Indian producers expand their domestic and international presence, the industry's next phase of growth will depend on sustaining consumer demand, maintaining product quality and building stronger distribution networks.
-
For now, the trajectory looks fairly clear. As new device prices in India continue climbing, and certified pre-owned platforms continue building the infrastructure that makes pre-owned technology feel safe rather than risky, more buyers are likely to star
 Atomberg's R&D expenditure more than doubled from Rs 39.59 crore in FY24 to Rs 86.79 crore in FY26, reflecting its focus on developing proprietary technologies. Its R&D workforce also increased from 123 employees in March 2024 to 254 in March 2026, accoun
 In partnership with Invision Brands and Franchise India Group, blenz targets 40 outlets across India with a proposed investment of over INR 20 crore by 2027.
 The store features collections spanning handloom saris, bridal couture, occasionwear and menswear. Its assortment includes traditional weaving techniques such as Banarasi Kadhwa, Jamdani, Kanjivaram, Patan Patola, Ikat, Sambalpuri Ikat and Bandhani, along


Copyright © 2009 - 2026 Franchiseindia.com Ltd