


Managing Editor, IndianRetailer.com & Retailer Media Jan 25, 2024 /
 222
/ 7 MIN READ


In a world where the glint of jewelry often conceals a tale of environmental toll, Aulerth emerges as a radiant anomaly, a beacon of ethical elegance illuminating the jewelry landscape. As the brainchild of visionary Founder & CEO, Vivek Ramabhadran, Aulerth is not just a brand; it's a narrative of conscious luxury meticulously etched in every piece it unveils. Another glimmering fact that adds an additional facet to Aulerth's illustrious story is that they secured a formidable $1.1 million in seed funding from an illustrious league of investors. Among these visionary backers are M Venture Partners, the design luminary Tarun Tahiliani, Taro Nordheider, the former CEO of Swarovski Professional, the LV angel fund, and a network of McKinsey partners.
Vivek, the maestro orchestrating Aulerth's ascent, envisioned a paradigm shift in the world of precious adornments. His vision extended beyond the traditional allure of gold and diamonds, seeking a new definition of preciousness entwined with design finesse, meticulous craftsmanship, and an unwavering commitment to environmental sustainability. Aulerth is not merely a jewelry brand; it's a narrative that narrates the tale of jewels with a conscience. Ramabhadran, with a glint in his eye, expresses the brand's ethos, "We're steering away from the traditional definition of precious, tied to materials like gold and diamonds. These materials are not just expensive; they're environmentally destructive. Aulerth is about making people see preciousness in beautiful design, meticulous craftsmanship, and a conscious ideology—a shift away from the conventional. Every product that we will create is intentionally engineered to have an extremely low footprint. It will be circular in nature so that its usage is the highest."

Couture for the Neck
What sets this jewelry couture brand apart is its strategic collaborations with some of India's design royalty, including Shivan & Narresh, Suneet Varma, Ekaya Banaras, Tribe Amrapali and JJV by JJ Valaya. These partnerships transcend the transient nature of conventional collaborations, envisioning a long-term synergy to redefine the landscape of ethical jewelry. Ramabhadran envisions Aulerth as a creative platform, fusing technical expertise with designers' creative genius.
“A good designer partner is someone who first and foremost brings a distinctive design signature on which we can then build. Give it a more defined form and shape and manifest that into beautiful jewelry. Therefore, we procured top designers who don't craft their own jewelry. We then became their creative arm who transformed their signature embroidered motives into glorious jeweled pieces,” he explained.
Digital-to-Physical Brilliance
Aulerth initially embraced a digital-first approach, but its vision transcends screens. Recognizing the importance of an omnichannel presence, the brand is expanding into physical spaces with its fourth standalone store recently launched in Hyderabad. Ramabhadran shares, "Apart from our own stores in Delhi, Gurgaon, Bengaluru, we are present in the Taj Hotels. We are also exploring international avenues." Interestingly, the designers, who are afflicted with the brand, also stick their collection at their showrooms, apart from top multi-brand luxury retailers such as Ogaan, Evoluzione, Agashe, Bombaim, Amethyst, Ensemble, Aza Fashions, among many others.
The allure of Aulerth lies in more than just its semi-precious nature. Ramabhadran outlines the unique value proposition—finest quality, lifetime warranty, and a 'wear and return' option. "Customers see the value in our commitment to quality and sustainability. It's not just about the jewelry; it's about a lasting relationship with the brand," he explains.

Bespoke Culture
Acknowledging the growing desire for personalization, Aulerth offers customization options. "We are their personal jeweler. Customers can bring in their specific touches, ensuring their jewelry is a true expression of self," Ramabhadran states. “We do two types of customization – first, modular customizations such as different colored stone or flight engineering on the existing design itself. Second, holistic revamp, where we go back to the sketching stage and create something new.”
Addressing the question of pricing, Ramabhadran clarifies that Aulerth is not just for the elite. With a range starting at Rs 3,500, it ensures accessibility. He says, "Our pricing model is diverse, ensuring there's something for everyone. We are not just catering to a niche; we're democratizing elegance."
Circular Journey
Aulerth's commitment goes beyond aesthetics—it's about environmental consciousness. The brand offers a unique Loop option, encouraging customers to return jewelry after use. "Our commitment to circular products ensures that we are not just creating beauty but contributing to a sustainable future," Ramabhadran asserts. Concluding our conversation, he encapsulates Aulerth's vision, "We are redefining the narrative of preciousness. It's about caring for the environment, embracing conscious choices, and celebrating the enduring beauty of craftsmanship. Aulerth is not just jewelry; it's a statement of elegance and responsibility."


India’s festive retail market is heading into another year of strong growth, but the nature of that growth is changing. Consumers are expected to shop more frequently, spread their spending across a wider range of categories and make smaller purchases rather than concentrate their budgets on a few big-ticket products. As quick commerce expands its reach and everyday essentials take a larger share of festive spending, the season is increasingly becoming a story of changing consumption habits.
According to Datum Intelligence’s Festive Barometer Study 2026, the festive market is estimated to reach Rs 1.50–1.55 lakh crore ($17–17.6 billion) in 2026, registering growth of 25–29% over the Rs 1.20 lakh crore recorded in 2025. The market has expanded consistently since 2014, with the exception of a three-year period of slower growth. In 2025, festive sales rebounded by 25%, setting the stage for another strong season.
However, the 2026 outlook points to a more distributed pattern of consumption. Around 20 million additional shoppers are expected to participate in the festive market, while purchase frequency is also likely to increase. At the same time, the average basket value is projected to decline by 1.5%, suggesting that consumers are dividing their budgets across more transactions.
More Shoppers, More Frequent Purchases
The expected increase in shopper participation reflects improving consumer sentiment and a wider appetite for discretionary spending. Urban non-essential spending sentiment registered a net score of 3.3 in July, more than twice the previous peak recorded across 22 rounds of tracking.
Household spending intentions also indicate a positive festive outlook. Around 72% of households plan to spend more during the season, while 48% expect their spending to increase by more than 10%. The median planned festive expenditure stands at Rs 12,500.
Yet, stronger spending intentions do not necessarily translate into larger individual purchases. With more shoppers entering the market and buying more frequently, retailers are likely to see demand distributed across multiple transactions and categories.
This shift also reflects consumers' growing preference for managing their budgets carefully. Affordable instalment options have gained importance, with 51% of consumers citing them as a reason to make purchases, an increase of seven percentage points. This was the largest rise among the purchase motivations tracked.
The trend suggests that consumers remain willing to spend during the festive season but are increasingly conscious of affordability and payment flexibility.
Quick Commerce Moves Into the Festive Basket
One of the most significant changes in the 2026 festive outlook is the growing role of quick commerce. The channel is expected to account for 16% of festive-season spending, compared with 12% in the previous year.
Its expanding contribution indicates that festive shopping is no longer limited to planned purchases of apparel, electronics, home products and gifts. Consumers are also using digital platforms to meet everyday requirements, replenish household essentials and make smaller, more immediate purchases.
The category outlook reinforces this shift. Grocery spending is projected to grow by 41%, making it one of the strongest-performing segments during the season. Mobile sales, in comparison, are expected to grow by 6%.
The difference in growth rates points to a gradual change in the composition of festive consumption. Smartphones and other high-value electronics continue to remain part of the shopping season, but everyday categories are gaining greater traction. The change is not necessarily a contraction in mobile demand; rather, groceries and other essentials are expanding at a faster pace and taking a larger share of the overall spending mix.
For retailers, this means festive demand is increasingly being generated through both planned purchases and frequent replenishment orders. Quick-commerce platforms are positioned to benefit from this behaviour, particularly as consumers become accustomed to ordering across categories throughout the day.
Logistics and Hiring Prepare for Higher Demand
The expected rise in purchase frequency also places greater importance on fulfilment networks and last-mile delivery. Logistics companies have reported significant parcel-volume growth in the lead-up to the festive season.
Delhivery handled 322 million parcels in the June quarter, registering 55% growth, including volumes from Ecom Express. Shadowfax processed 198 million parcels during the same period, up 94%.
While these figures reflect quarterly logistics activity rather than festive-season volumes, they indicate the scale of fulfilment capacity being deployed as e-commerce demand expands. A market characterised by more shoppers and smaller, more frequent orders will require retailers and delivery partners to manage higher transaction volumes, efficient sorting and faster fulfilment.
Seasonal employment is also expected to rise by 16–25%, reflecting the additional manpower required across warehousing, logistics, retail operations and customer-facing roles.
The combination of higher parcel volumes and seasonal hiring points to the operational demands of a festive market that is expanding beyond traditional large-ticket shopping.
A Different Shape to India's Festive Retail Market
The 2026 festive season is shaping up to be more than another year of higher sales. It signals a change in how consumers distribute their spending and how retailers capture demand.
The expected addition of 20 million shoppers, increased purchase frequency and a 1.5% decline in average basket size indicate that growth is increasingly being driven by the number of transactions rather than simply the value of individual purchases.
At the same time, quick commerce is moving closer to the centre of festive consumption, while grocery and everyday essentials are gaining ground alongside traditional festive categories. Mobile purchases are still expected to grow, but at a slower pace than grocery, reflecting a broader retail mix.
India’s digital retail landscape continues to evolve, with consumer-facing businesses attracting investments across categories such as beauty, wellness, quick commerce, and local services. However, the pace of funding has slowed in 2026 as investors become more selective about where they deploy capital. While established businesses face greater scrutiny over valuations and profitability, early-stage companies continue to find opportunities, indicating that investor interest in the sector remains intact despite a cautious funding environment.
According to the India B2C E-Commerce Report released by Tracxn Technologies on November 5, 2026, companies in the sector raised USD 1.6 billion between January 1 and November 3, 2026, across 356 funding rounds. This represents a 33 percent decline compared with the USD 2.4 billion raised through 621 rounds in 2025.
The report tracks funding activity, investors, exits, unicorn creation, and city-level developments across India's business-to-consumer (B2C) e-commerce ecosystem.
Also read: How Jaipur Rugs Is Expanding Its Global Footprint
Investors Become More Selective
The decline in funding reflects a shift in investment priorities, with investors increasingly focusing on business fundamentals, sustainable growth, and clear routes to profitability.
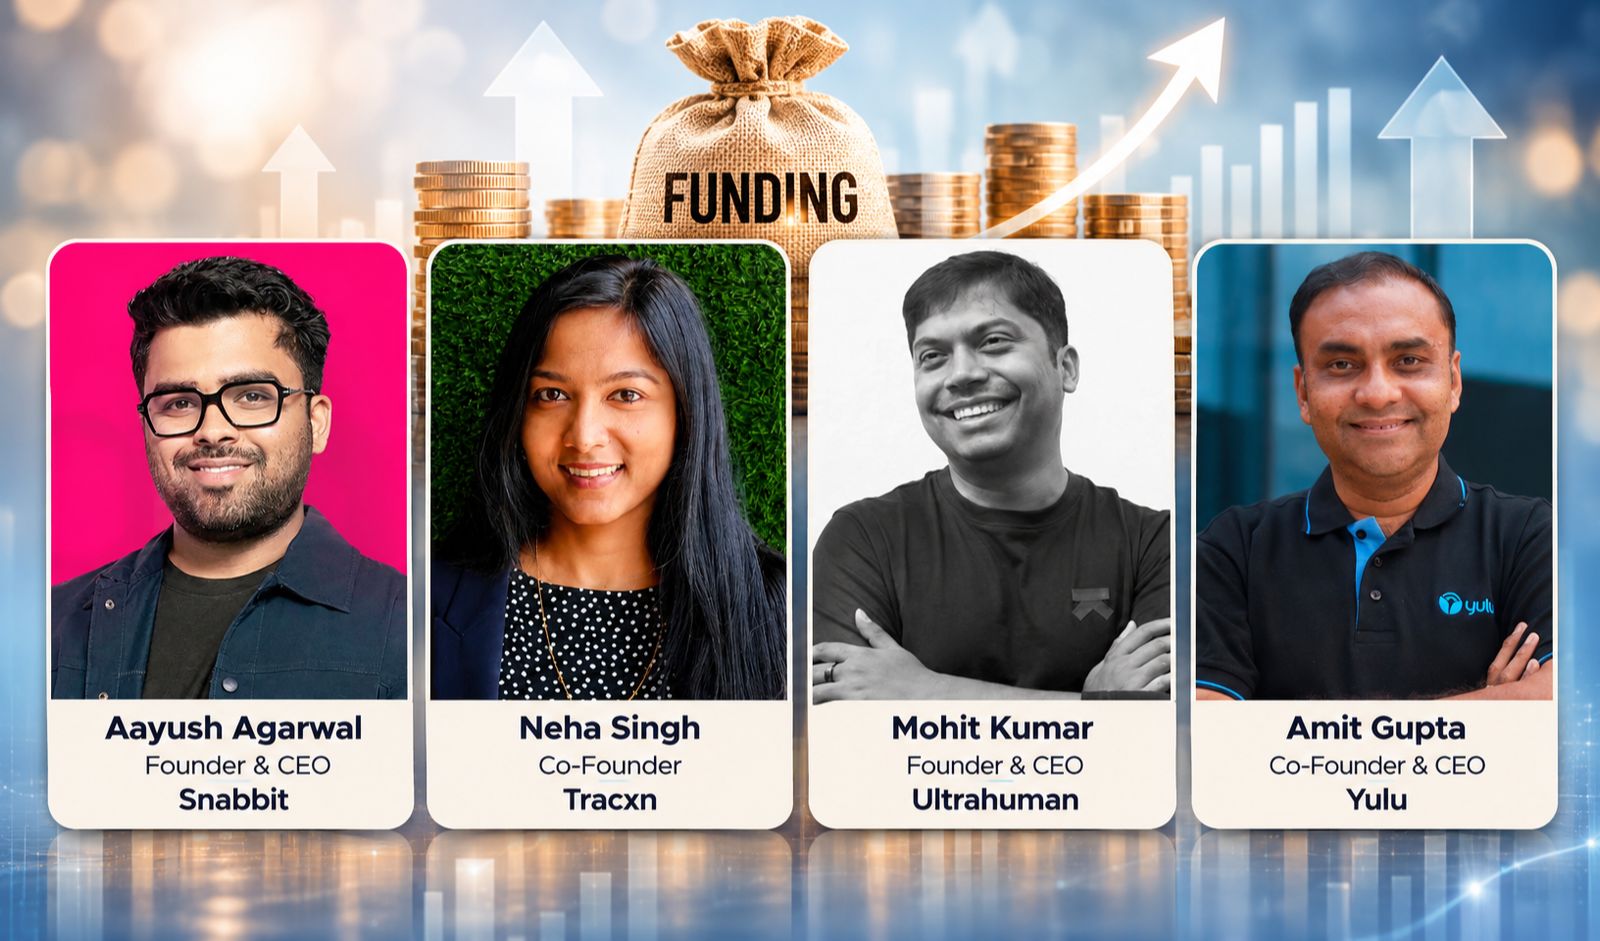
Neha Singh, Co-founder of Tracxn, said, “The 33 percent year-to-date decline in India's B2C e-commerce funding to USD 1.6 billion in 2026 reflects a strategic calibration in investor sentiment rather than a structural retreat from the digital retail ecosystem, which has cumulatively raised USD 49.2 billion across over 47,300 companies.”
She added that the reduction in deal activity indicates a more selective approach to capital allocation. Investors are giving greater importance to strong unit economics and businesses that can demonstrate a clear path to profitability.
The difference is particularly visible across funding stages. Early-stage investments remained relatively stable, while late-stage and seed-stage funding experienced significant declines.
Also read: How Ambrane is Creating Its Next Growth Chapter
Early-Stage Funding Shows Resilience
Early-stage companies raised USD 872 million in 2026 YTD, registering a 3 percent increase from USD 846 million in 2025. This segment accounted for 54 percent of the total capital deployed during the period, across 97 funding rounds.
In comparison, late-stage funding declined 51 percent to USD 587 million from USD 1.2 billion in 2025. Seed-stage investments also fell 50 percent, reaching USD 169 million compared with USD 339 million in the previous year.
Among the notable transactions, FS Life raised USD 110 million through a Series B round in February, making it the largest funding round of 2026 YTD. Ultrahuman followed with a USD 65 million Series C round in May. At the seed stage, Elixiir Foods raised USD 9 million in February.
The decline in later-stage investments also points towards caution around company valuations and exit opportunities, particularly as acquisition and public listing activity remained lower than the previous year.
Also read: How India’s Beverage Shelf Is Evolving
Six Companies Attract Significant Capital
Despite the overall slowdown, a small group of companies continued to attract substantial investor interest. Six businesses raised USD 50 million or more during 2026 YTD, collectively accounting for a significant share of the sector's funding.
These included FS Life with USD 110 million, Ultrahuman with USD 113 million across two Series C tranches, Yulu with USD 63 million, Snabbit with USD 56 million, FirstClub with USD 55 million, and Nua with USD 50 million.
Together, the six companies raised USD 447 million, accounting for 28 percent of total funding during the period. Their investments highlight interest in differentiated consumer brands, health and wellness, shared electric mobility, quick commerce and high-frequency household services.
Ultrahuman raised USD 48 million in March and another USD 65 million in May. Founder and CEO Mohit Kumar said the company is working towards building technology that can continuously understand the human body and translate health-related signals into useful everyday insights.
“For the longest time, computers have understood almost everything about the world except the person using them,” Kumar said.
He added that the company aims to combine sensing technology, engineering, algorithms, physiology and clinical science to develop products that can help consumers better understand areas such as sleep, cardiovascular health, fertility and metabolic health.
Also read: From Organic Hampers to Personalised Gifts
Meanwhile, Yulu is looking to expand its shared electric mobility operations. Amit Gupta, Co-founder and CEO of Yulu, said its USD 93 million Series C fundraise would support its ambition to build shared EV infrastructure across major Indian cities.
“Our EBITDA-positive growth model — a function of full ecosystem ownership, operational excellence and disciplined unit economics — positions Yulu to become the default mobility option for quick commerce and services platforms and gig workers in India,” Gupta said.
He added that Yulu plans to quadruple its fleet to 200,000 electric vehicles over the next two years and expand its mid-speed EV offering for bike taxis and e-commerce deliveries.
Snabbit, which raised USD 56 million in a Series D round led by SIG, is also preparing for its next phase of expansion. Founder and CEO Aayush Agarwal said the company intends to strengthen its balance sheet while expanding its presence across micro-markets and entering new service categories.
“We have raised USD 56 million in Series D round funding, led by SIG, along with Mirae and Bertelsmann,” Agarwal said, adding that existing investors, including Lightspeed, Elevation and Nexus, continue to support the business.
Also read: Diwali Brings Growth in Furniture and Home Decor Sales
Bengaluru Leads City-Wise Funding
Bengaluru remained the largest funding destination for India's B2C e-commerce companies in 2026 YTD, attracting USD 686 million, or 43 percent of the total capital raised. Its cumulative funding across the segment has reached USD 29 billion.
Ultrahuman's two Series C rounds and Yulu's USD 63 million fundraise contributed to the city's performance.
Mumbai ranked second, attracting USD 286 million, supported by Nua's USD 50 million Series C investment. Gurugram followed with USD 199 million in funding during the period.
The concentration of capital in these three cities reflects their continued importance as centres for consumer-focused startups and digital businesses.
Also read: India’s Alco-Bev Market Sees Festive Push as Premium Spirits Gain Ground
Acquisitions and IPO Activity Slow
Exit activity also moderated during 2026. The sector recorded 19 acquisitions compared with 25 in 2025, while IPO activity declined to seven listings from 13 in the previous year.
L'Oréal's USD 434 million acquisition of beauty and personal care company Innovist in June was the largest disclosed acquisition during the period. Other notable transactions included USV India's USD 138 million acquisition of Wellbeing Nutrition and Wipro Consumer Care's USD 41 million acquisition of Dermatouch. Marico also acquired 4700BC and Cosmix for USD 25 million each.
Across the sector, 261 acquisitions have been recorded over the years, with Reliance Retail emerging as the most active acquirer with 10 deals.
On the public markets front, Purple Style Labs and Rentomojo listed in September, recording market capitalisations of USD 488 million and USD 438 million, respectively. The remaining five listings had market capitalisations of USD 43 million or less.
Astrotalk was the only new unicorn in the B2C e-commerce segment in 2026 YTD. The previous addition was quick-commerce company Zepto in August 2023.
Also read: Diwali Demand Puts India’s Home Appliance Market on a Premium Growth Path
Measured Growth Expected in 2027
Looking ahead, the funding environment is expected to remain measured, with investors likely to continue prioritising sustainable business models over aggressive expansion.
Singh said, “Looking ahead to 2027, funding trends may indicate a measured stabilization rather than an aggressive rebound.”
She added that capital deployment could remain focused on early-stage innovation and capital-efficient omnichannel models. Late-stage investments, meanwhile, may depend on the performance of recently listed companies and the ability of established businesses to demonstrate disciplined margin expansion.
The latest funding trends suggest that India's B2C e-commerce sector is entering a more disciplined phase. While the overall investment pool has contracted, capital continues to flow towards businesses with differentiated offerings, strong operating models and opportunities to scale. The coming year will indicate whether this cautious approach translates into a broader recovery in funding or becomes a longer-term feature of the sector.
Also read: How India’s Edible Oil Market Is Evolving
A college student in Pune wants an iPhone with a genuinely good camera. A new one costs more than her monthly stipend can justify. A few years ago, her only real option would have been settling for a budget Android instead. Today, she has a third path that didn't really exist in any organised form a decade ago, a certified, warrantied, pre-owned iPhone at nearly half the price of new.
That shift, happening quietly across millions of similar decisions, is what's now being called India's upgrade economy, and the numbers behind it are hard to ignore. According to Counterpoint Research's Global Pre-Owned Smartphone Market Report for H1 2026, India's refurbished smartphone volumes grew 13 percent year on year in the first half of the year, even as sales of new smartphones actually fell by around 11 percent over the same period. That's not a small divergence. It suggests a genuine behavioural shift, not just budget conscious buyers settling for less, but buyers deliberately choosing better, older devices over newer, more expensive ones.
The same report found premium brands gaining ground specifically within the organised, certified segment of the refurbished market, a detail that matters more than it might seem. India's pre-owned electronics market has historically been dominated by unorganised sellers, roadside shops, informal resellers, classified listings with no real accountability if something goes wrong after the sale. Counterpoint's data puts the organised channel's share at roughly 20 percent of the total market, which sounds modest until you realise how much room that leaves for structured, trust-driven businesses to grow into.
This is really the crux of why the upgrade economy matters beyond just cheaper phones. Pre-owned technology has always existed in India. What's changing is the infrastructure around it, warranty coverage, quality certification, verification checks, and genuine after sales support, the same things that made buying new devices feel safe for decades.
A growing number of certified pre-owned platforms now illustrate this shift concretely. The stronger ones put every device through a documented, multi-point inspection covering hardware, software, battery health and cosmetic condition, alongside verification of activation lock status and device identity history, two checks that directly address the biggest fears buyers have historically had about used electronics, a stolen device, a hidden lock, a battery quietly dying within months. Many now offer up to twelve months of warranty, a short return window, and financing through EMI, features that used to be reserved almost exclusively for new device purchases. Trade-in and exchange programmes have also become common, letting customers put an older device toward a pre-owned upgrade, and some platforms operate physical stores in major cities, giving buyers somewhere to walk in and get support rather than relying purely on an online transaction with no recourse.
This model addresses something the broader market data hints at but doesn't fully explain on its own. Industry tracking through 2026 has repeatedly pointed to rising demand for higher-priced refurbished devices specifically, even as the cheapest segment of the refurbished market has been shrinking as a share of total sales. In other words, Indian buyers aren't gravitating toward pre-owned technology purely to save money at the bottom end. They're using resale and refurbishment markets to access premium technology they otherwise couldn't justify buying new, a phone with a great camera, a laptop capable of real creative work, a smartwatch with cellular connectivity.
That's a meaningfully different economy from the one refurbished electronics operated in a decade ago, when pre-owned essentially meant compromise. It's becoming a legitimate parallel path to ownership, one where the ceiling isn't "what can I afford new" but "what can I access certified and warrantied, at a price that makes sense."
What happens next likely depends on how much the organised segment of this market can grow relative to the unorganised one still handling roughly four out of every five refurbished transactions in the country. Trust, not price, is the actual bottleneck holding back faster adoption, and trust is built slowly, through certification standards, warranty follow through, and enough repeat customers willing to vouch for the experience.
For now, the trajectory looks fairly clear. As new device prices in India continue climbing, and certified pre-owned platforms continue building the infrastructure that makes pre-owned technology feel safe rather than risky, more buyers are likely to start their next upgrade not by asking which new phone to buy, but by asking which excellent, certified, pre-owned device they can now actually afford.
Authored by:
Manil Shetty, Managing Director, Maple Digital Technology
For many young Indians, a computer is no longer a device used only in a college laboratory or an office. It is where they attend classes, prepare assignments, learn software, edit videos, apply for internships, manage side projects and unwind. These overlapping uses are changing what buyers expect from personal computing and moving the market beyond the idea of a laptop as a work-only purchase.
Young consumers are not one uniform group. A school student, design aspirant, first-time job seeker and young professional may all be buying a personal computer, but their priorities differ. What connects them is the expectation that one device should support several parts of the day without demanding a major compromise on cost or usability.
The First Computer Has Its Own Significance
For many students, a personal computer is an investment in independence. They want to complete coursework without borrowing a family member’s device, join online classes, prepare presentations and organise files. As they move into higher education, requirements become more specific. A commerce student may need spreadsheets and research tools; a design student may look for creative applications; someone learning to code needs an environment in which to practise regularly.
The first purchase is therefore a decision that involves more than comparing prices. Buyers and their families want to know whether a device can run the applications they expect to use, remain useful as studies progress and offer reliable after-sales service. They are evaluating it against a list of tasks, not just a processor name or specification sheet.
Performance is measured in everyday use
Young buyers may compare specifications, but their experience is shaped by how a device performs across a full day. Can it run several browser tabs alongside a document? Does it start quickly? Can it handle a video call while notes are open? Will it support the applications they regularly use without slowing down? For students and young professionals, these everyday experiences often matter as much as the specifications on paper.
These everyday tasks indicate how well a device handles multiple activities and responds to regular usage demands. For students, this could mean attending online classes while accessing study material, preparing assignments, researching topics and switching between applications without disruptions. For young professionals, it could involve managing documents, virtual meetings and browser-based tools through the day. Ultimately, consistent performance and reliability in these situations often matter as much as the specifications on paper.
Portability and everyday convenience
Portability also matters because the device moves between a bedroom desk, classroom, library, coaching centre and shared workspace. Weight, battery life, screen quality, keyboard comfort and durability influence the decision alongside processing power and memory. Price remains important, particularly for first-time buyers and families managing education expenses. But value is not the lowest upfront price. A device that cannot support a learner’s regular applications, or becomes difficult to use as requirements grow, can prove a poor purchase. Brands need to explain what a product is designed to do, where its limits lie and which user it serves.
One device, several ambitions
Young consumers are increasingly balancing learning, creating and earning through their personal computers. A person might start the day attending classes, then continue editing videos in the afternoon, building their portfolio in the evening and working on freelance assignments, such as video editing or graphic design, at night. Others use computers to study languages, code, run an online business or prepare for competitive exams. This shift has changed how consumers evaluate a device’s capabilities. Multitasking, storage space, reliable internet connectivity, useful software and a comfortable user experience all contribute to how well a computer fits into everyday activities. The ability to switch between applications smoothly and manage multiple tasks efficiently can be just as important as raw performance.
Entertainment is also becoming an integral part of this computing experience, but the distinction between work and leisure isn't always clear-cut. For many young creators and professionals, the content they consume for enjoyment can also become a source of research and inspiration. A photographer might study the cinematography and framing of a film, a social media strategist might explore music for campaign ideas, or an event planner might draw inspiration from visual storytelling and performances. In these instances, entertainment and work are not separate activities; one often feeds into the other. Younger consumers therefore expect their devices to support not just content consumption, casual gaming and streaming, but also the creative exploration and research that can emerge from it.
What brands need to understand
Speed, design or low prices should not be the only aspects that are communicated through the campaigns regarding the product. The brand must know how young people use their gadgets and must state what problems each gadget solves. First-time buyers, in particular, need clear guidance on which features are essential for their needs and which specifications may not make a significant difference to their everyday experience.The young creative individual may pay more attention to the display, memory, and compatibility of applications.
Communication in retail or online stores is important as well. Demonstrations, helpful comparisons, and clear explanations can assist customers in making a decision, especially if they are buying a computer for the first time. The experience should also extend beyond the purchase, with accessible product guidance, easy-to-understand setup instructions and reliable after-sales assistance helping users make the most of their devices.
Another important shift brands need to recognise is that young consumers no longer fit neatly into fixed audience categories. Career paths are becoming increasingly fluid, with newer professions such as content creation and podcasting becoming established career choices. Individuals are also taking on multiple roles simultaneously. Someone might be pursuing an online MBA while working as a DJ and running a business, moving between being a learner, a creative professional and an entrepreneur. These roles often overlap, and so do the computing needs that come with them. Brands therefore need to look beyond conventional audience labels and understand the different ambitions, activities and workflows that shape how an individual uses their device.
Authored by:
Aman Verma, COO & Co-Founder, Primebook
Scroll through any week of retail headlines in India and a pattern jumps out. A snack brand closes a Series B. A beauty label raises growth capital. A footwear chain files its draft papers. Consumer names such as Lenskart and Meesho have already made the leap from startup decks to the stock-market ticker, and a long line of D2C brands is watching closely.
For decades, retail success in India was built on reading the customer: what sells in Ludhiana versus Kochi, how festive demand shifts year to year, which SKU deserves the eye-level shelf. That instinct still matters. But a new layer of literacy is now being demanded of everyone in the business, from the founder pitching investors to the store manager who has just been handed ESOPs. They need to understand how markets price a business.
Market Literacy Is Becoming a Retail Skill
Three shifts are pushing capital-market fluency down the retail org chart.
Listed peers have become the benchmark. When Avenue Supermarts or Trent publishes quarterly numbers, the market's reaction tells every private retailer what investors value right now, whether that is same-store sales growth, margin discipline or store expansion pace. Founders who can read that reaction negotiate better in their own funding rounds.
Equity is reaching the shop floor. ESOP pools at funded D2C brands increasingly extend beyond the head office to category managers, regional leads and senior store staff. An employee who holds stock options but has never seen a share price move is holding something they do not fully understand.
Treasury decisions are getting sharper. Mid-sized retailers and franchise owners sitting on seasonal cash surpluses are asking where that money should sit between peaks. Making that call well requires a basic grasp of risk, liquidity and volatility.
The problem is that most retail professionals learned business on the floor, not on a trading screen. And the market is an expensive classroom when lessons are paid for with real money.
Retail Already Knows How to Rehearse
Here is the irony: retail is one of the industries most comfortable with rehearsal. Brands open pilot stores before a national rollout. They soft-launch a product in two cities before committing to a full production run. Merchandisers test planograms in a handful of outlets and watch the sell-through before redesigning every shelf in the chain.
The same logic applies to markets. Before putting capital at risk, it makes sense to run a pilot, and that is exactly what trading simulators offer: a live-like market environment where orders, price swings and losses are real in every sense except the financial one.
What a Simulator Actually Teaches
A good practice environment teaches lessons that no explainer video can.
- How orders behave. The difference between a market order and a limit order feels academic until you watch one fill at a price you did not expect.
- What volatility feels like. Seeing a position swing several percent in an afternoon builds a gut sense of risk that a spreadsheet cannot.
- Position sizing. Retailers understand inventory exposure intuitively. Simulators translate that instinct into how much capital to commit to a single idea.
- Emotional discipline. The urge to exit too early on a small gain, or hold too long on a loss, shows up even with virtual money. Better to meet that urge in practice.
The barrier to starting has also dropped sharply. Many tools now run straight in the browser, and some go as far as offering demo trading without account registration, so there is no sign-up form, no KYC and no personal data to hand over. For a busy store manager, that means a fifteen-minute session during a lunch break rather than an afternoon of onboarding. For a training team, it means an entire batch of employees can try the same exercise in a workshop without anyone creating a login.
Choosing the Right Practice Ground
Low friction is useful, but the practice ground still matters, because habits formed in a simulator tend to follow people to the platform they eventually trade on. A few principles help.
Stay inside the regulated ecosystem. India offers solid practice options built around SEBI-regulated markets, including NSE's own learning and virtual-trading initiatives and the paper-trading modes that many SEBI-registered brokers provide inside their apps. Practising on instruments and rules you will actually use is far more valuable than practising on something you never should.
Check before you click. The Reserve Bank of India maintains a public Alert List of platforms that are not authorised to offer forex trading to Indian residents, and SEBI publishes registers of authorised intermediaries. A two-minute check is the retail equivalent of verifying a new supplier's GST number.
Be wary of practice tools built to convert. A simulator that constantly nudges you towards depositing money, promises guaranteed returns, or pushes leveraged forex and binary-style bets is a sales funnel, not a classroom.
Treat it as training, not a game. The point is to build judgement. Keeping a simple log of each trade, the reason behind it and the outcome turns play into learning.
A 30-Day Plan for Retail Teams
For founders and HR leads who want to build market literacy into their teams, a simple monthly structure works well.
- Week 1: Foundations. Short sessions on how exchanges work, what moves a share price, and how to read a listed retailer's quarterly results.
- Week 2: First trades. Each participant builds a small virtual portfolio of listed consumer and retail companies they know from the floor.
- Week 3: Stress test. Track the portfolio through a results season or a market-moving event and discuss what happened and why.
- Week 4: Reflection. Review trade logs together. Which decisions were driven by analysis, and which by emotion? What would the team do differently with real capital?
The cost is close to zero. The payoff is a team that understands its own ESOPs, reads competitor results with sharper eyes, and speaks the same language as the investors funding the next stage of growth.
The Retail Lesson, Applied to Markets
Every experienced retailer knows the rule: test small, learn fast, then scale. It is how winning formats are born and how costly mistakes are avoided. As Indian consumer businesses move deeper into the world of capital markets, the people who build them would do well to apply that same rule to their own financial learning.
The next big retail listing will be celebrated on the floor of the stock exchange. The people best placed to benefit from it will be the ones who rehearsed long before the bell rang.
The Indian beverage market is witnessing changes. With a growing interest in alternative options to carbonated soft drinks, there are now a variety of options available on the shelf, including colas, fruit-flavored drinks, fizzy drinks, energy drinks, and even low-sugar products.
Factors such as cost, availability, and chilled options are becoming increasingly important to the market. However, with traditional colas still being very popular, energy drinks are gaining momentum along with new drink formats.
India Energy Drink Market Share, Companies & Trends Report (2026-2031) by Ken Research: India Energy Drink Market is valued at USD 1.135 billion in the year 2026 and is expected to reach USD 2.245 billion by the year 2031, at a CAGR of 12.04 percent.
The market is largely consolidated, with companies such as PepsiCo India (Sting), Red Bull India, Monster Beverage Corporation (Monster Energy and Predator), Reliance Consumer Products (Campa Energy), and HELL ENERGY competing across affordable Rs 20 PET bottles and premium canned products.
Also read: From Organic Hampers to Personalised Gifts
Energy Drinks Gain Momentum
Energy drinks are growing faster than traditional carbonated soft drinks, although colas continue to account for a significant share of the market.
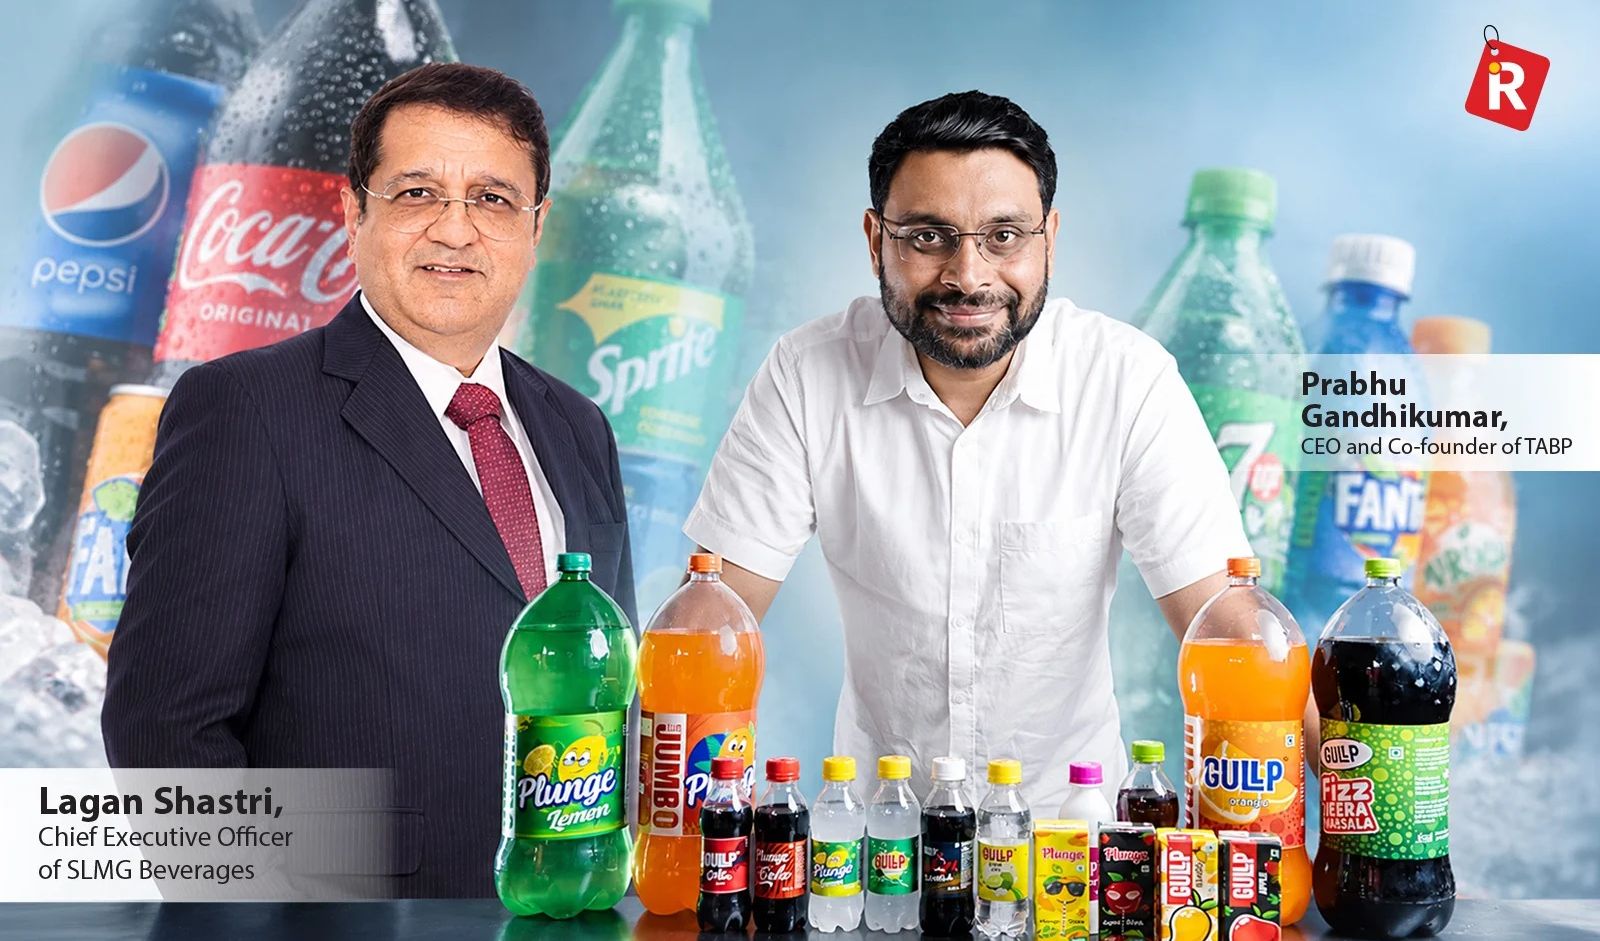
Prabhu Gandhikumar, CEO and Co-founder of TABP, said, “Euromonitor estimates that India’s energy drink volumes grew by 21 percent in 2025. Affordable formats are helping the category reach consumers who would previously have found it expensive to try.”
He added that this should not be seen as a complete shift away from colas, as consumers purchase different beverages for different occasions.
Lagan Shastri, Chief Executive Officer of SLMG Beverages, said, “Energy drinks are expanding faster from a smaller base, while colas retain substantial scale. Younger consumers, new consumption occasions, chilled availability and greater choice are supporting growth across both segments.”
Also read: Diwali Brings Growth in Furniture and Home Decor Sales
Low-Cost Packs Gain Traction
Price continues to play an important role in India's beverage market, particularly in smaller towns and rural areas. Single-serve packs and affordable price points are helping brands reach consumers who prefer making small, frequent purchases.
Shastri said, “Affordable single-serve packs are a key growth driver. Consumers value accessible price points and convenient, immediate consumption, reinforcing the importance of the right pack-price architecture and widespread chilled availability.”
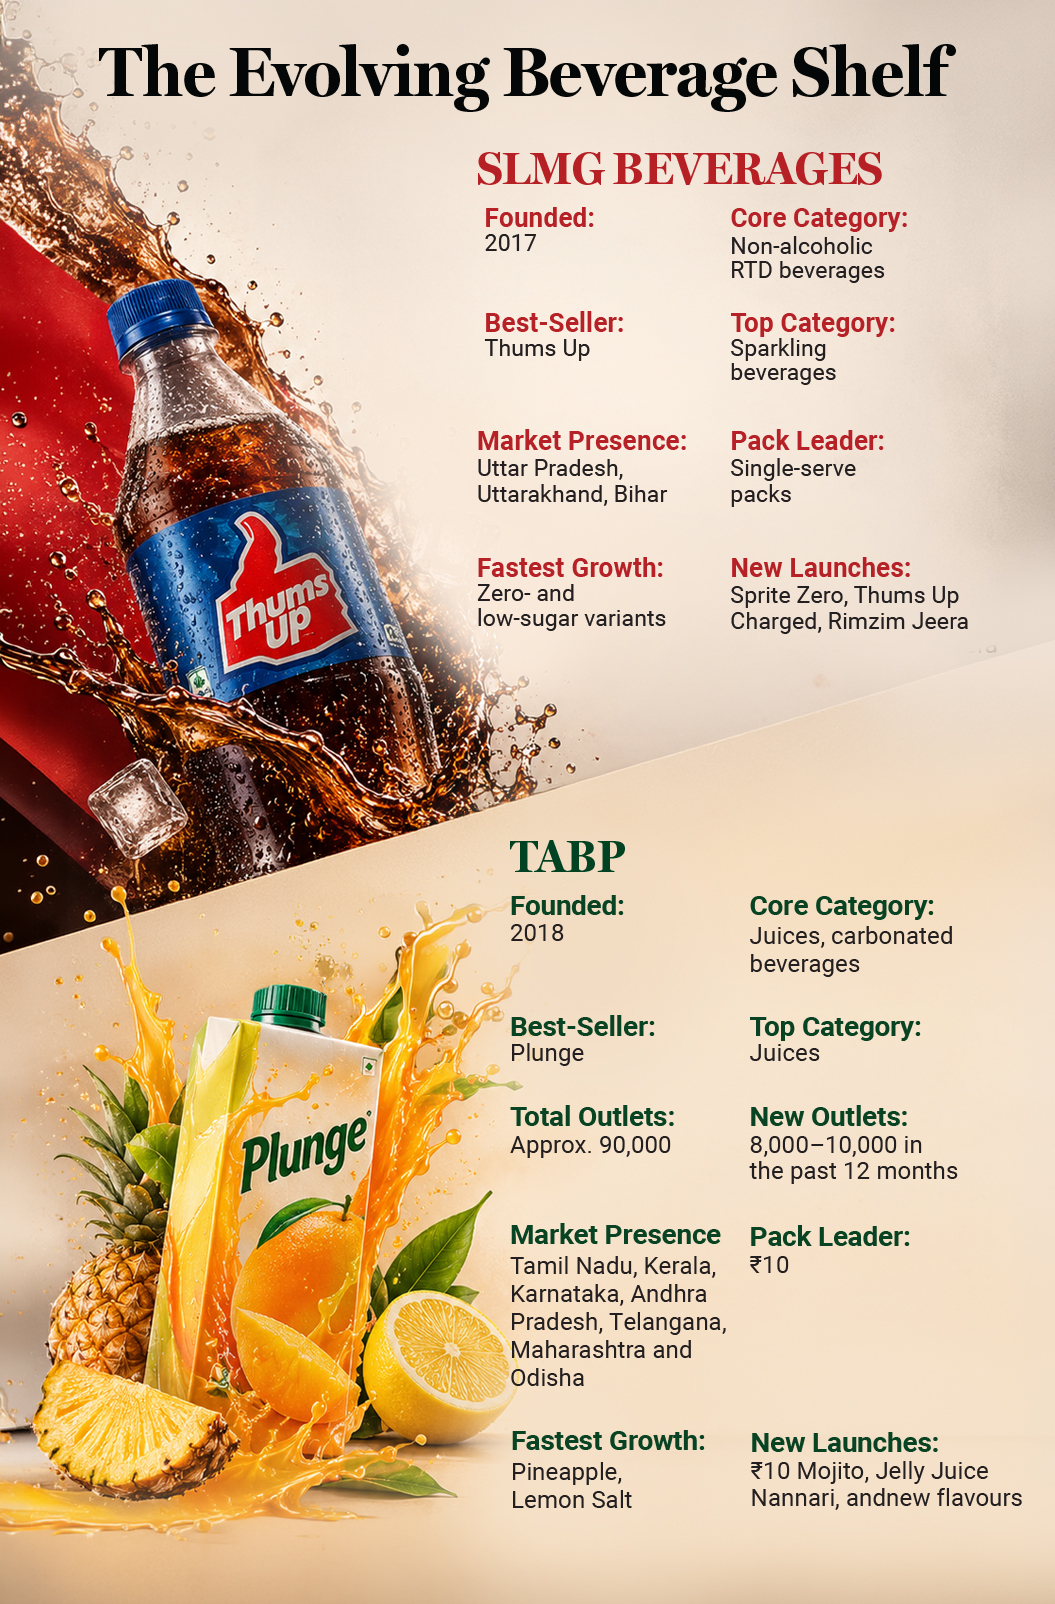
For TABP, the Rs 10 price point remains its best-selling and fastest-moving offering. Gandhikumar explained that consumers often make purchasing decisions based on the amount they can comfortably spend at a particular time, rather than the value per litre offered by larger packs.
He said the company has also introduced a Rs 10 mojito, following the same approach of offering different flavours at accessible prices.
Also read: India’s Alco-Bev Market Sees Festive Push as Premium Spirits Gain Ground
 Expanding Retail Reach
Kirana stores, neighbourhood shops and bakeries remain key beverage sales channels, while quick commerce is emerging as an additional avenue for wider retail distribution and growth.
According to Gandhikumar, TABP added approximately 8,000–10,000 retail shops over the past 12 months, taking its estimated presence to around 90,000 shops across Tamil Nadu, Kerala, Karnataka, Andhra Pradesh, Telangana, Maharashtra and Odisha.
He said, “For the consumer we serve, the nearby shop is an important point of purchase. Our distribution decisions therefore begin with local demand, the right assortment and dependable replenishment.”
Shastri also highlighted the growing role of quick commerce but said kiranas remain the distribution backbone. He added that the company is working with The Coca-Cola Company to improve availability, channel-specific assortments and digital activation.
Also read: Diwali Demand Puts India’s Home Appliance Market on a Premium Growth Path
Changing Beverage Preferences
Consumers are exploring diverse beverage options, including fruit-based, sparkling, energy and zero-sugar drinks, choosing products based on changing preferences and consumption occasions.
Shastri said, “Consumer preferences are broadening, not simply shifting away from cola. Sparkling, fruit-based, energy and zero-sugar choices serve different occasions.”
At SLMG Beverages, sparkling beverages remain the principal contributor to portfolio growth. The company operates across Uttar Pradesh, Uttarakhand and Bihar, with Thums Up among its best-selling products. Its newer offerings include Sprite Zero, Thums Up Charged and Rimzim Jeera. Zero- and low-sugar variants are also among its faster-growing segments.
For TABP, juices remain the largest category, with Plunge as its best-selling brand. Pineapple and lemon salt are currently its fastest-growing products. Founded in 2018, the company focuses on juices and carbonated beverages and has expanded its portfolio to include jelly juice, additional flavours and nannari.
Also read: How India’s Edible Oil Market Is Evolving
Growth
As well as energy drinks, the market for non-alcoholic ready-to-drink products in India is growing. This includes soft drinks, fruit drinks and packaged waters. The market was estimated by Redseer to be worth USD 20 billion in 2025 and expected to grow to USD 40 billion by 2030, growing at approx. 14 percent per annum.
Gandhikumar said he expects an average growth rate of 12-15 percent per annum for the next couple of years, although weather can impact the market.
As prices of packs have become more affordable, the market has broadened with more variety. Whilst traditional cola markets remain strong, there are many new growth opportunities with energy drinks, fruit-based and low-sugar products.
Also read: Small Feet, Big Business: Kids’ Footwear Steps Up Growth
The festive season has traditionally been one of the biggest shopping periods for India's fashion and retail industry. From new clothes and footwear to accessories and festive essentials, consumers have always looked forward to making purchases during this time. However, the 2026 festive season revealed a noticeable shift in shopping behavior. Indian consumers continued to participate in festive sales, but they became more careful about how much they spent, what they purchased, and where they shopped.
Indian shoppers are increasingly moving towards value-driven fashion commerce, according to Fynd's Report. While festive shopping remained strong, consumers were no longer buying simply because discounts were available. Instead, they were comparing prices, looking for better deals and prioritizing products that offered practical value.
Value Takes Priority as Consumers Become More Selective
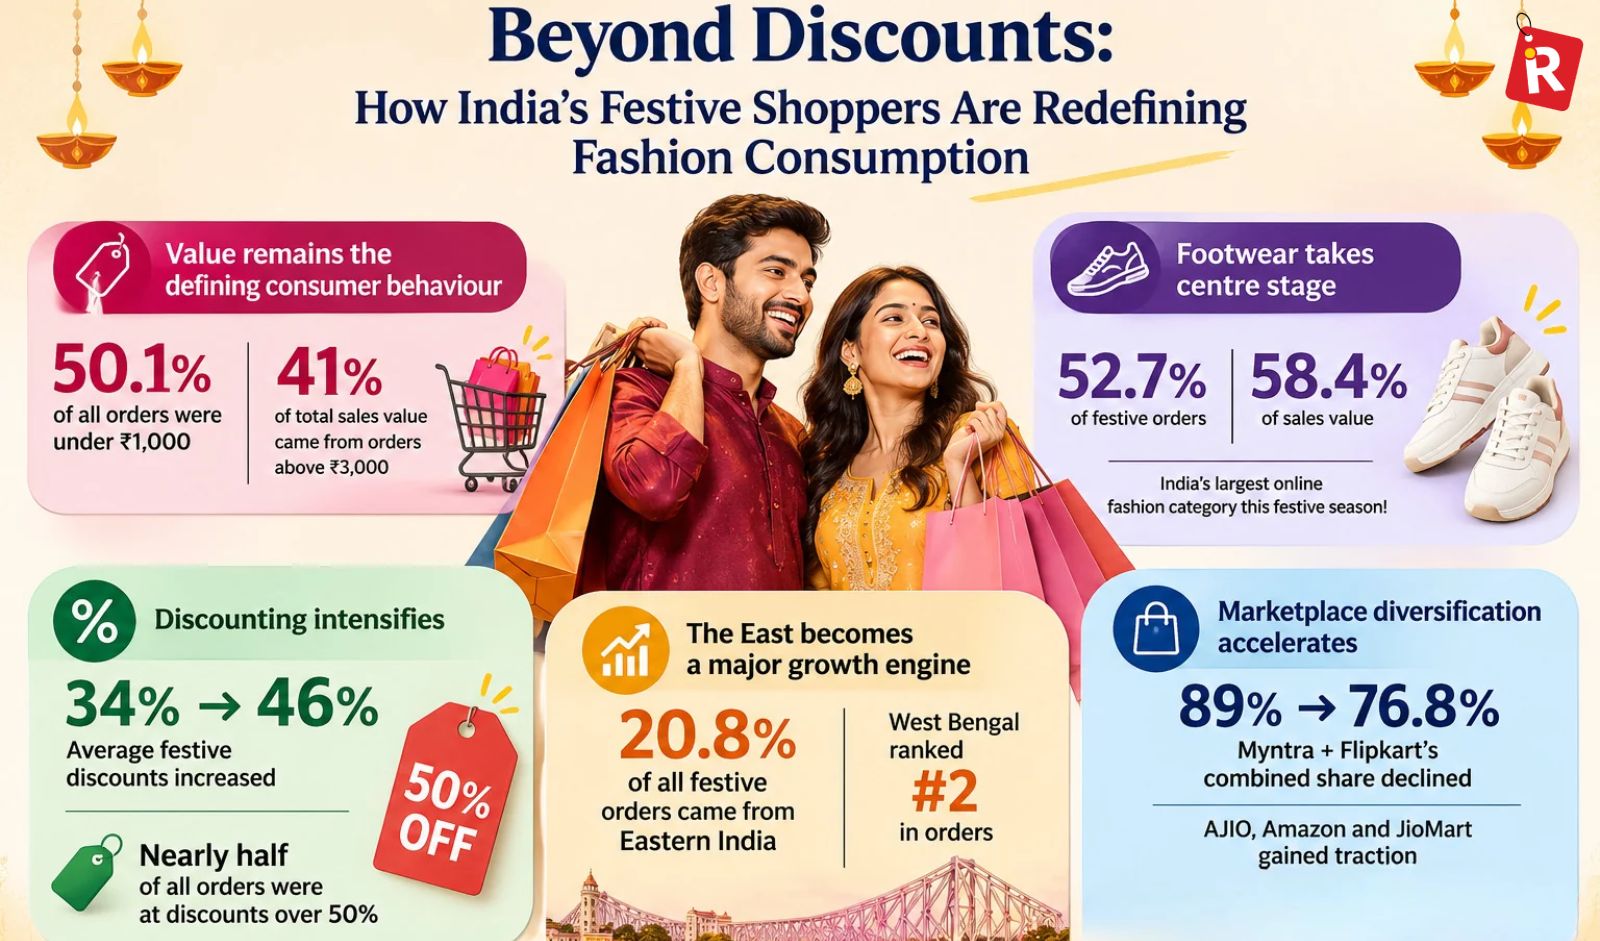
One of the biggest findings of the report is the growing importance of affordability. Around 50.1 percent of all festive orders were placed below Rs 1,000, indicating that a large number of consumers preferred keeping their purchases within an accessible price range.
However, this does not mean Indian shoppers have stopped spending on premium products. Orders above Rs 3,000 accounted for only 11.8 percent of total purchases but contributed more than 41 percent of the overall sales value. This shows that consumers are still willing to spend on higher-priced products when they see value in the purchase.
Footwear Emerges as the Biggest Fashion Category
Another major highlight of the report is the growing popularity of footwear. During the 2026 festive season, footwear accounted for 52.7 percent of all festive orders and contributed 58.4 percent of total sales value.
This marks a significant change from 2025, when footwear represented just 33 percent of festive orders. The growing preference for footwear suggests that shoppers are increasingly prioritizing products that can be used beyond the festive season. Unlike occasion-specific clothing, footwear often serves both everyday and special-occasion needs, making it a practical investment for consumers.
Meanwhile, clothing's share of festive orders declined from 48 percent in 2025 to 34.5 percent in 2026. This does not necessarily indicate a decline in interest in fashion. Rather, it points towards consumers becoming more selective about discretionary clothing purchases.
Bigger Discounts, Smarter Shopping
Discounts continued to play an important role in influencing festive purchases. However, brands had to offer more attractive deals to capture consumer attention. According to the report, average festive discounts increased from 34 percent to 46 percent. Nearly half of all orders were placed at discounts exceeding 50 percent.
This indicates that consumers were actively looking for promotions and were increasingly sensitive to pricing. At the same time, deeper discounting also puts pressure on retailers to balance sales growth with profitability.
The report suggests that the future of festive retail will depend not just on how much brands discount their products, but also on how effectively they understand customer expectations.
Eastern India Becomes a Strong Growth Market
Regional shopping patterns also revealed an important shift during the festive season. Eastern India emerged as one of the strongest growth markets, contributing 20.8 percent of all festive orders.
West Bengal became India's second-largest ordering state, highlighting the growing importance of the region in online fashion commerce. This development reflects the expanding reach of digital marketplaces and the increasing participation of consumers beyond traditional metropolitan markets. It also presents an opportunity for brands to rethink their regional strategies.
Tier II Cities Drive the Next Wave of Demand
Beyond regional growth, smaller cities are becoming increasingly important for India's fashion industry. The contribution of Tier II cities to festive orders increased from 19 percent in 2025 to approximately 35 percent in 2026. This sharp rise highlights how online fashion shopping is expanding beyond India's largest urban centres.
Tier I cities continued to contribute approximately 43 percent of total orders and 56 percent of gross merchandise value (GMV). However, the growing contribution from Tier II markets signals a wider consumer base and new opportunities for brands.
Marketplace Preferences Continue to Evolve
The report also highlights a shift in how consumers are choosing online shopping platforms. Myntra and Flipkart continued to lead the fashion marketplace landscape. However, their combined share declined from 89 percent to 76.8 percent during the festive season.
At the same time, platforms such as AJIO, Amazon and JioMart gained traction, indicating that shoppers are exploring more options before making a purchase.
This growing marketplace diversification is important for brands. Depending heavily on one or two platforms may limit their ability to reach different customer segments. A wider marketplace presence can help brands improve visibility, connect with new shoppers, and reduce dependence on individual sales channels.
Digital Payments Gain Momentum
Payment preferences also continued to change during the 2026 festive season. Online payments accounted for 56.5 percent of all orders, reflecting the growing acceptance of digital payment methods.
Prepaid adoption also increased across Eastern markets, indicating a shift in consumer payment behaviour in these regions.
As more consumers become comfortable with prepaid transactions, brands can also explore ways to encourage digital payments through relevant offers and a seamless shopping experience.
Returns Remain an Important Retail Challenge
While festive demand remained encouraging, managing returns continued to be an important concern for fashion retailers.
The overall return rate stood at 11.8 percent during the festive season. Clothing recorded a category-wise return rate of 14.9 percent, while footwear reported a lower return rate of 10.5 percent.
These numbers highlight the need for brands to focus on product information, accurate sizing, quality checks, and better product representation online. Reducing returns is not just about controlling operational costs. It is also about improving customer satisfaction and building long-term trust.
What the 2026 Festive Season Means for Retailers
Commenting on the findings, Ragini Varma, Chief Business Officer - India, Fynd said, “This festive season unfolded against a very different backdrop. Consumers were navigating higher borrowing costs, elevated fuel prices, global geopolitical uncertainty, and continued pressure on household budgets. In that environment, value emerged as the defining theme of the season. Shoppers compared more, planned purchases more carefully, and looked for products that justified their spend. For brands, the opportunity is not simply to sell more, but to understand how customer priorities are evolving and deliver the right value, assortment and experience at the right moment.”
The findings point towards a clear shift in India's fashion retail market. Consumers are still interested in festive shopping, but their expectations are changing. Affordability, product utility, discounts, convenient payments, and regional relevance are increasingly influencing purchase decisions.
For retailers, the next phase of growth will require a more thoughtful approach to commerce. Diversifying marketplace presence, developing stronger regional strategies, planning discounts more carefully, encouraging prepaid payments, and understanding category-specific demand will become essential.
Ultimately, the future of fashion commerce will not be defined by the biggest discounts or the highest number of orders. It will be shaped by how well brands understand the value their customers are looking for.
The dining table is becoming something more than a place to serve food. Indian consumers are increasingly focusing on the way their dining spaces look and feel, be it well-chosen plates and bowls, matching serveware, or chic table settings.
From home entertaining to festive occasions, gifting, or changing home décor tastes, dinnerware is moving from a household staple to a lifestyle choice, creating new opportunities for design-led brands.
Growth in the Market and Shifting Consumer Preferences
The dinnerware market in India is witnessing steady growth due to increasing demand for premium, design-led, and functional products.
The overall tableware market is expected to grow at a CAGR of 4.9 percent from 2025 to 2030, whereas the ceramic tableware is anticipated to register around 10 percent CAGR from 2025 to 2029.
Changing lifestyles, home hosting, gifting, and growing interest in home décor are helping to transform dinnerware from a household necessity to a lifestyle and personal expression category.
Also read: From Organic Hampers to Personalised Gifts
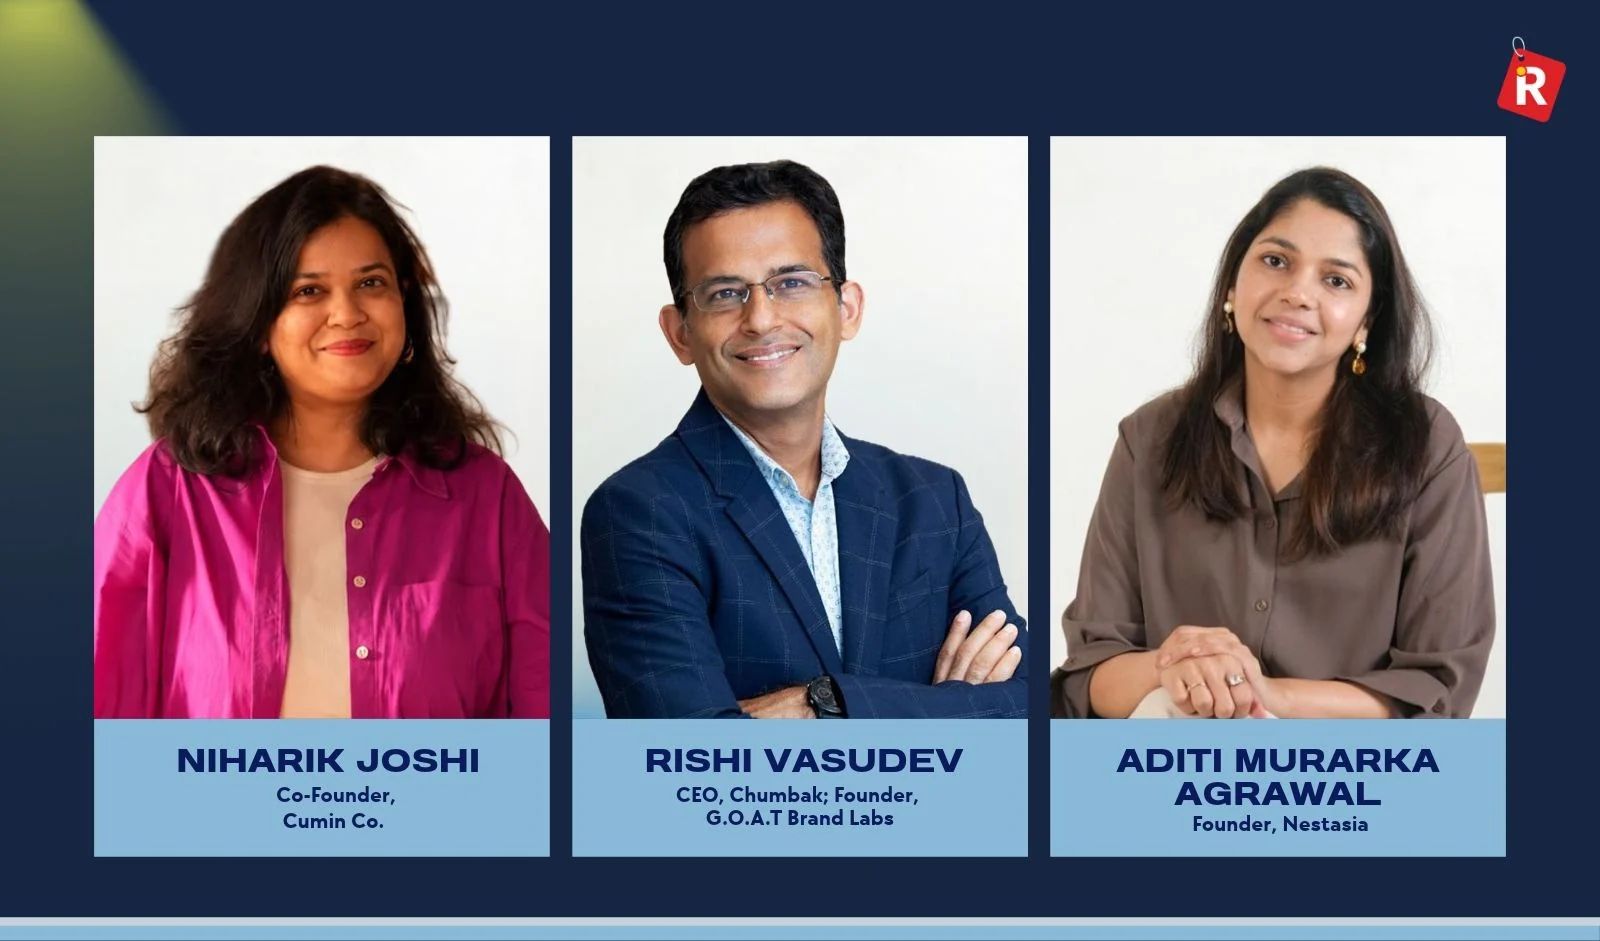
Niharik Joshi, Co-founder of Cumin Co., said, "The dinnerware category in India is growing rapidly, and we're seeing a very interesting shift in the way consumers approach it. Traditionally, dinnerware was largely a functional purchase. Today, it is increasingly becoming a lifestyle."
She highlighted the resurgence of home hosting as a key driver of this shift. Consumers are increasingly inviting friends and family over for meals and investing in products that reflect their personal taste and home aesthetics.
"People want their dinnerware to reflect their aesthetic, their taste, and the kind of experience they want to create for their guests," Joshi added.
Also read: Diwali Brings Growth in Furniture and Home Décor Sales
Raising the bar and purchasing inspired by design
The increasing importance of aesthetics is also playing a role in purchase decisions across price segments. There is a high level of interest among consumers for unique designs and aesthetic finishes.
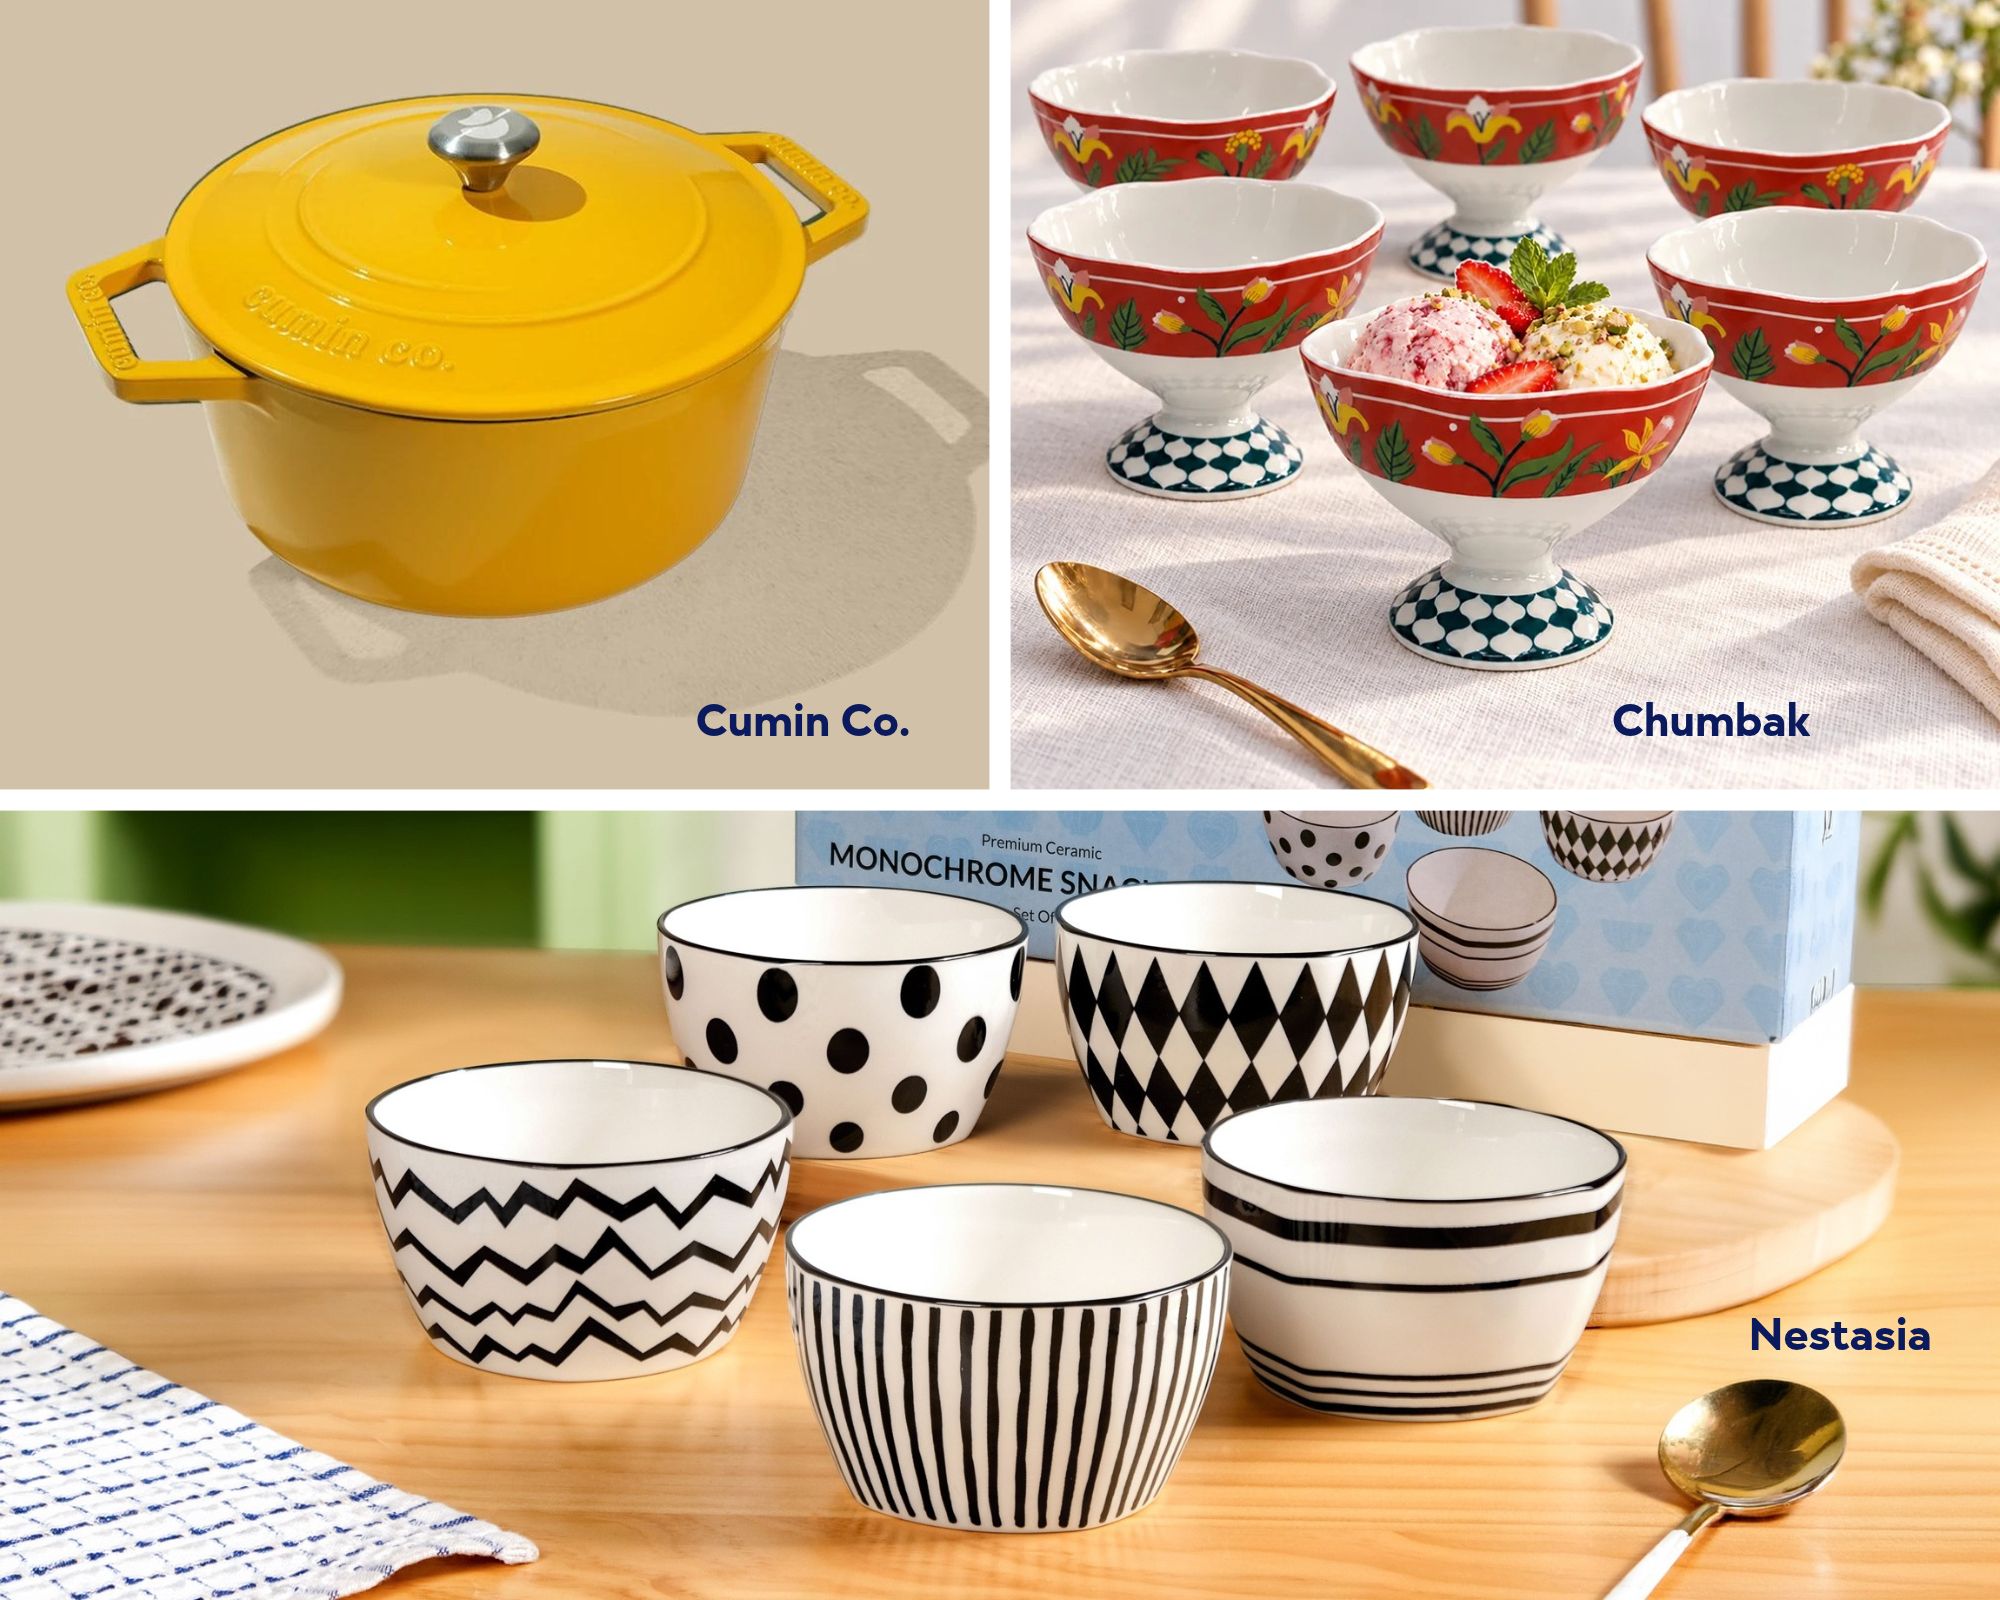
"The demand for products in the Rs 500 to 2000 range has been great. The dinnerware sets and statement pieces have a lot of interest," said Rishi Vasudev, CEO at Chumbak and Founder at G.O.A.T. Brand Labs. At the same time, consumers are increasingly willing to spend more on distinctive designs, better finishes, and products that feel special."
A similar trend is evident at Nestasia, where consumers are increasingly judging products on their design, material, detailing, and overall finish, as opposed to their utility.
Aditi Murarka Agrawal, founder of Nestasia, said, "The strongest shift we are seeing is that consumers are naturally moving towards better-designed products and aspiring to create better, more considered homes."
She added that premiumization is not simply about purchasing expensive products but about choosing better-quality and thoughtfully designed products that enhance the overall home experience.
Also read: India’s Alco-Bev Market Sees Festive Push as Premium Spirits Gain Ground
 Home hosting and gifting drive demand
Demand for dinnerware beyond everyday use is driven by weddings, holidays, gift-giving, and entertaining at home.
Consumers are increasingly opting for coordinated dining collections, serveware, glassware, and table accessories, while the growing trend of hosting gatherings at home is encouraging greater spending on table settings and dining presentation.
According to Agrawal, festive and wedding gifting remain important opportunities for the category. Nestasia is witnessing demand for curated assortments, occasion-led collections, festive products, and gift sets.
"The gifting experience itself has also evolved. It is no longer just about what is inside the box. The packaging, how the gift is presented, and the unboxing experience have become important parts of the overall experience," she said.
She further observed that consumers are putting more effort into home entertaining, with table settings, serveware, glassware, barware, and décor becoming important elements of hosting.
Chumbak is also witnessing growing demand for dining and drinkware products as year-round gifting options. Vasudev said dinnerware is increasingly becoming part of home décor, with consumers selecting products for their kitchen counters and crockery cabinets.
Also read: Diwali Demand Puts India’s Home Appliance Market on a Premium Growth Path
Growth in Online and Off-Line Retail
The rise of digital commerce and organized retail is also facilitating consumer engagement with dinnerware brands. While online channels offer wider product selections, physical stores allow consumers to experience designs, materials, and finishes before purchasing.
At Chumbak, online and offline channels contribute equally, with each accounting for 50 percent of sales. The company has an average selling price of around Rs 1,000 and operates more than 30 stores across 15-plus cities. Its best-selling product is the Marigold Kulhad Set of 4, priced at Rs 1,599.
Vasudev said the brand is strengthening its omnichannel presence across metros and emerging markets, including Guwahati, Visakhapatnam, Amritsar, and Kochi. The company is also using Chumbak Now to provide two-hour delivery. Its plans include expanding home and living categories, strengthening gifting-led collections, and reaching more consumers in emerging markets.
Also read: How India’s Edible Oil Market Is Evolving
Nestasia, meanwhile, has a predominantly online-led business, with approximately 90 percent of its sales coming through its website, e-commerce marketplaces, and quick commerce. Its offline stores contribute the remaining 10 percent.
Following its latest store opening in Jaipur, the company has 16 stores across India. Its existing network includes locations in Noida, Chandigarh, Dehradun, Pune, Hyderabad, Bengaluru, Delhi, Gurugram, and Kolkata.
The company plans to expand to 20 exclusive brand outlets (EBOs) by the end of FY27 and approximately 80 by the end of FY28. It is also exploring modern trade as an additional distribution channel.
Also read: Small Feet, Big Business: Kids’ Footwear Steps Up Growth
Safety and Use Importance Gained
Alongside design and premiumization, consumers are also becoming more conscious of product materials and food safety. Awareness around food-safe materials, lead-free glazes, and safe finishes is gradually influencing purchase decisions.
Joshi said, "Consumers may first be drawn to a product because of its design, color, or finish, but they're increasingly asking questions about what goes into making it."
"Consumers no longer want to compromise between aesthetics, functionality, and safety. Convenience is also gaining importance, particularly through the stove-to-table concept, where cookware can move directly from the kitchen to the dining table," she added.
Also read: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Expanding the Home and Kitchen Opportunity
Looking ahead, brands are seeking growth beyond traditional plates and bowls by expanding into serveware, glassware, cookware, drinkware, and kitchen accessories.
Nestasia plans to deepen its presence in bottles, lunch boxes, kitchen tools, storage containers, and cookware while expanding its retail network. Chumbak is focusing on gifting-led dinnerware and décor collections, along with new home and living categories.
India’s tableware market is creating opportunities for established and emerging brands, with overall growth projected at 4.9 percent CAGR and ceramic tableware at 10 percent.
Rising focus on home décor and personal expression is expected to drive demand for design-led, quality, safe, and convenient products.
Also read: India’s Rice Market: From Everyday Staple to Branded Growth Opportunity
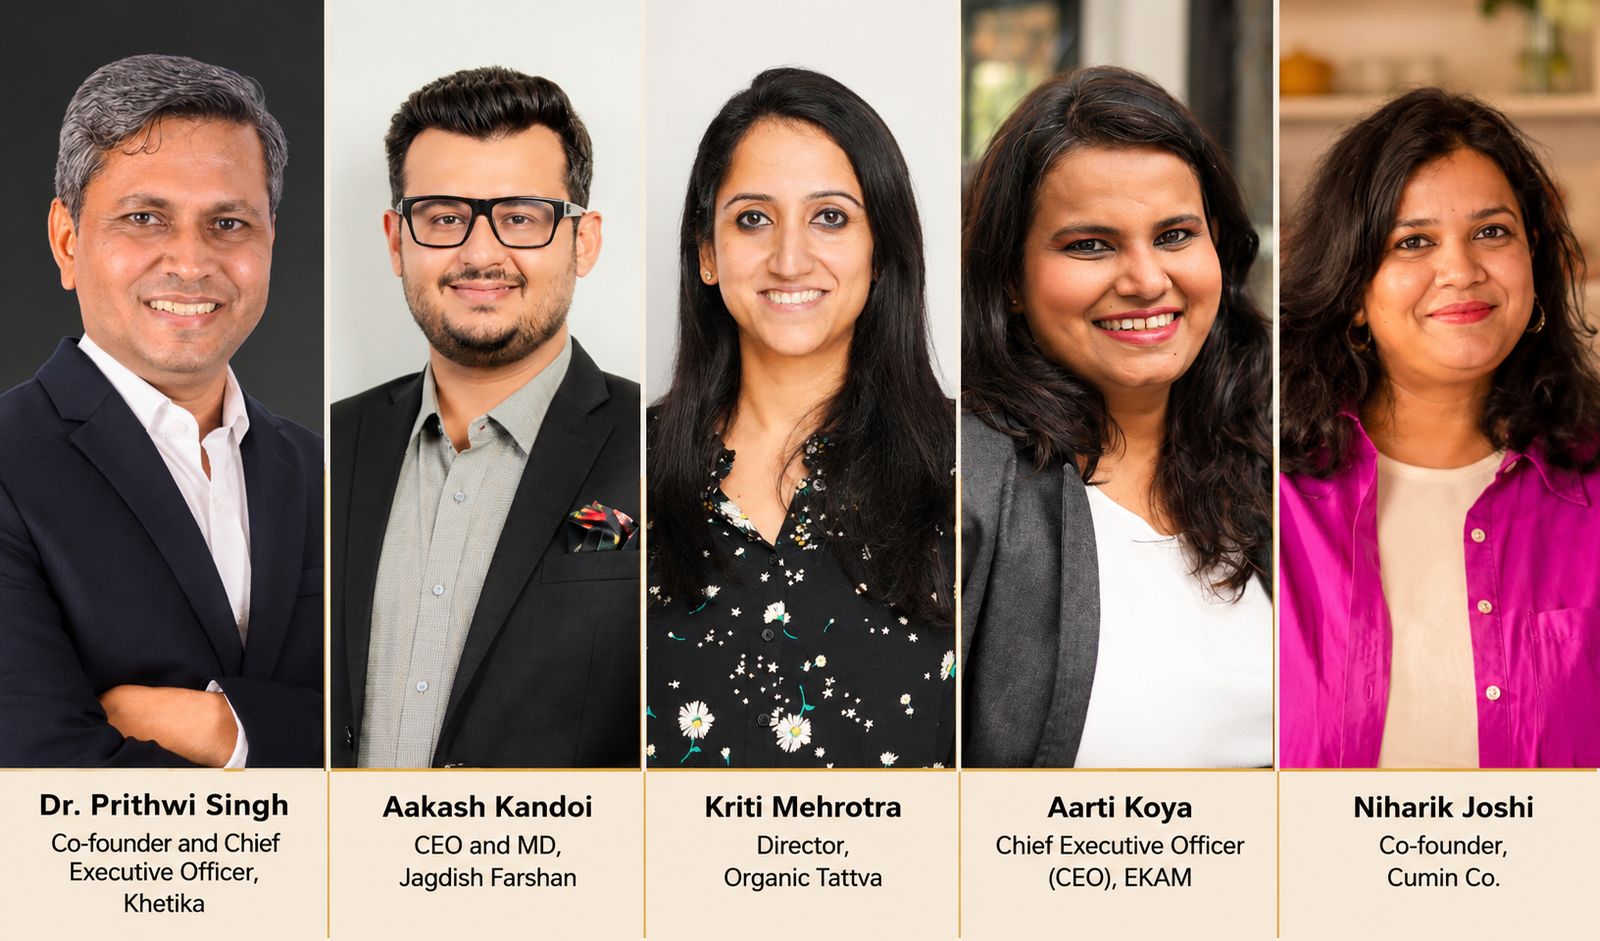
India's Diwali gifting market is changing as consumers move beyond traditional sweets and dry-fruit boxes to explore healthier snacks, organic products, home fragrances and personalised gifts. While mithai and namkeen continue to be popular, consumers are increasingly looking for gifts that offer quality, good presentation and everyday use.
Brands are also seeing growing interest in customised hampers, premium packaging and corporate gifting. From organic food boxes to scented candles and lifestyle products, the festive gifting market is expanding into new categories.
According to PwC India's 2025 Voice of the Consumer study, 84 percent of Indian consumers seek safer and healthier food choices. This growing awareness is also influencing what people choose to gift during festivals.
Also read: Malgudi: Shankar Mahadevan Takes South Indian Dining Up the Premium Ladder
Healthier Gifts Gain Popularity
Consumers are paying more attention to ingredients and product quality while choosing festive gifts. Organic foods, dry fruits, seeds, honey, ghee and healthy snacks are finding space in Diwali hampers.
Dr. Prithwi Singh, Co-founder and CEO of Khetika, said, "Diwali gifting is gradually moving beyond conventional sweets and standard dry-fruit hampers. Consumers are increasingly looking for gifts that combine quality, good taste and a greater sense of wellbeing."
He said Khetika's Premium Snacking & Gifting range includes dates, makhana, seeds and other wholesome food products. The company's healthy snacks category has recorded over 100 percent year-on-year growth.
The trend is also supported by NIQ's 2025 health and wellness research, which found that 49 percent of Indian consumers plan to buy more high-fibre foods, while 37 percent intend to add more plant-based proteins to their diets.
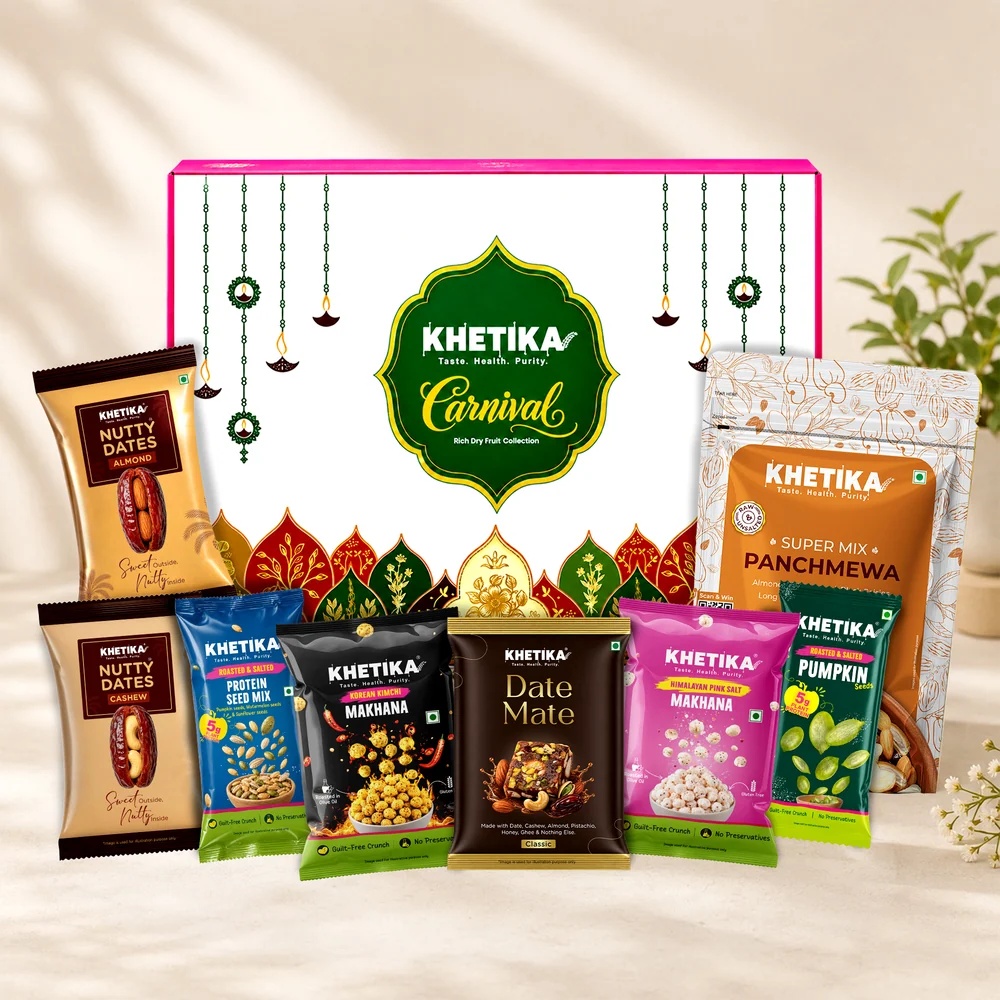 Singh said products priced above Rs 300 are witnessing strong demand. The company's Luxury Stuffed Dates Collection and Healthy Indulge Box have also seen a rise in demand. Its focus includes preservative-free and INS-free products, natural flavouring, and farmer-linked sourcing through SAATHI, supported by more than 380 quality checks and tests.
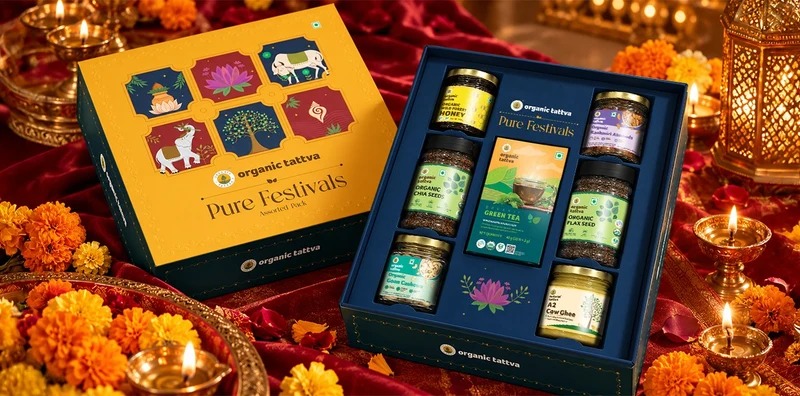
Kriti Mehrotra, Director, Organic Tattva, said, "Diwali gifting has shifted from sweets, namkeens, and sugary drinks to wellness-led hampers. People are gifting cleaner, healthier snacks, something that their families and friends would actually love to use at home."
Established in 2012 and headquartered in Greater Noida, Organic Tattva has launched two gift boxes at different price points. These include dry fruits, chia seeds, flax seeds, honey, ghee, and other organic products.
The company's average gifting order value ranges between Rs 700 and Rs 1,500. Dry fruits, honey, ghee and superfoods are among its popular gifting categories. However, Mehrotra said festive growth has remained stagnant for most FMCG companies this year. The brand is also offering festive deals across quick-commerce and e-commerce platforms.
Also read: How GRM Foods Is Growing 921 Basmati Rice Globally
Traditional Hampers Get a New Look
Traditional sweets and savoury snacks continue to be important during Diwali, but consumers are showing greater interest in curated hampers that bring different products together.
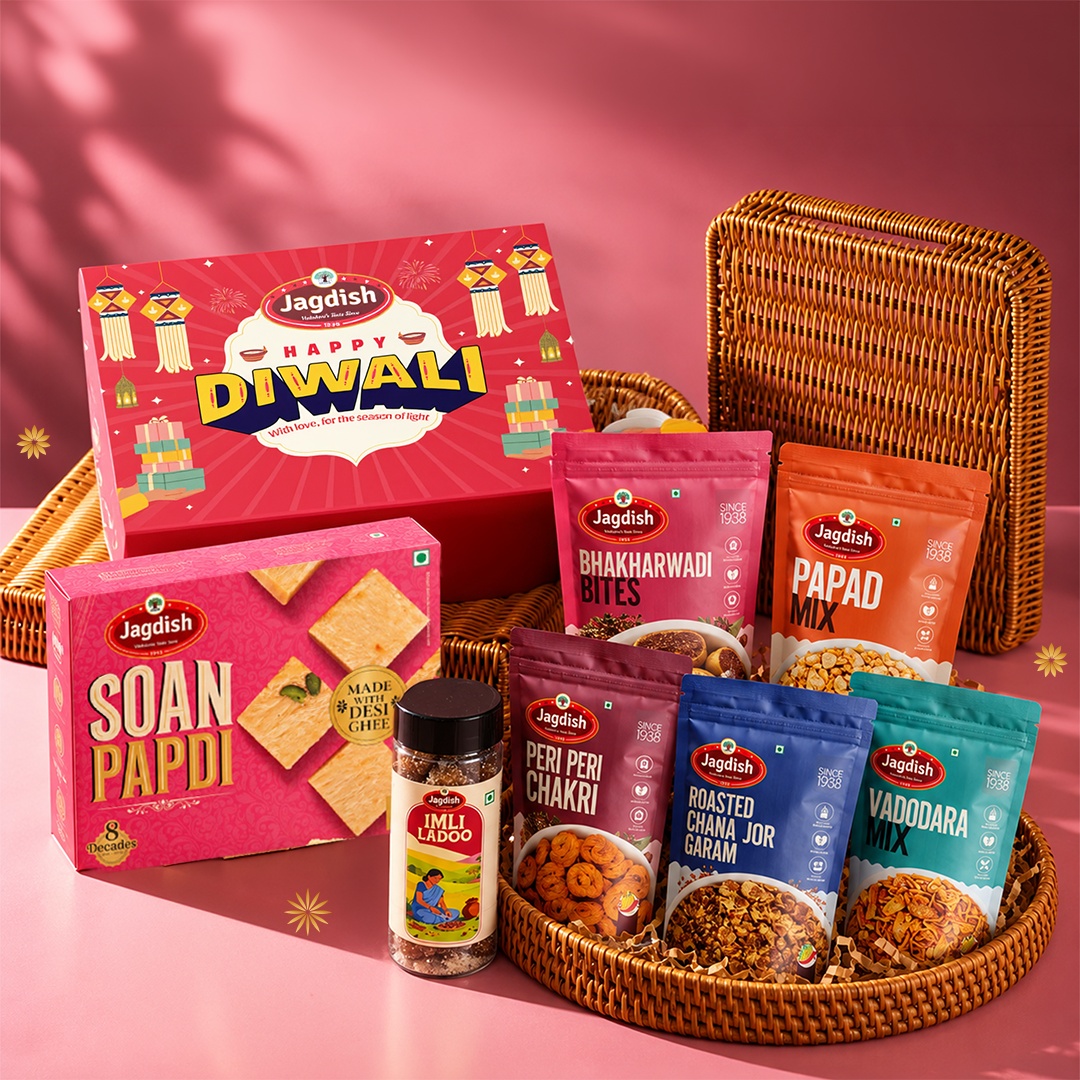
Aakash Kandoi, CEO and MD of Jagdish Farshan, said, "Diwali gifting this year is more considered than impulsive. Consumers are still spending, but they want each gift to carry meaning: heritage, quality and packaging that feels gift-ready."
Jagdish Farshan is recording 15 percent year-on-year growth in Diwali sales. Its popular gifting categories include festive hampers, mithai and namkeen. Starting at Rs 699, its hampers combine Gujarati farsan, traditional sweets and dry fruits.
The company's average order value ranges between Rs 1,100 and Rs 1,300, showing interest in larger gift assortments instead of individual boxes.
 Kandoi said, "Today's Diwali buyer is not choosing between tradition and modernity; they want both in the same box."
He added that customers are asking more questions about ingredients, oil quality, and sugar levels. As a result, dry-fruit sweets and baked or roasted namkeen are also finding demand.
Personalisation is another trend, with customers choosing their own assortments, adding messages and selecting festive packaging. Corporate buyers are also asking for branded hampers for employees and clients.
Jagdish Farshan expects to maintain at least 15 percent festive growth. The company sees opportunities in quick commerce, Tier II cities and demand from Indian consumers living in the US, UK and Canada.
Also read: From Premium Perfumes to Pocket-Friendly Scents
Home Fragrance Finds Space in Gifting
Apart from food products, home fragrance is emerging as another gifting option. Rising dry-fruit prices and the demand for affordable premium gifts are encouraging consumers and companies to explore alternatives.
Aarti Koya, CEO, EKAM, said, "Diwali 2026 is a volume year, not a ticket-size year."
According to Datum Intelligence, India's online festive season is expected to reach Rs 1.50-1.55 lakh crore in 2026, growing 25-29 percent over 2025.
Koya said EKAM is seeing more first-time buyers, repeat orders and demand for smaller gifts instead of one large hamper. The later Diwali date this year, November 8 compared with October 20 in 2025, has also pushed a larger share of purchases towards the final ten days.
Rising dry-fruit prices are another factor. According to figures cited by Koya from the Free Press Journal, pistachio and date prices have approximately doubled, while almond prices have increased around 35 percent year on year.
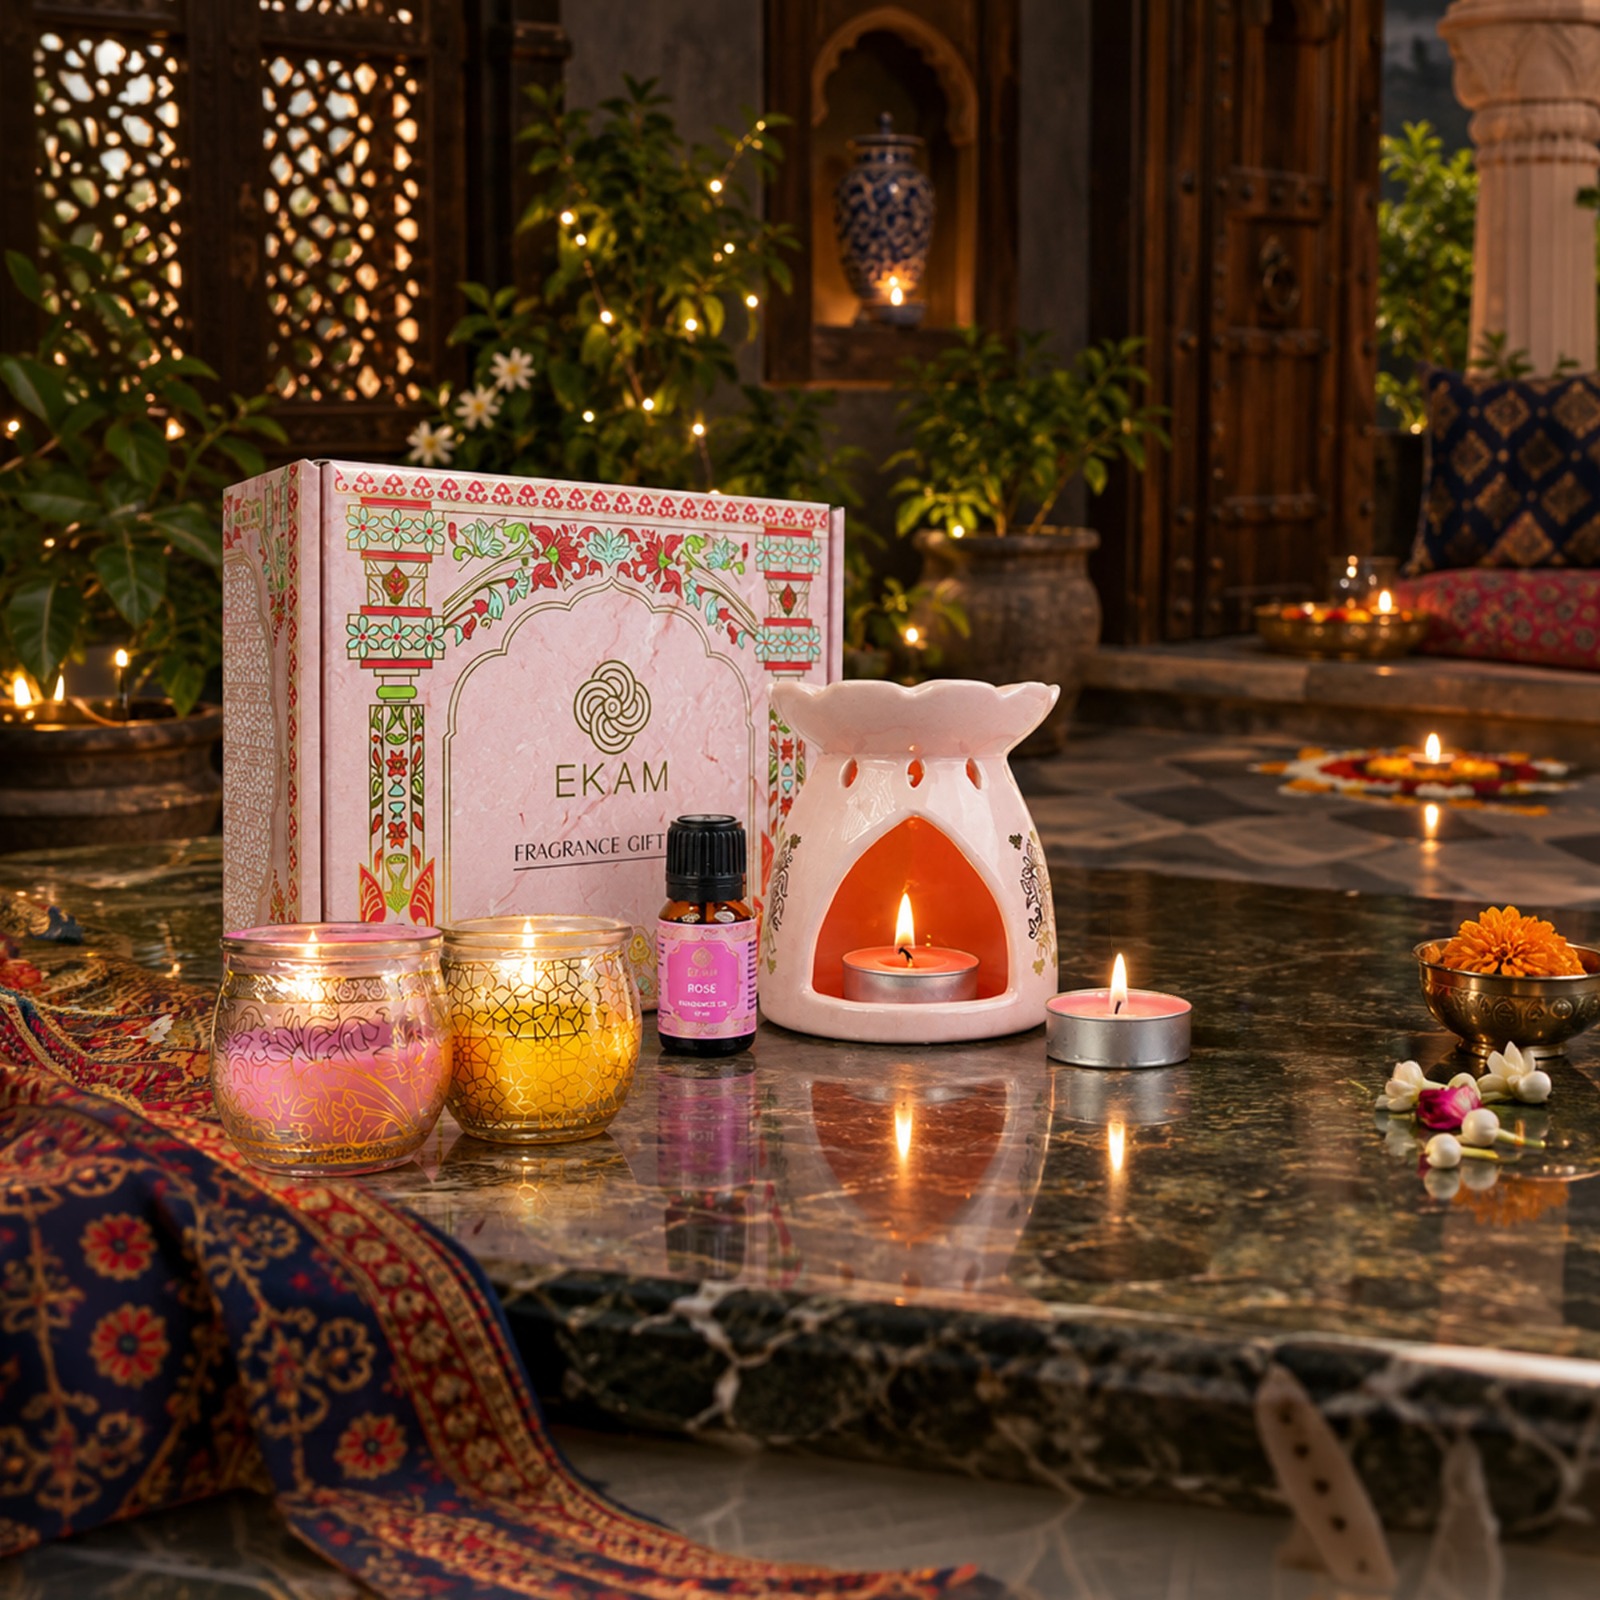 EKAM's Diwali-season sales are running 200 percent ahead of last year on a like-for-like basis. Festive candle gift packs, reed diffuser sets and corporate orders are driving demand.
The company has introduced 24 new gifting SKUs across three collections: Sheesh Mahal, Pink Haveli and Stone Palace. Its products are mainly priced between Rs 500 and Rs 1,000, while the Rs 1,000-2,500 segment is growing faster. Reed diffuser gift sets are popular in the Rs 500-750 range.
Founded in September 2020, EKAM is headquartered in Mangalore (Karnataka). Its average direct-to-consumer order value is around Rs 1,000, while corporate orders average Rs 1 lakh.
Koya said, "Premium means 'feels expensive', not 'is expensive'. Shoppers are comparing prices and prioritising value, and festive growth is coming from smaller, more frequent orders rather than bigger baskets."
The company has also expanded its presence across Amazon, Flipkart, Myntra, Blinkit, Swiggy Instamart and Zepto to reach last-minute shoppers.
Also read: Retail Sales Grow 8 Pc in September 2026 Ahead of Festive Season: Report
 Personalised Gifts Gain Demand
Consumers are also looking for gifts that are useful and match the interests of the person receiving them. This is creating opportunities for lifestyle and home products.
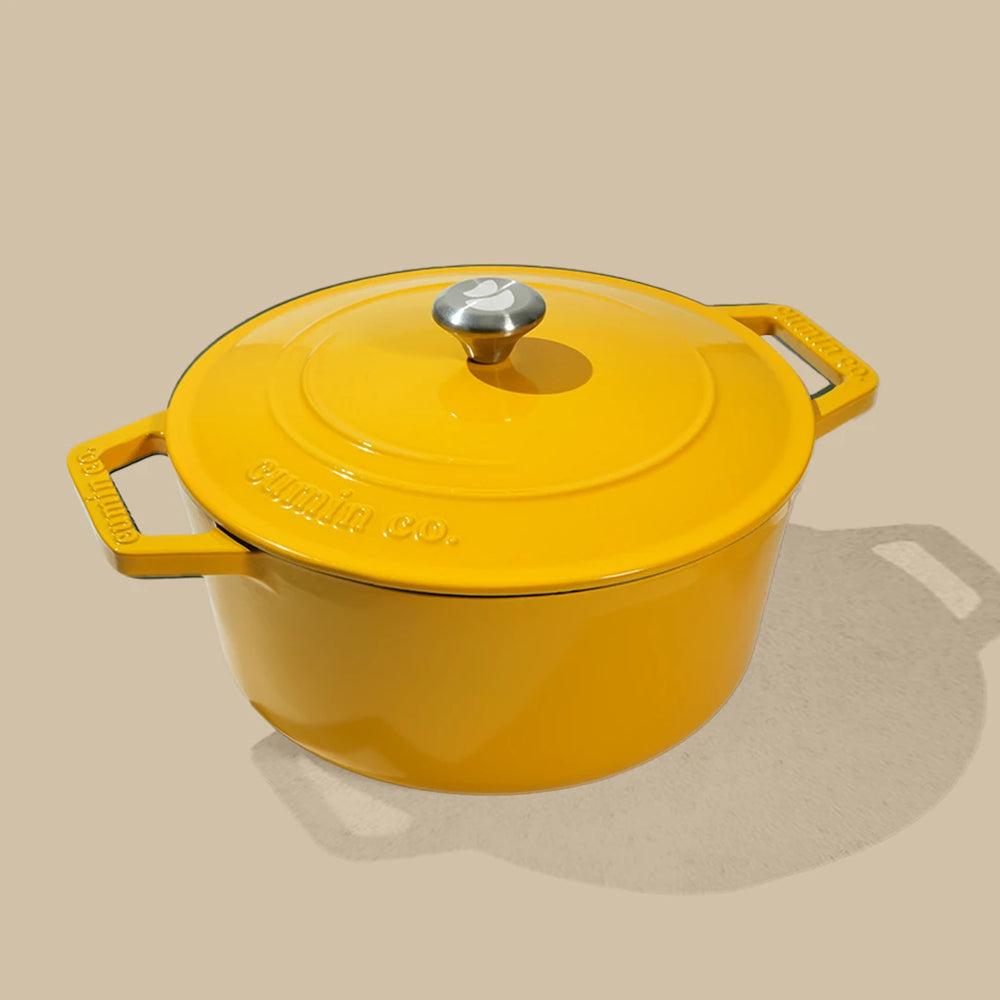
Niharik Joshi, Co-founder of Cumin Co., said, "One of the biggest shifts we've noticed is how deliberate and discerning consumers have become about gifting. People are no longer looking to simply pick up generic or random gift items."
The company has seen good demand for its Stash Boxes, which offer storage and everyday utility. It has also introduced a gifting concierge service to help customers select products, especially when buying gifts for several people.
Joshi said, "There is a growing preference for products that are unique yet useful, something that the recipient will genuinely enjoy and incorporate into their everyday lives."
She added that consumers are increasingly interested in products that combine design, quality, and functionality. The company has also received corporate gifting orders where buyers specifically asked for clean products.
According to Joshi, consumers may be purchasing fewer products but are willing to spend more on premium and well-designed gifts.
Also read: Premiumization Reshapes India’s Home Appliance Retail Market
 Corporate Gifting Expands
Corporate gifting is becoming an important part of the festive market, with companies looking for customised hampers, branded packaging and products suited to different budgets.
Brands are also extending their gifting collections beyond Diwali to weddings, housewarmings, employee milestones and other occasions.
Khetika is building its gifting range as a year-round offering, while Jagdish Farshan is focusing on customised food hampers. EKAM is offering co-branded packaging and bulk orders, and Cumin Co. is focusing on useful and design-led products.
Overall, India's Diwali gifting market is expanding beyond traditional sweets and dry fruits. Healthier food choices, personalised hampers, home fragrances and useful lifestyle products are becoming part of the festive shopping basket.
As consumers become more careful about what they buy and gift, brands are focusing on products that offer quality, good presentation and value.
A college student in Pune wants an iPhone with a genuinely good camera. A new one costs more than her monthly stipend can justify. A few years ago, her only real option would have been settling for a budget Android instead. Today, she has a third path that didn't really exist in any organised form a decade ago, a certified, warrantied, pre-owned iPhone at nearly half the price of new.
That shift, happening quietly across millions of similar decisions, is what's now being called India's upgrade economy, and the numbers behind it are hard to ignore. According to Counterpoint Research's Global Pre-Owned Smartphone Market Report for H1 2026, India's refurbished smartphone volumes grew 13 percent year on year in the first half of the year, even as sales of new smartphones actually fell by around 11 percent over the same period. That's not a small divergence. It suggests a genuine behavioural shift, not just budget conscious buyers settling for less, but buyers deliberately choosing better, older devices over newer, more expensive ones.
The same report found premium brands gaining ground specifically within the organised, certified segment of the refurbished market, a detail that matters more than it might seem. India's pre-owned electronics market has historically been dominated by unorganised sellers, roadside shops, informal resellers, classified listings with no real accountability if something goes wrong after the sale. Counterpoint's data puts the organised channel's share at roughly 20 percent of the total market, which sounds modest until you realise how much room that leaves for structured, trust-driven businesses to grow into.
This is really the crux of why the upgrade economy matters beyond just cheaper phones. Pre-owned technology has always existed in India. What's changing is the infrastructure around it, warranty coverage, quality certification, verification checks, and genuine after sales support, the same things that made buying new devices feel safe for decades.
A growing number of certified pre-owned platforms now illustrate this shift concretely. The stronger ones put every device through a documented, multi-point inspection covering hardware, software, battery health and cosmetic condition, alongside verification of activation lock status and device identity history, two checks that directly address the biggest fears buyers have historically had about used electronics, a stolen device, a hidden lock, a battery quietly dying within months. Many now offer up to twelve months of warranty, a short return window, and financing through EMI, features that used to be reserved almost exclusively for new device purchases. Trade-in and exchange programmes have also become common, letting customers put an older device toward a pre-owned upgrade, and some platforms operate physical stores in major cities, giving buyers somewhere to walk in and get support rather than relying purely on an online transaction with no recourse.
This model addresses something the broader market data hints at but doesn't fully explain on its own. Industry tracking through 2026 has repeatedly pointed to rising demand for higher-priced refurbished devices specifically, even as the cheapest segment of the refurbished market has been shrinking as a share of total sales. In other words, Indian buyers aren't gravitating toward pre-owned technology purely to save money at the bottom end. They're using resale and refurbishment markets to access premium technology they otherwise couldn't justify buying new, a phone with a great camera, a laptop capable of real creative work, a smartwatch with cellular connectivity.
That's a meaningfully different economy from the one refurbished electronics operated in a decade ago, when pre-owned essentially meant compromise. It's becoming a legitimate parallel path to ownership, one where the ceiling isn't "what can I afford new" but "what can I access certified and warrantied, at a price that makes sense."
What happens next likely depends on how much the organised segment of this market can grow relative to the unorganised one still handling roughly four out of every five refurbished transactions in the country. Trust, not price, is the actual bottleneck holding back faster adoption, and trust is built slowly, through certification standards, warranty follow through, and enough repeat customers willing to vouch for the experience.
For now, the trajectory looks fairly clear. As new device prices in India continue climbing, and certified pre-owned platforms continue building the infrastructure that makes pre-owned technology feel safe rather than risky, more buyers are likely to start their next upgrade not by asking which new phone to buy, but by asking which excellent, certified, pre-owned device they can now actually afford.
Authored By:
Manil Shetty is the Managing Director at Maple Digital Technology Intl. Pvt. Ltd.
-
India’s festive retail market is heading into another year of strong growth, but the nature of that growth is changing. Consumers are expected to shop more frequently, spread their spending across a wider range of categories and make smaller purchases rat
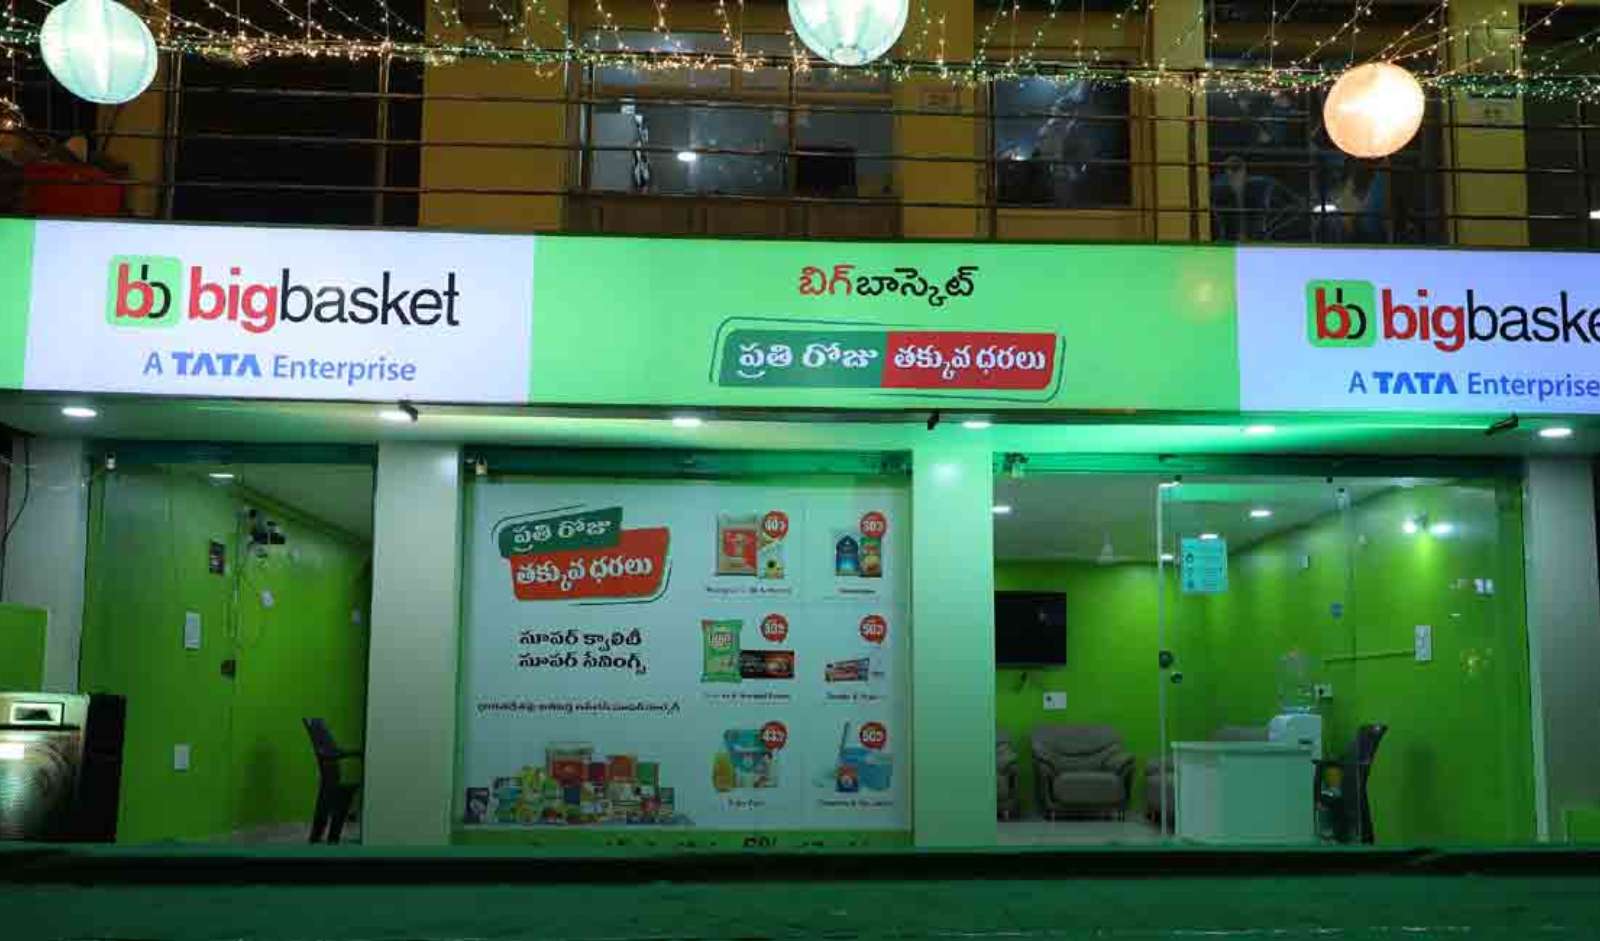 bigbasket reported strong demand for festive products during Diwali, with consumers increasingly using quick commerce for last-minute purchases. Electronics also recorded several-fold growth, supported by the platform's partnership with Croma.
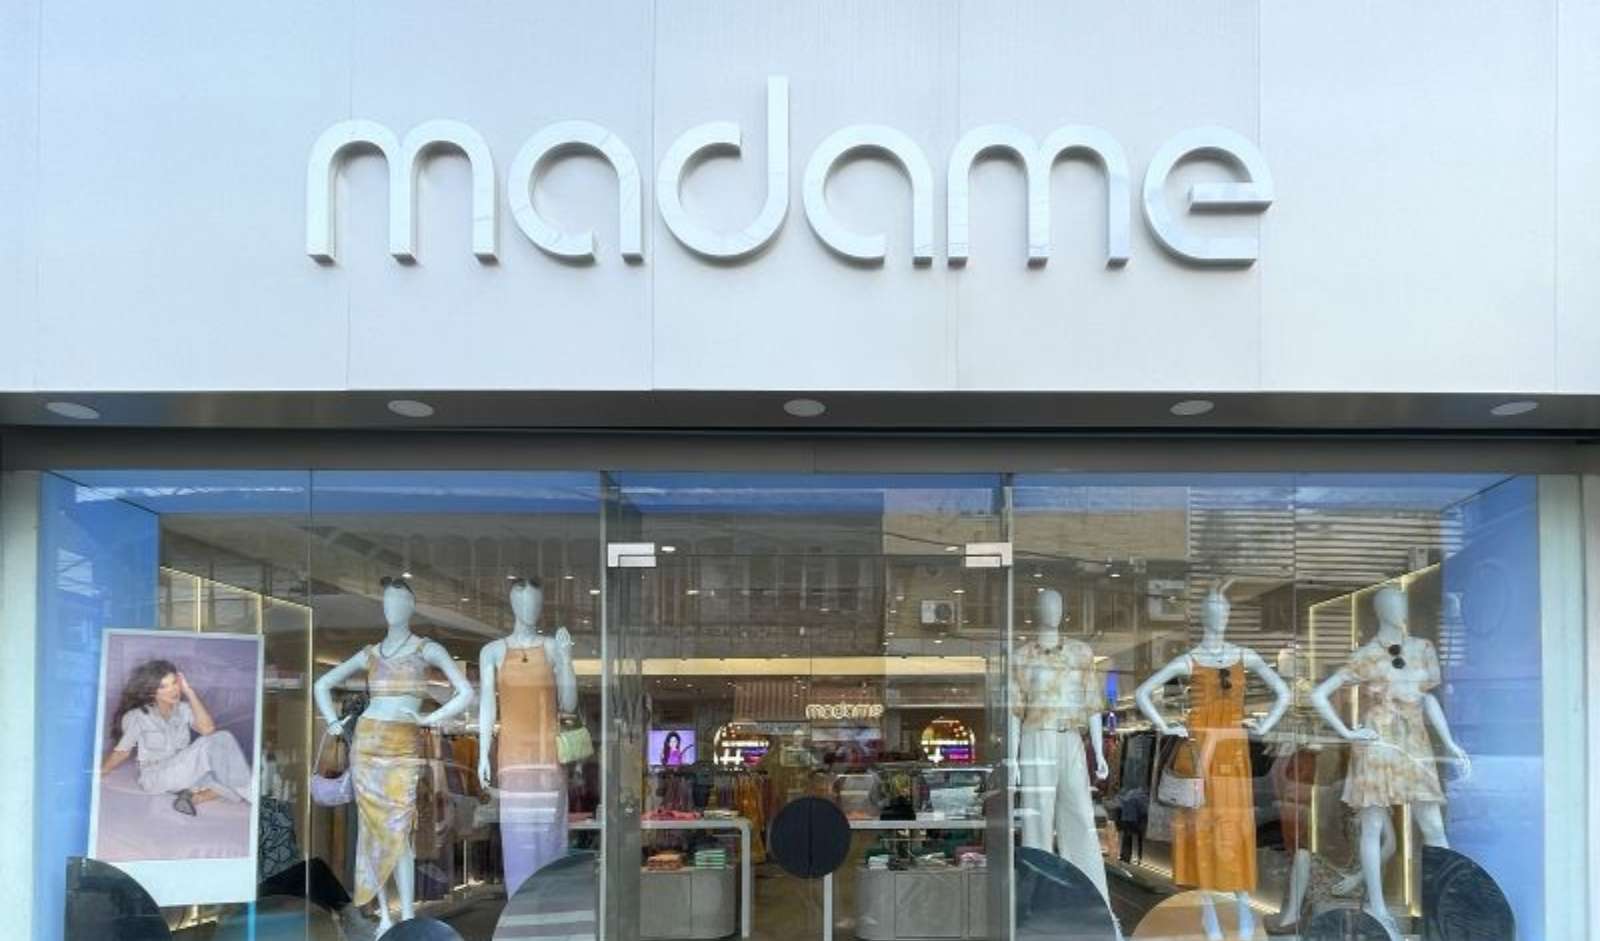 Women's westernwear brand Madame plans to expand its exclusive brand outlets from 125 to 200 by 2029. The company currently operates across more than 750 retail touchpoints in India.
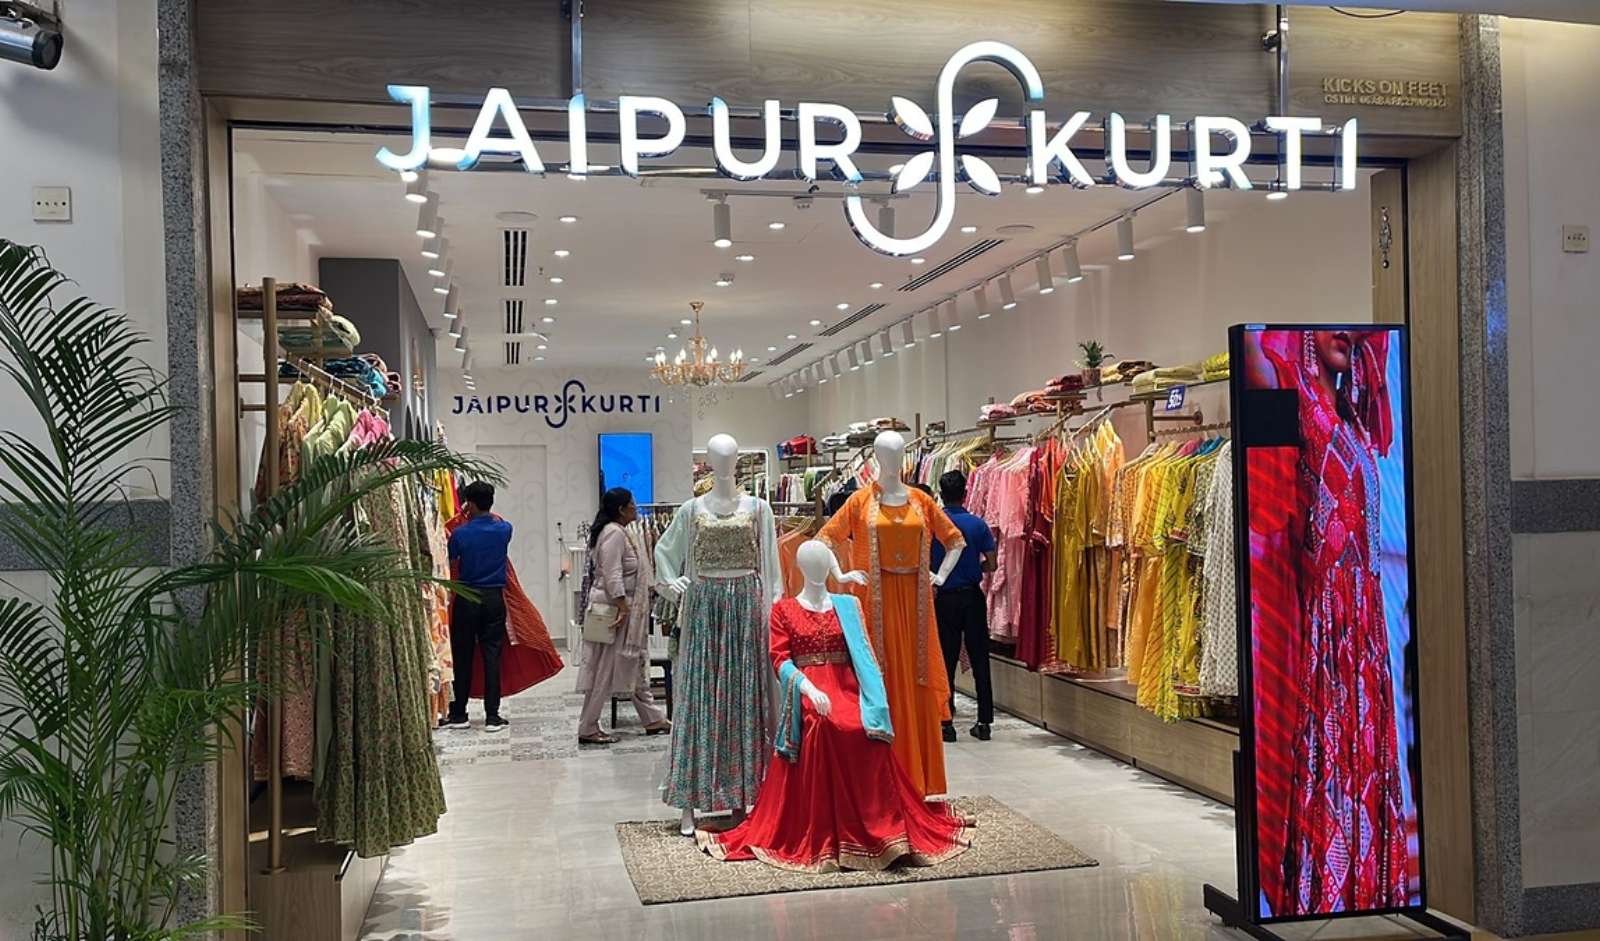 Nandani Creation reported Rs 70.4 crore in consolidated revenue during H1 FY27, registering 27 percent year-on-year growth. Online marketplaces contributed 36 percent of sales, followed by own channels at 32 percent.


Copyright © 2009 - 2026 Franchiseindia.com Ltd